HIVE Digital Technologies reported revenue of $84.9m for its fiscal second quarter to 30 September, up 7.3% on the previous quarter, as sales from its BUZZ HPC artificial intelligence cloud rose 71% from a year earlier. A $31.2m equipment writedown and heavy depreciation pushed the company to a net loss of $78.7m.
Bitcoin mining still pays most of the bills
The company, listed in Toronto and on Nasdaq, released the figures on 9 November and held its earnings call on 10 November. All amounts are in US dollars.
Bitcoin mining brought in $76.0m, up 5.5% on the June quarter but down 7.4% on a year earlier. HIVE received 1,070 bitcoin in mining rewards, against 1,004 in the previous quarter, helped by average network difficulty easing to about 128T from 135T. Executive chairman Frank Holmes pointed to a 27% fall in the bitcoin price over the year.
The HPC and AI business, run through the BUZZ HPC subsidiary, generated $8.8m, up 25.3% on the quarter and 70.7% on the year. It still makes up only about a tenth of group revenue.
Second quarter of fiscal 2027
- $84.9m total revenue, down 2.7% year on year
- $8.8m HPC and AI revenue, up 70.7%
- $139.0m cash at 30 September
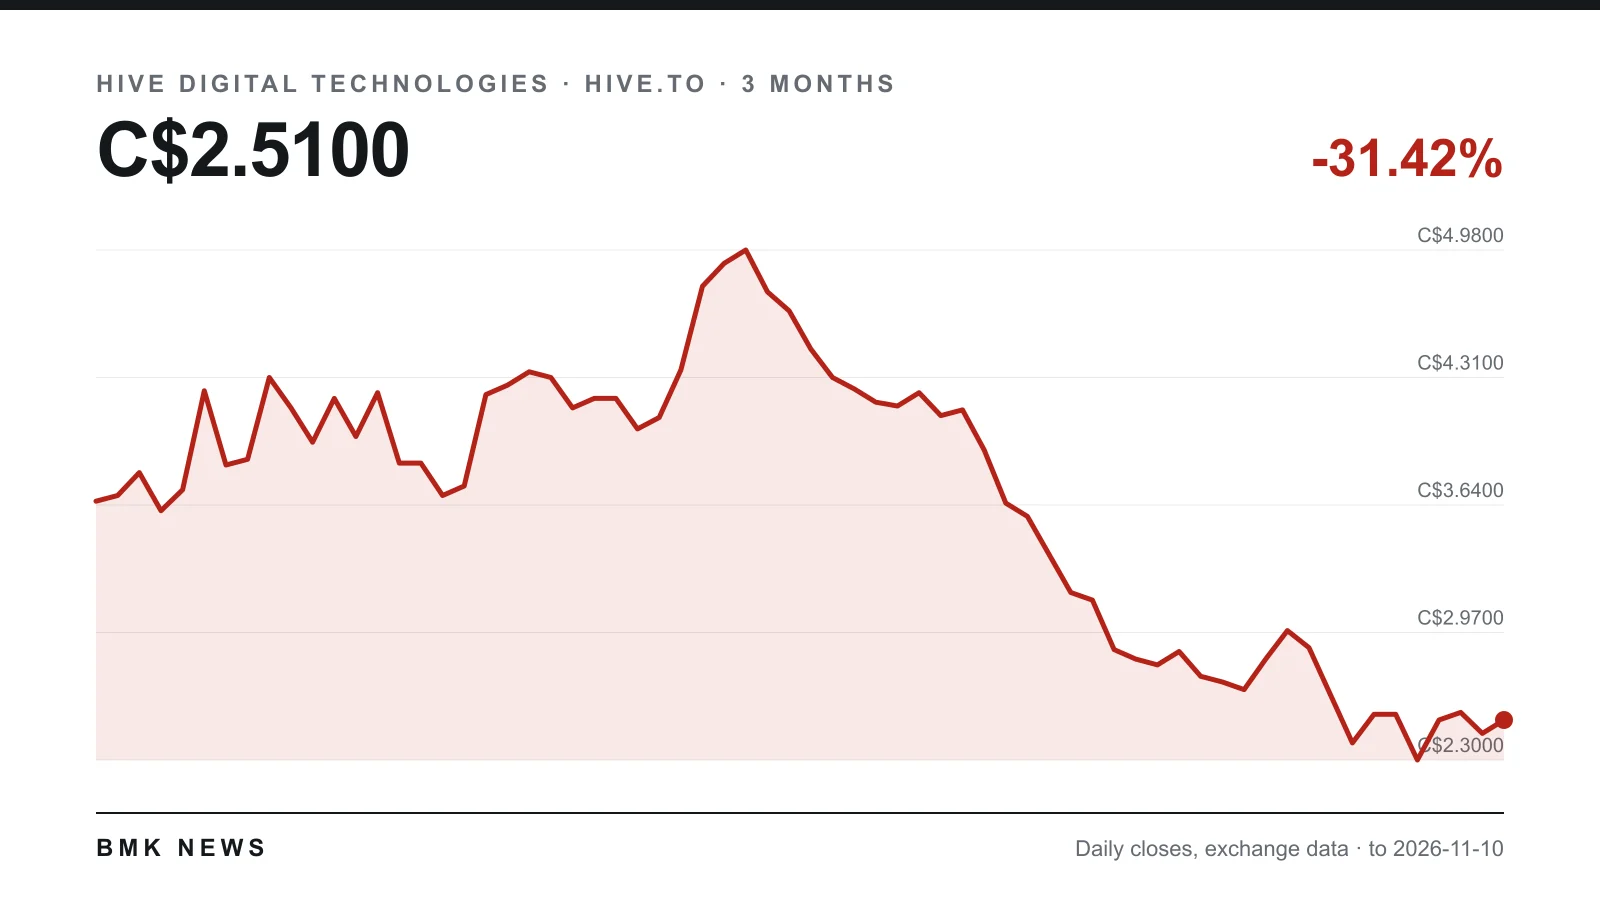
HIVE Digital Technologies: share price, chart and news
The loss came from writedowns, not cash costs
Gross operating margin, a non-GAAP measure that HIVE defines as revenue less operating, maintenance and HPC service costs, rose to $30.2m, or 35.6% of revenue, from $24.2m (30.6%) in the first quarter. Adjusted EBITDA climbed 85% on the quarter to $24.8m.
The accounting result was far weaker. The $78.7m net loss, or $0.29 a share according to the quarterly 10-Q filing, included $54.9m of depreciation, a $31.2m non-cash impairment of mining equipment after a recoverability review, $8.6m of share-based pay and a $7.3m loss on derivatives, mainly capped calls linked to its convertible notes.
Selling, general and administrative costs rose to $10.7m from $9.0m, which the company put down mainly to a lease at its Merritt facility for HPC expansion. Over six months, the filing shows a net loss of $221.6m on revenue of $164.0m, a figure that includes a non-cash provision for regulatory liabilities of $84.5m, almost all of it booked before the September quarter.
Contracted GPU revenue and the debt behind it
HIVE put live annualised GPU cloud revenue at about $40m and contracted annualised revenue, which includes capacity not yet in service, at about $185m. It targets a GPU cloud run-rate of about $200m by the fourth calendar quarter of 2026, subject to financing, deployment schedules and customer acceptance, and about $700m of total annualised HPC revenue by the end of 2028.
Two contracts carry most of that pipeline: a three-year sovereign AI agreement with Cohere worth about $225m, using roughly 2,300 Nvidia GB200 GPUs kept in Canada, and a five-year deal worth about $350m with an investment-grade enterprise customer covering 2,016 Nvidia GB300 GPUs.
On 27 October, BUZZ HPC arranged a loan of about $129m from an unnamed institutional lender to pay for the GB200 cluster, at a fixed 9% over three years and about 80% of the cluster's $165m cost. The GPUs are expected to ship before the end of the calendar year.
Key points from the quarter
- Bitcoin rewards rose to 1,070 BTC from 1,004
- Adjusted EBITDA of $24.8m, up 85% on the quarter
- Net loss of $78.7m after a $31.2m impairment
- About 13.7m new shares sold through the at-the-market programme for about $43.2m
What investors are watching
HIVE also funds itself by selling shares. In the quarter it issued 13,698,085 shares through its at-the-market programme at an average of $3.15 (C$4.38), raising about $43.2m before commission. The 10-Q shows 276,878,228 shares outstanding on 6 November.
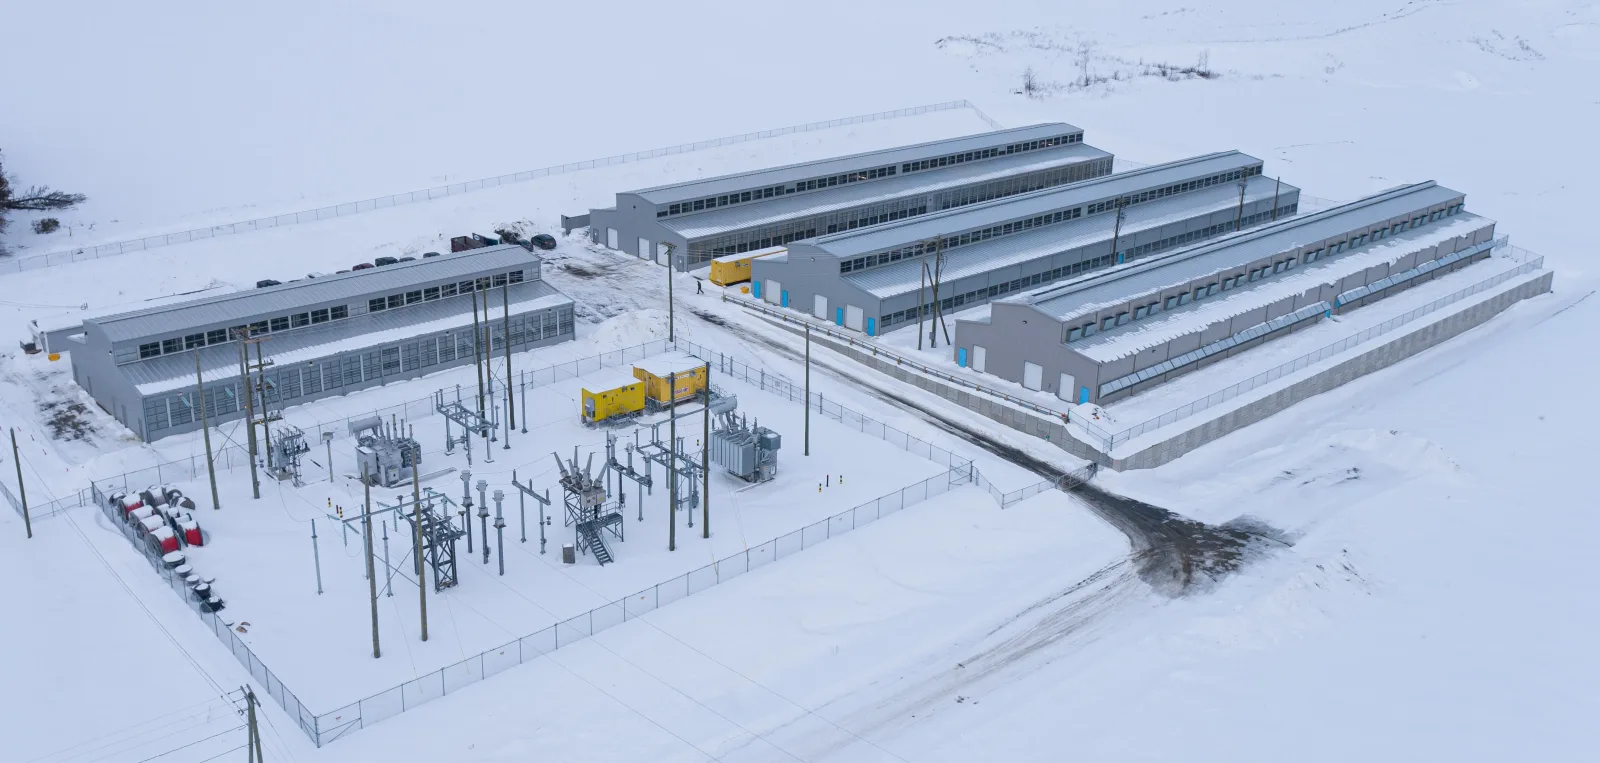
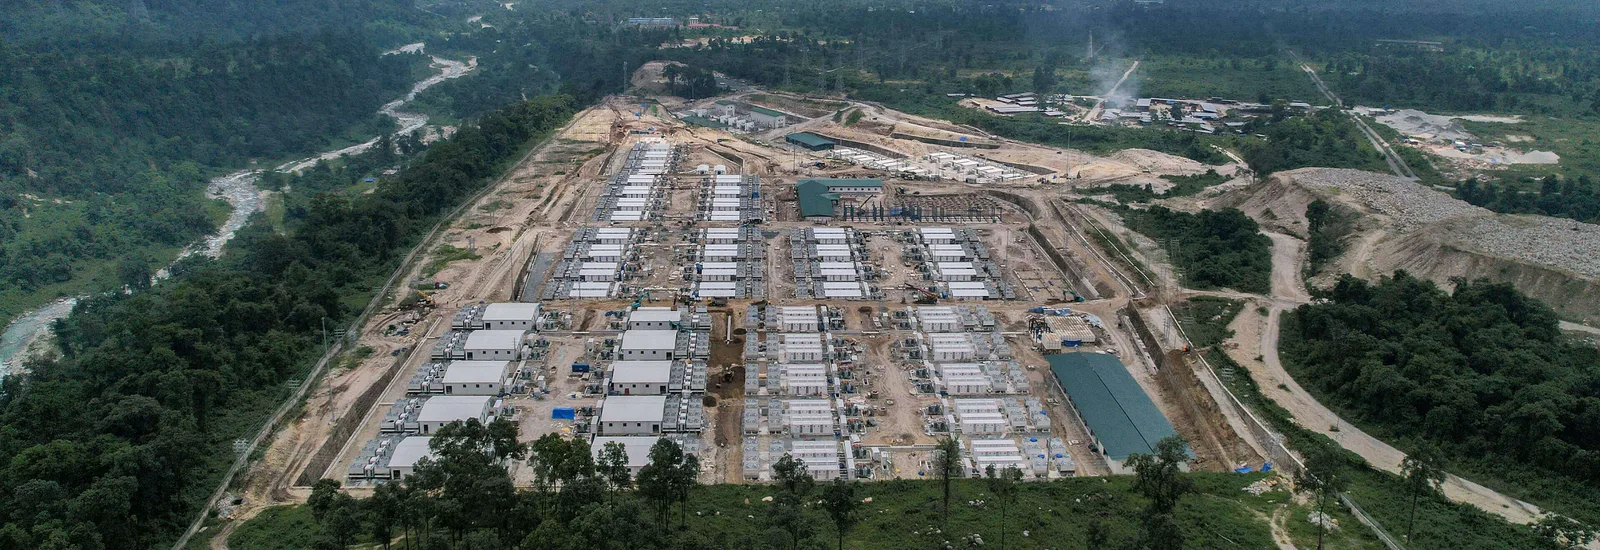
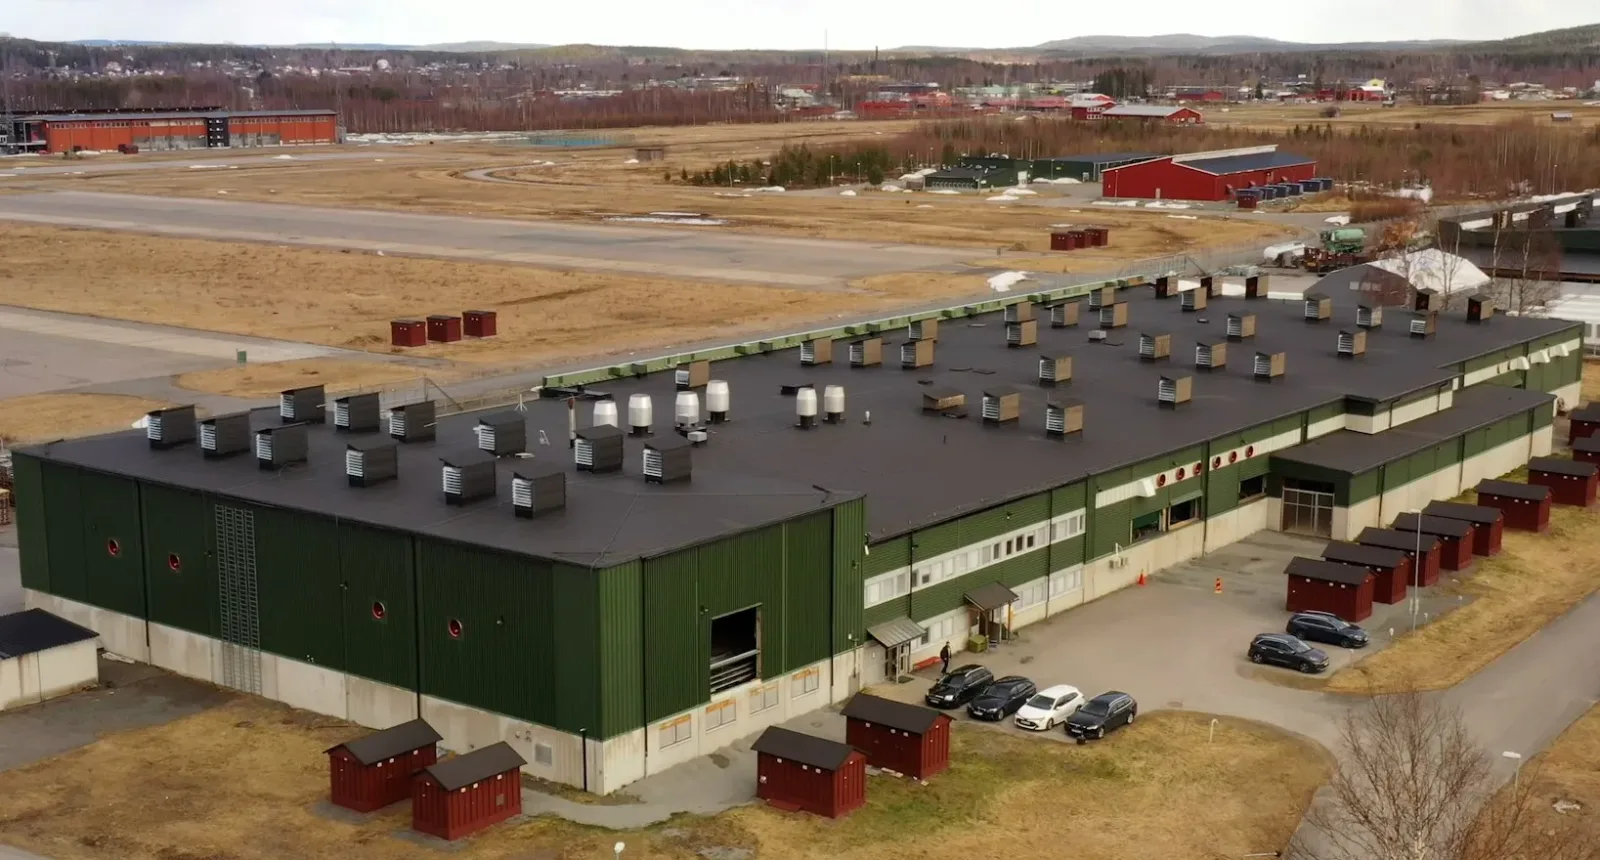
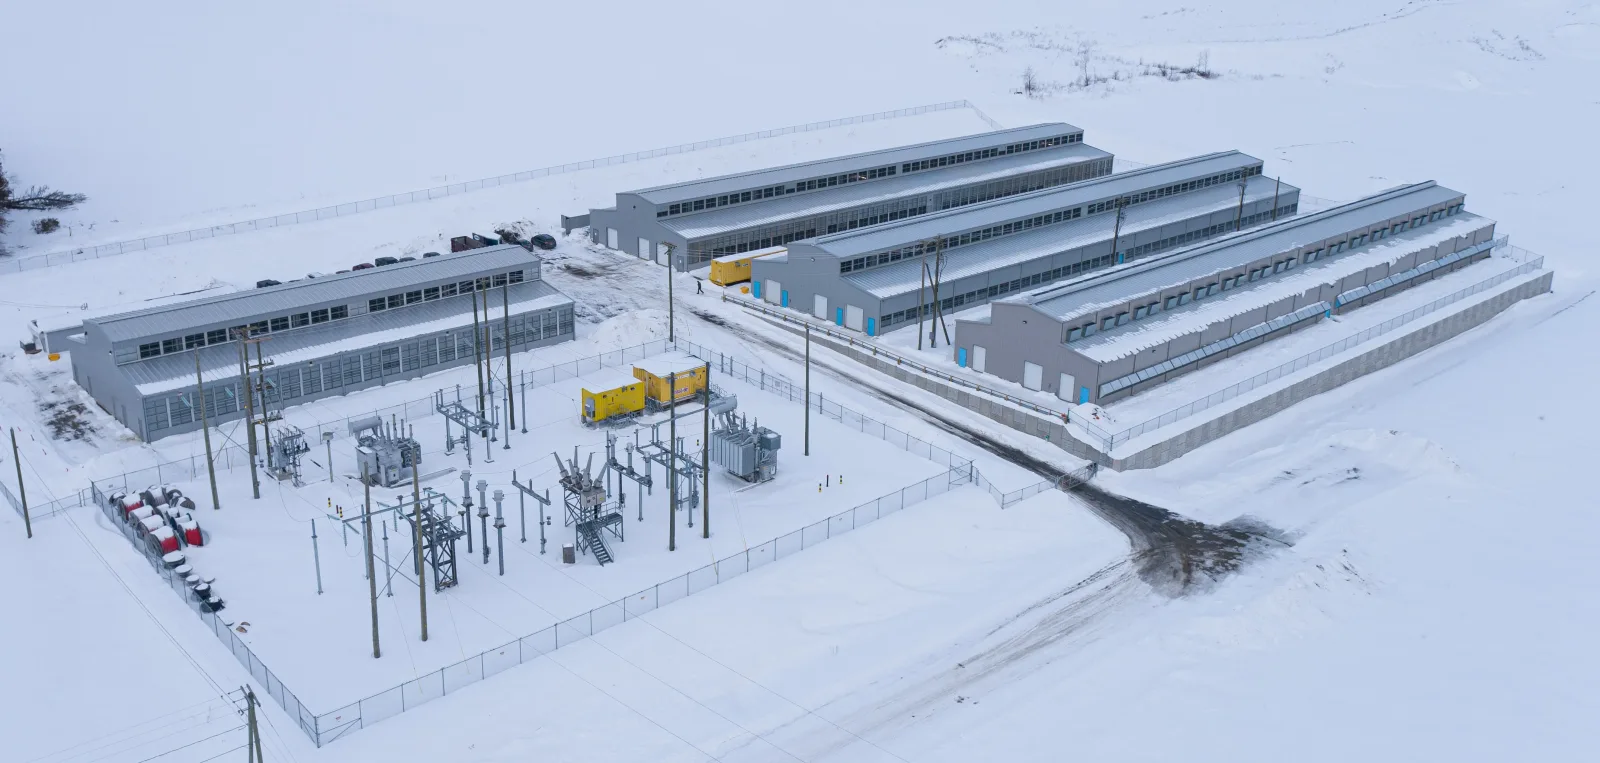
Power is the other constraint. The company has about 440 MW of capacity and expects to reach about 540 MW once a further 100 MW at Yguazú in Paraguay is energised in the fourth calendar quarter. It has a letter of intent for a 32 MW colocation project at Boden in Sweden, which it says could bring about $45m a year, but no binding agreement yet.
Kilic said demand for the chips had not eased: "GPU demand remains very high." The near-term tests are the delivery of the GB200 systems before year-end, the start of revenue from the two large contracts and whether the bitcoin price and network difficulty leave mining margins intact. As a loss-making company that keeps issuing shares and carries convertible notes and secured loans, HIVE also carries dilution and financing risk for shareholders.