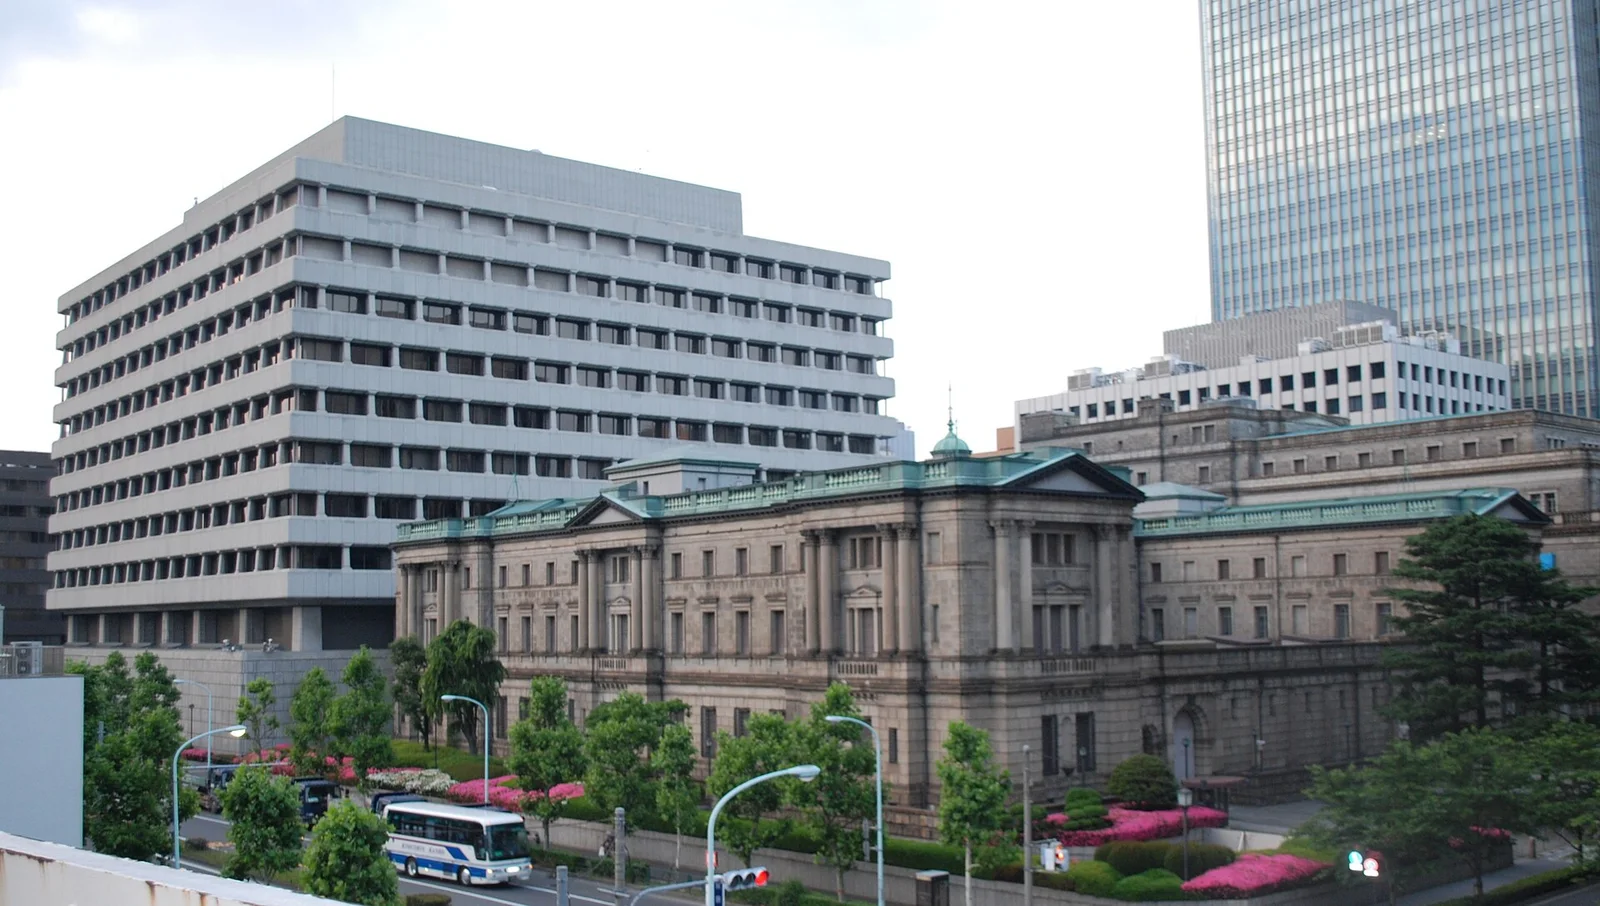
The Bank of Japan kept its policy rate at 1.25 percent on Friday but said it will sell its huge holdings of Japanese stock funds more than twice as fast from January, cutting the estimated time to unwind them from 112 years to 43.
An 8-1 Hold With a Hawkish Dissent
The decision, announced in Tokyo at the end of the October meeting, left the overnight call rate where September's quarter-point hike from 1 percent had put it. After quarter-point increases in June and September, Japanese borrowing costs are at their highest since April 1995. Markets had widely expected the bank to wait.
The vote was 8-1. Board member Hajime Takata proposed lifting the rate to 1.5 percent, arguing that underlying consumer price inflation had already reached the 2 percent target and that policy should move faster toward a neutral setting. The majority voted his proposal down.
A dissent in favour of a hike keeps the next meeting live. The board's next scheduled decision is on 18 December, and the vote count tells markets that at least one member already sees the case for moving.
ETF Sales Pace More Than Doubles
The bigger change was on the balance sheet. The board unanimously approved raising the annual pace of sales of its exchange-traded fund holdings to 860 billion yen on a book-value basis, from about 330 billion yen. That is roughly 0.1 percent of stock market trading value, against about 0.05 percent under the programme that started in January 2026. Measured at market value, the new pace is worth about 2.46 trillion yen a year. It takes effect in January 2027.
Bank of Japan, 30 October
- 1.25% policy rate, highest since 1995
- ¥860bn annual ETF sales from January 2027, up from ¥330bn
- 43 years estimated time to sell the holdings, down from 112
The bank built the stake during years of stimulus, spending 37.19 trillion yen on ETF purchases through March 2024. At the old pace, selling it would have taken an estimated 112 years; at the new one, about 43. Tohru Sasaki, a former Bank of Japan official, told AP that owning so many shares was "unhealthy for the central bank."
The board kept a safety valve. It may temporarily adjust or pause sales when markets are stressed, as long as it stays within the annual pace, and it said sales since January had gone smoothly while trading volumes grew. Sales of its holdings of Japanese real estate investment trusts stay at about 5 billion yen a year.
Markets: indices, currencies and commodities
Nikkei Slides as the Tech Selloff Spreads
Tokyo had a rough session. The Nikkei fell as much as 3 percent at one point as Asian markets extended a selloff in technology stocks on Wall Street. Government bonds rallied: the 10-year Japanese yield dropped 5.5 basis points to 2.780 percent, and 10-year US Treasury yields fell more than 7 basis points in Tokyo trade.
Futures pointed to a soft start in Europe. Euro Stoxx 50 futures were down 0.43 percent and DAX futures 0.2 percent lower, while S&P 500 e-mini futures fell 0.89 percent.
In size, the extra selling is modest. At about 0.1 percent of trading value, it is unlikely to move prices on a given day. The signal matters more: the central bank is now setting a timetable to step back from the stock market it once propped up, which removes a buyer of last resort that Japanese equity investors had come to count on.
Forecasts Point to Higher Inflation, Weaker Growth
The bank's new projections leaned in the direction Takata described. It raised its inflation forecast for fiscal 2027 to 2.6 percent from 2.4 percent and kept fiscal 2026 at 2.5 percent. It trimmed fiscal 2027 growth to 0.7 percent from 0.8 percent, while nudging fiscal 2026 growth up to 0.7 percent from 0.6 percent.
| Forecast | New | Previous |
|---|---|---|
| Inflation, fiscal 2026 | 2.5% | 2.5% |
| Inflation, fiscal 2027 | 2.6% | 2.4% |
| Growth, fiscal 2027 | 0.7% | 0.8% |
Inflation forecasts above target for two years, with growth stuck below 1 percent, are the mix that makes a gradual series of further hikes the market's base case.
Why the Yen Carry Trade Matters to European Investors
The decision capped a busy week for central banks. The US Federal Reserve held its range at 3.75 to 4.00 percent on 28 October in a 10-2 vote, the European Central Bank left its deposit rate at 2.50 percent on 29 October, and the Bank of Canada raised its rate by a quarter point to 2.50 percent.
Even at 1.25 percent, Japan still has the lowest policy rate of that group, and the wide gap with US rates continues to weigh on the yen. That gap is what feeds the carry trade, in which investors borrow cheaply in yen to buy higher-yielding assets elsewhere, including European bonds and equities.
Each step toward higher Japanese rates raises the cost of that trade. Markets saw in August 2024 how quickly a BoJ hike can force carry positions to unwind and spill into global stock markets. A board that is both selling equities faster and openly debating a move to 1.5 percent makes the yen, and the funding it supplies to global markets, a risk European portfolios need to track into December.