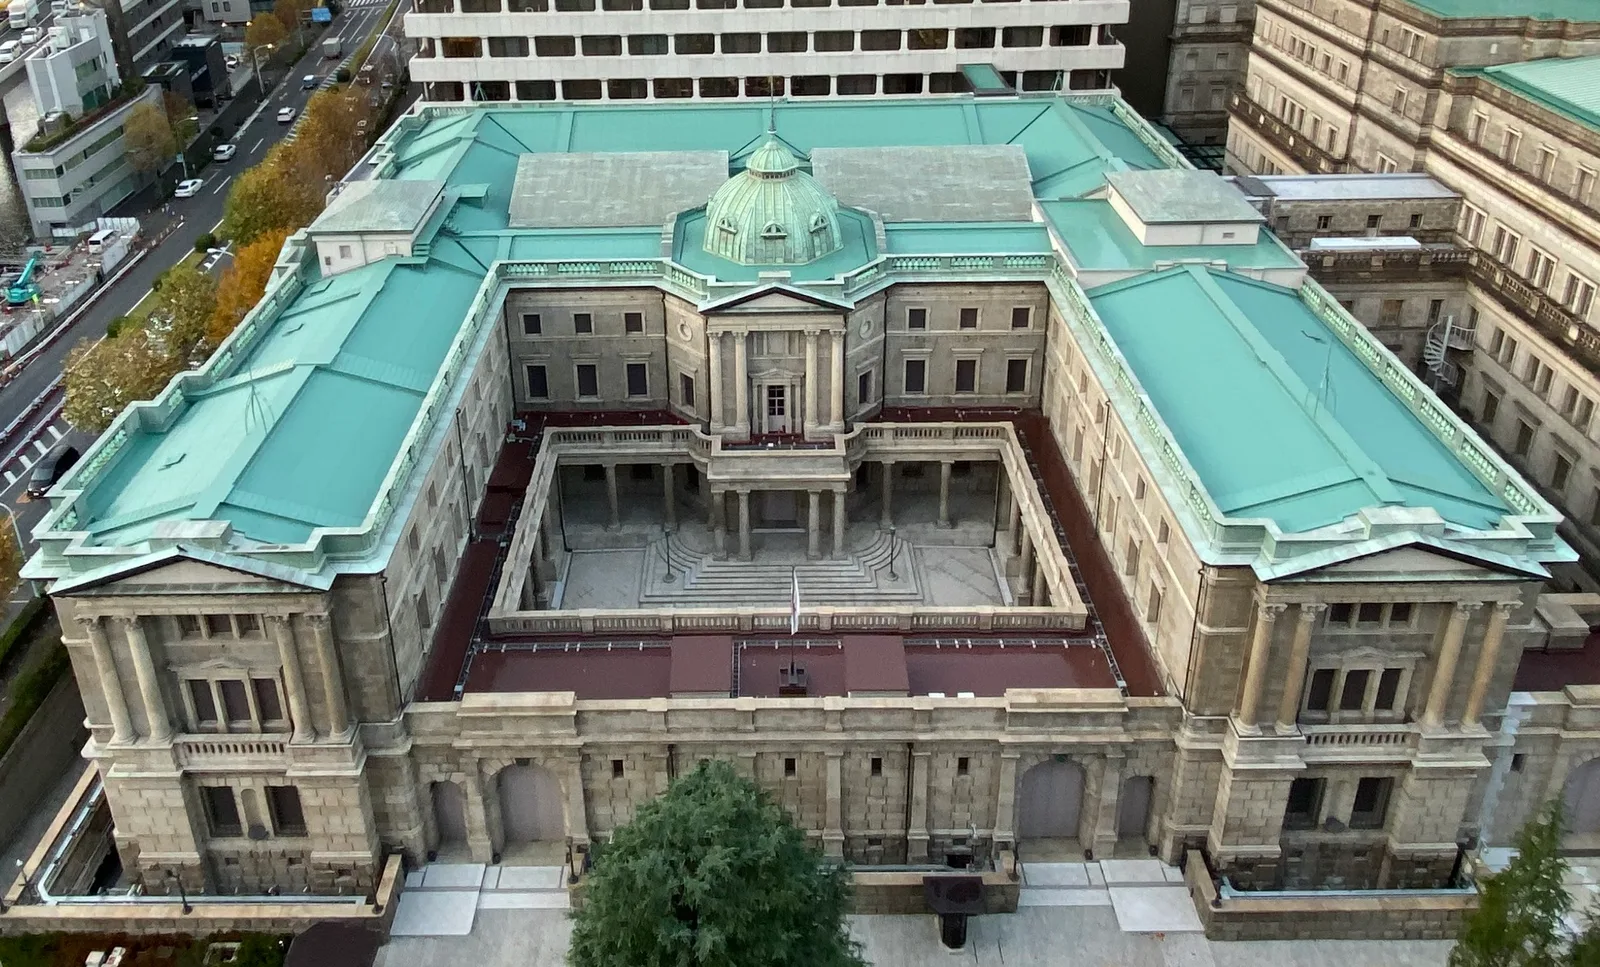
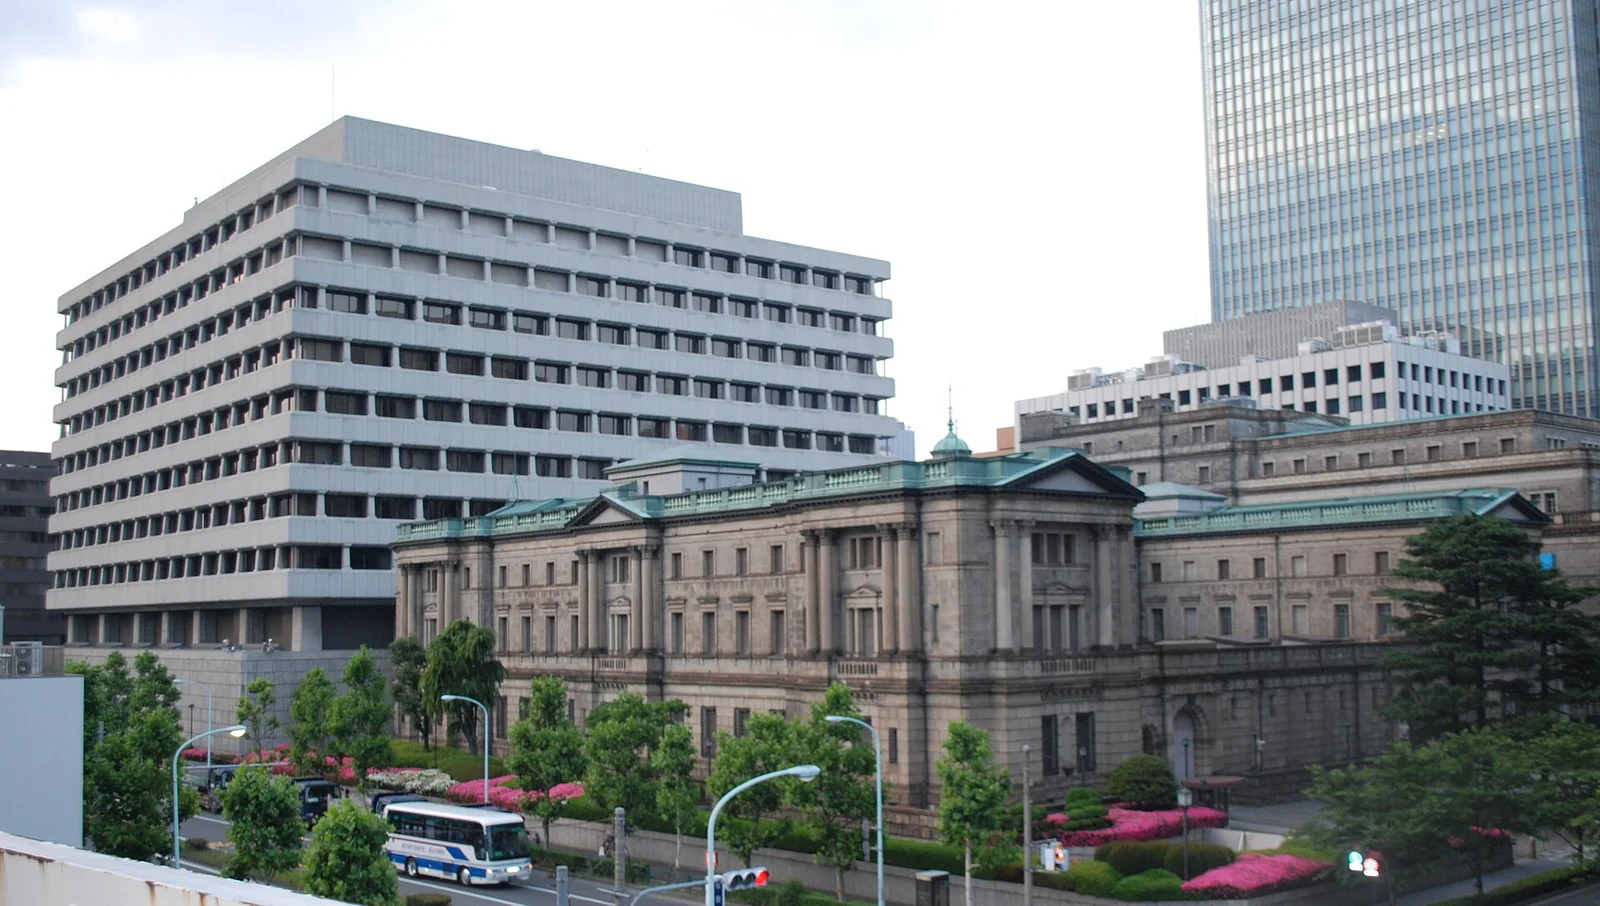
The Bank of Japan raised its policy rate by a quarter point to 1.25 percent on Friday, the highest level in 31 years, saying elevated wholesale inflation had started to feed through to consumer prices.
The decision, at the end of a two-day meeting, was the BoJ's first increase in three months and had been almost fully priced by markets. The board voted 7-2, with Toichiro Asada and Ayano Sato, both regarded as dovish members, dissenting.
It capped a week in which the major central banks leaned the same way. The US Federal Reserve raised its target range by a quarter point to 3.75 to 4 percent on Wednesday, its first increase in three years, and the European Central Bank had lifted its key rate to 2.5 percent the week before. The Bank of England held at 3.75 percent on Thursday, although three of its nine policymakers voted for a rise.
Japan's tightening in numbers
- 1.25% BoJ policy rate, up from 1%
- 7-2 board vote, with two dovish dissents
- 3.042% 10-year JGB yield on 15 September, highest since 1996
Why the BoJ Moved Now
In its statement the BoJ said wholesale inflation remained elevated and that price pressure from business-to-business trade had begun to reach consumers. It said underlying inflation "has been approaching 2%", as companies pass on higher wage costs and inflation expectations rise.
Reuters linked the pressure to several sources: the spike in energy costs caused by the war with Iran, expansionary fiscal policy, strong demand tied to investment in artificial intelligence, and a weak yen that raises the cost of imports. In July the BoJ had already warned of a risk that soaring fuel costs could push inflation above its forecasts.
Core consumer inflation held near the 2 percent target in August, as companies kept passing on higher costs for food and groceries. The bank said developments were in line with its baseline forecast, but it flagged a risk that underlying inflation could drift away from its target.
How Far Japanese Rates Can Go
The new rate sits inside the BoJ's own estimate of Japan's nominal neutral rate, the level that neither stimulates nor restrains the economy, which it puts at 1.1 percent to 2.5 percent. That wide band leaves open how far the tightening cycle can run.
Analysts polled by Reuters expected the policy rate to reach 1.5 percent by the end of March 2027, with a further rise to 1.75 percent after that. The bank has raised rates roughly twice a year since it ended its decade-long stimulus programme in 2024.
Governor Kazuo Ueda and his colleagues have avoided committing to a pace, saying it depends on the inflation outlook and on how earlier increases feed through to financial conditions. Ueda was due to hold a news conference at 0630 GMT, where investors will look for clues on the timing of the next step.
The Yen and Pressure From Washington
Critics have argued that the BoJ's gradual approach has helped keep the yen weak, and the gap between Japanese rates and those set by the Fed and the ECB remains wide even after Friday's move. That gap could keep the currency under pressure.
The yen has also become a diplomatic issue. US Treasury Secretary Scott Bessent said he had voiced strong support for decisive monetary steps to counter its weakness when he met Ueda this month, according to Reuters. Bessent also urged Prime Minister Sanae Takaichi's government not to expand fiscal stimulus, the news agency reported, citing sources.
Why European Investors Are Watching Tokyo
Japanese government bond yields have already climbed sharply. The 10-year yield rose 4.9 basis points to 3.042 percent on 15 September, its highest since 1996. On the same day the 10-year US Treasury yield topped 5 percent, Brent crude settled at $108.03 a barrel, and Europe's Stoxx 600 closed at 633.77, its lowest since 12 June.
Higher yields at home give Japan's large institutional investors, among them life insurers and pension funds, more reason to keep money in domestic bonds instead of buying foreign debt, including European government bonds. A steady rise in Japanese rates therefore adds to the upward pressure on borrowing costs elsewhere, at a time when energy prices and heavy government issuance are already pushing in the same direction.
For currency and bond markets, the next signal is Ueda's guidance. A clear hint at another increase before the end of March would point to a faster path than analysts expect, while a vague message would leave the yen exposed to the wide rate gap with the US and Europe.