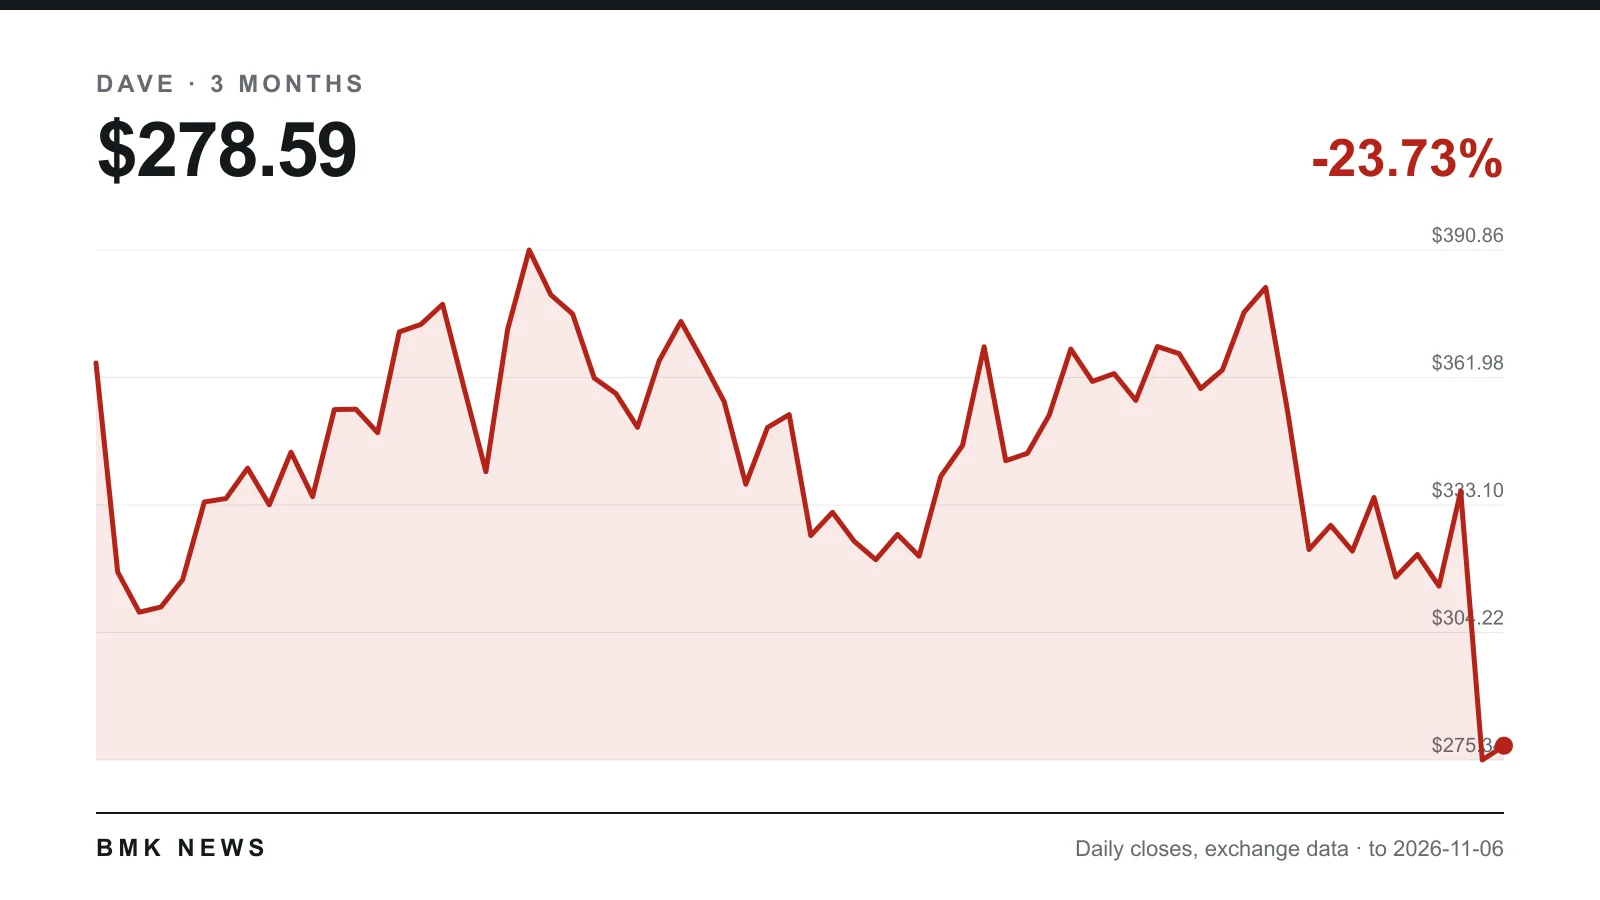
Dave, the US neobank best known for its ExtraCash advances, raised its 2026 outlook again on 4 November. The quarter also brought higher credit costs and an adjusted earnings miss, and the shares fell 18.1% to $275.34 on Thursday, their first session after the results.
A Faster Quarter With a Thinner Margin
Revenue for the three months to 30 September rose 31% to $197.7m, from $150.8m a year earlier. Adjusted EBITDA, which leaves out stock-based pay, litigation costs and other items, rose 39% to $81.5m, a margin of 41%.
The weaker figures came further down. Adjusted earnings per diluted share slipped to $4.39 from $4.45 a year before, and adjusted net income fell 7% to $60.3m. According to Earnings Whispers, analysts had expected adjusted earnings of $4.45 a share on revenue of $191.15m, so Dave beat on sales and missed on profit.
Net income under US accounting rules fell 31% to $63.8m, or $3.30 a diluted share. The year-earlier figure was lifted by a $33.6m tax benefit, which included the release of a $27.4m valuation allowance. This year's figure included $26.3m of non-cash gains as the value of Dave's warrant and earnout liabilities fell.
Dave: share price, chart and news
Dave's third quarter
- $197.7m revenue, up 31% from a year earlier
- $36.6m provision for credit losses, up from $29.9m
- 70% non-GAAP gross margin, down from 72% in the second quarter
Credit Costs and Funding Weigh on the Margin
The provision for credit losses rose 22% to $36.6m. Non-GAAP gross margin fell to 70% from 72% in the second quarter, although it was still above the 69% of a year earlier.
Chief financial officer Kyle Beilman said about one percentage point of that drop came from moving ExtraCash funding to Coastal Community Bank, which happened faster than planned. That funding line had about $159m outstanding at the end of September, against $93m three months earlier. He said provisions explained most of the rest: changes to collections had brought repayments forward without reducing eventual losses, so the company has recalibrated its loss model.
"Q3 demonstrated the operating leverage of our model," Beilman said. Costs still rose quickly. Marketing spend grew by more than 50%, with advertising and activation costs up to $28.0m from $18.9m. Compensation and benefits rose to $43.3m from $24.8m, and stock-based pay roughly tripled to $22.0m.
Members, Advances and Late Payments
Dave added 1.135 million new members in the quarter, 35% more than a year earlier, at an acquisition cost of $22 each. Monthly transacting members rose 18% to 3.15 million, under a new definition that leaves out members who only use its Goals savings feature.
ExtraCash originations rose 23% to $2.5bn. The share of advances 28 days past due improved to 2.09% from 2.15% a year earlier, and fell below 2% in September. Dave's monetisation rate on ExtraCash, net of losses, rose to 5.2%, which it says is the highest in five years, after it relaxed older fee caps. The average advance reached $225 in September.
Guidance Raised Again
Dave now expects 2026 revenue of $746m to $750m, up from $725m to $735m, which implies fourth-quarter revenue of $219m to $223m. Adjusted EBITDA guidance rose to $327m to $330m, from $315m to $325m, and adjusted earnings per share to $17.45 to $17.65, from $17.00 to $17.50.
Management expects the 28-day past-due rate to stay below 2% in the fourth quarter and non-GAAP gross margin to climb back above the second quarter's 72%.
Shares Give Back Their Pre-Results Gain
The stock rose 6.8% to $336.22 on 4 November, before the figures came out after the close. On 5 November it fell to $275.34, after touching $258.05, on volume of 1.47 million shares against 513,900 the day before. The close left the shares 28% below their 22 October level of $382.39.
The balance sheet is stronger than a year ago. Cash, restricted cash and investments reached $315.1m at the end of September, up from $123.2m at the end of 2025, and Dave repaid its $75m Victory Park debt facility in early October. It also carries $193.5m of convertible notes due 2031, issued this year. It spent about $20m on buybacks and on net settlement of staff share awards in the quarter, leaving $88m under its buyback authorisation.
The main risk outside the numbers is legal. The US Justice Department's lawsuit over Dave's marketing and fees, first filed by the Federal Trade Commission in November 2024, is unresolved, and Dave booked $6.2m of legal settlement and litigation costs in the quarter. It also faces a putative class action under the Military Lending Act, whose appeal is due for oral argument on 16 November, and consumer protection suits brought by the City of Baltimore and, since 28 September, a Pennsylvania district attorney.
Sources
- Dave Inc. (Form 8-K, Exhibit 99.1): Dave Reports Third Quarter 2026 Financial Results (2026-11-04)
- U.S. Securities and Exchange Commission (EDGAR): Dave Inc. Form 10-Q for the quarter ended 30 September 2026 (2026-11-04)
- Earnings Whispers (via Finviz): Dave misses on EPS as credit costs bite but accelerating revenue drives a fourth straight guidance raise (2026-11-04)
- Yahoo Finance: Dave Inc. (DAVE) historical prices (2026-11-13)
- U.S. Federal Trade Commission: FTC v. Dave, Inc. (case 232-3014) (2024-12-30)