Ondas, the US drone and defence technology group, doubled its revenue from the previous quarter to a record $167.5m in the third quarter and raised its 2026 forecast to at least $550m. Acquisitions drove most of the growth, and the company is still losing money at the operating level.
Revenue doubles in three months
Revenue for the three months to 30 September was $167.5m, the company said on 12 November, against $83.8m in the second quarter and $10.1m a year earlier. On a pro forma basis, which counts acquired businesses as if they had been owned in both periods, organic revenue grew 64% year on year.
Revenue for the first nine months reached $301.4m. Ondas has completed six acquisitions, including DZYNE Technologies, its largest so far, along with Cyberhawk, Gate/Bron, Ottopia, Insignito and Caribou Labs.
Ondas: share price, chart and news
Margins fall and losses widen
Q3 2026 at a glance
- $167.5m revenue, up 100% on the second quarter
- 21.8% gross margin, down from 43.1% in the second quarter
- $59.7m adjusted EBITDA loss, against $46.2m in the second quarter
The gross margin fell sharply. The company blamed higher amortisation of acquired intangibles, inventory written up in acquisitions, production inefficiencies in its precision strike business and early ramp-up costs, and expects similar margins in the fourth quarter. On its adjusted measure, which excludes several acquisition-related items, the margin was 34.8%.
Operating expenses rose to $226.0m, including $57.8m of share-based pay and $25.3m of amortisation, and research and development spending climbed by about $30m from the second quarter to $61.6m. The operating loss was $189.5m.
The net loss narrowed to $64.7m because other income of $133.1m included $125.1m of non-cash gains on warrants, which the company says make its earnings volatile for reasons unrelated to operations. The loss attributable to Ondas was $62.6m, or 10 cents a share.
A higher outlook and a $1.1bn target for 2027
| Target | Previous | 12 November |
|---|---|---|
| 2026 revenue | $525m to $550m | at least $550m |
| Q4 2026 revenue | - | more than $250m |
| Company-wide adjusted EBITDA break-even | Q4 2027 | Q3 2027 |
| 2027 revenue | - | at least $1.1bn, excluding new acquisitions |
Ondas repeated that it expects its operating platform to reach positive adjusted EBITDA in the fourth quarter of 2026. Chief executive Eric Brock said "This quarter demonstrates the growing benefits of Ondas' integrated operating platform".
Orders and backlog
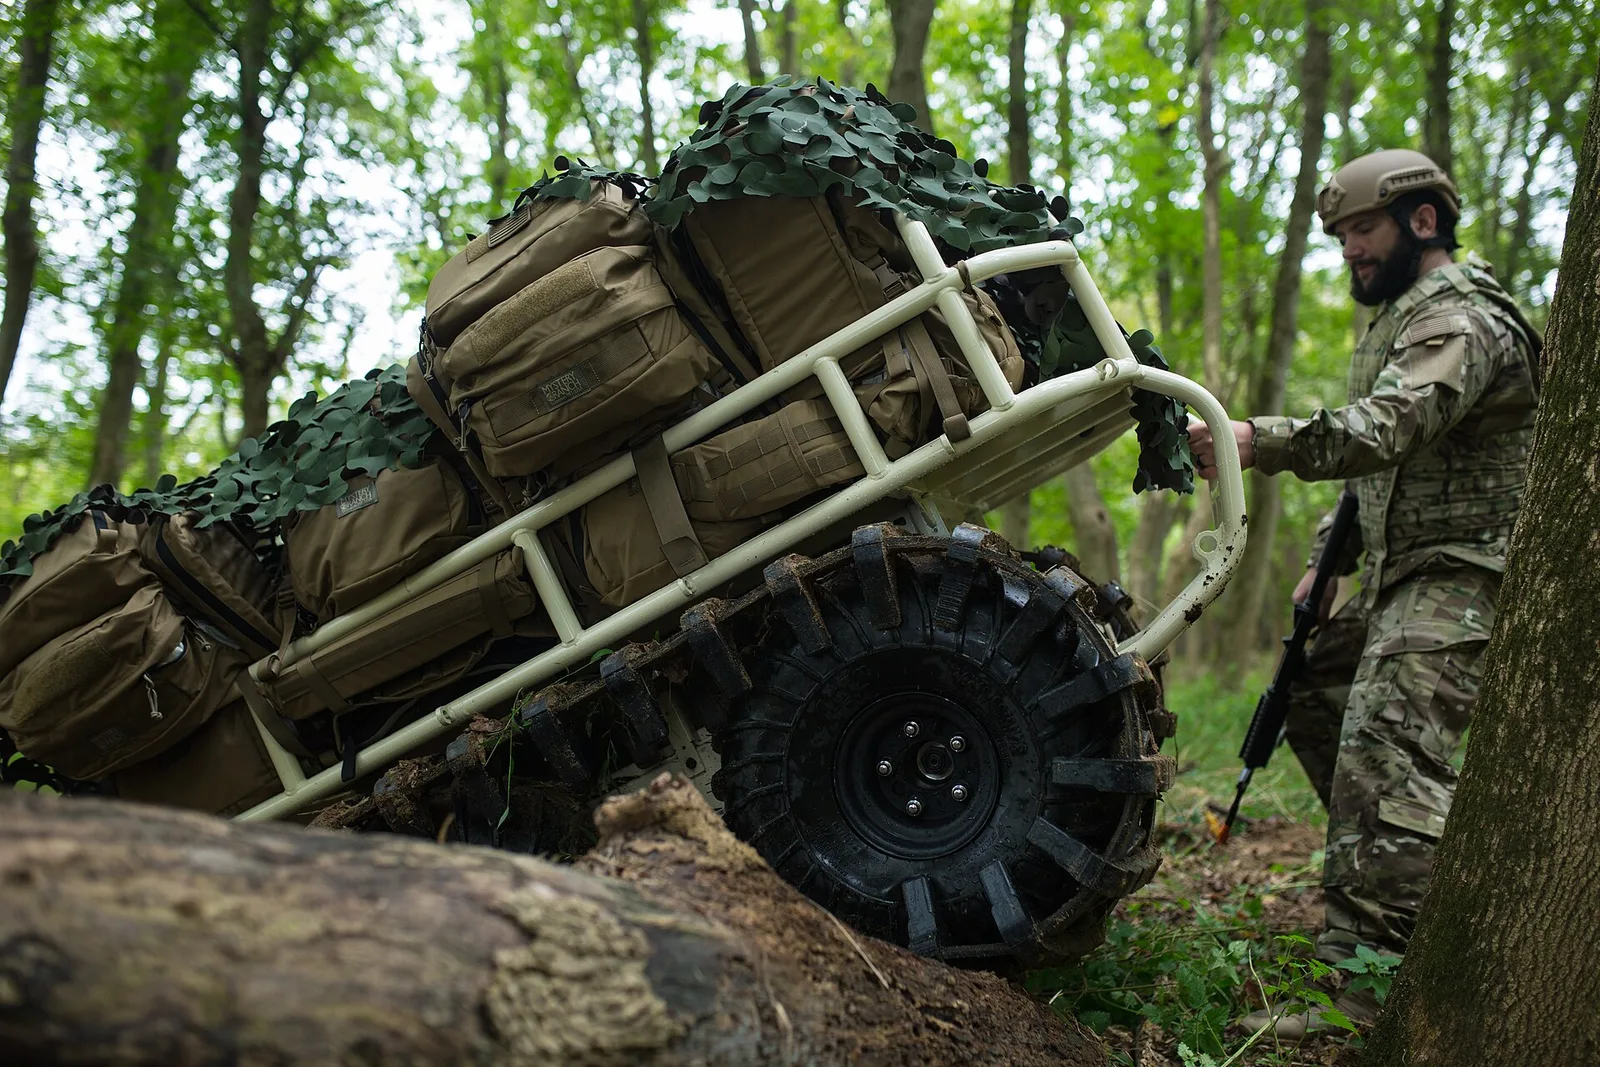
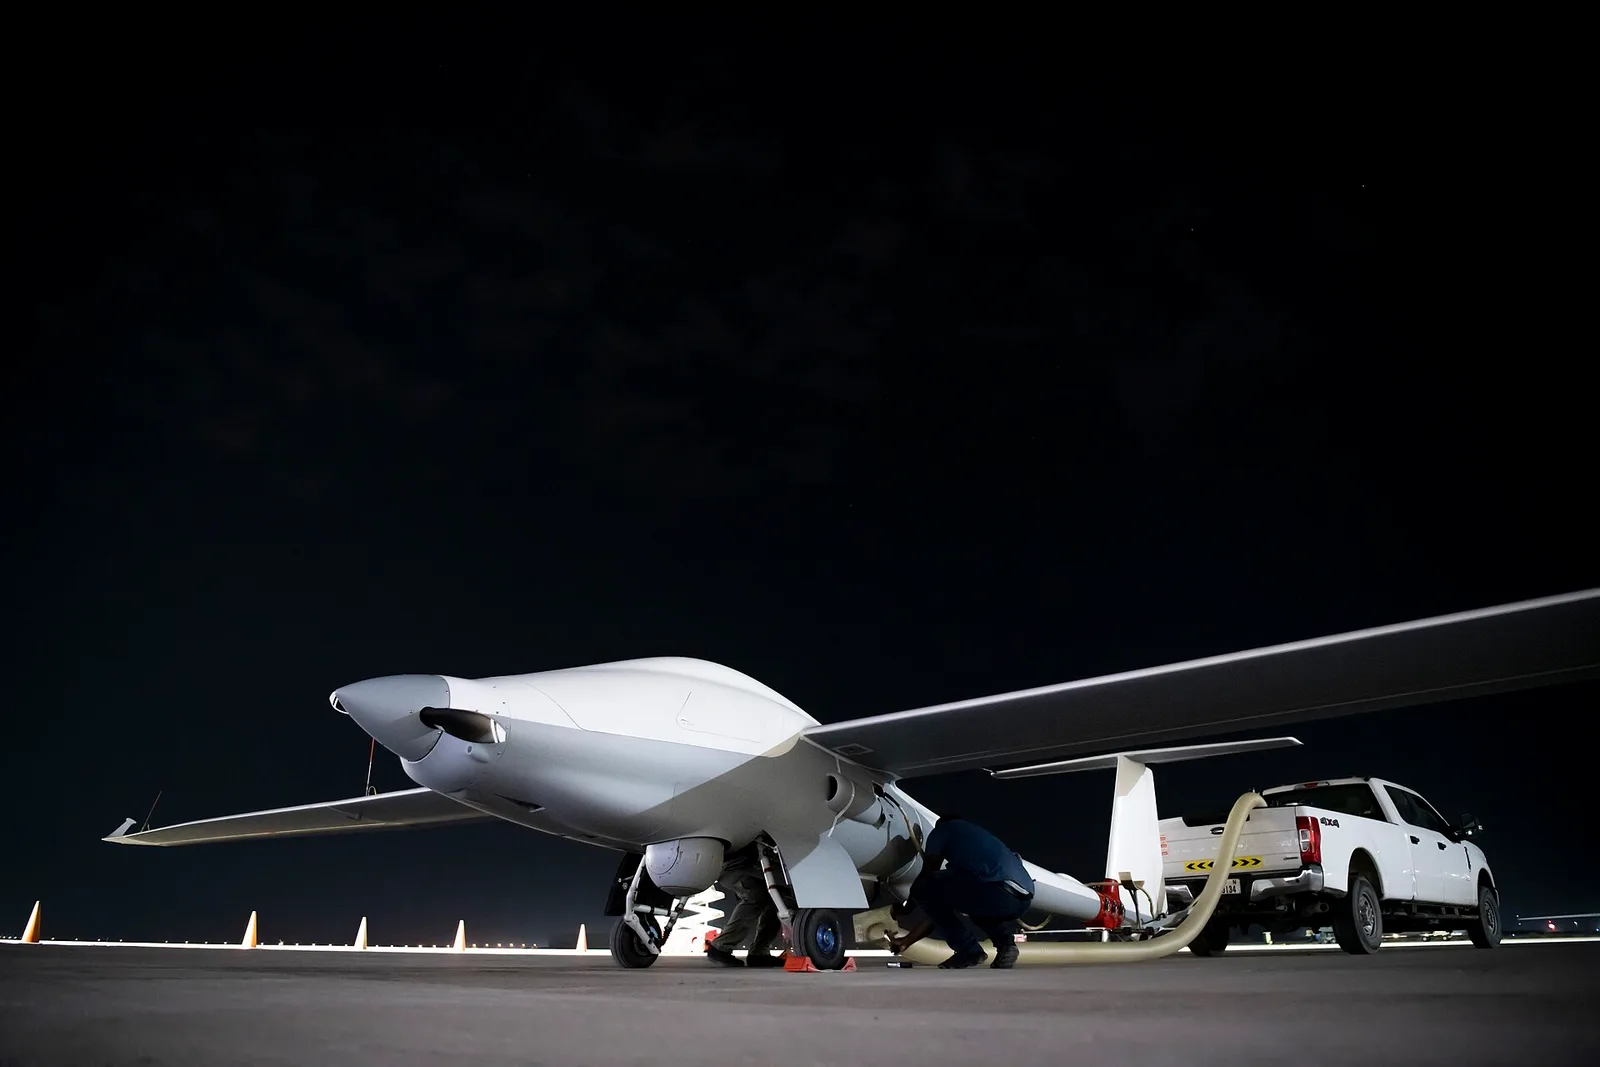
Backlog rose 36% from the previous quarter to $835m, and new orders in the third quarter totalled $214m. Ondas Sentinel, its US defence unit, booked $100m, including $53.7m of follow-on orders for the ULTRA long-endurance surveillance aircraft and $21.7m for IonStrike. A $140m combat engineering vehicle programme is due to start volume deliveries in the fourth quarter.
The company has agreed to buy Stemme, the German maker of the airframe used in ULTRA, for cash. That deal is expected to close in the first quarter of 2027.
Cash, dilution and risks
Ondas ended September with $820.3m of cash, restricted cash and short-term investments. The cushion was built by issuing shares: 590.2m were outstanding at 30 September, up 55% from 380.8m at the end of 2025.
Investors face several risks. Growth depends heavily on acquisitions, which bring integration work and amortisation charges, and the falling gross margin shows the cost of scaling production. Ondas still loses money on an adjusted basis, warrant gains make reported profits swing, and further share sales would dilute holders. Much of its revenue comes from defence and government buyers whose timing can slip.