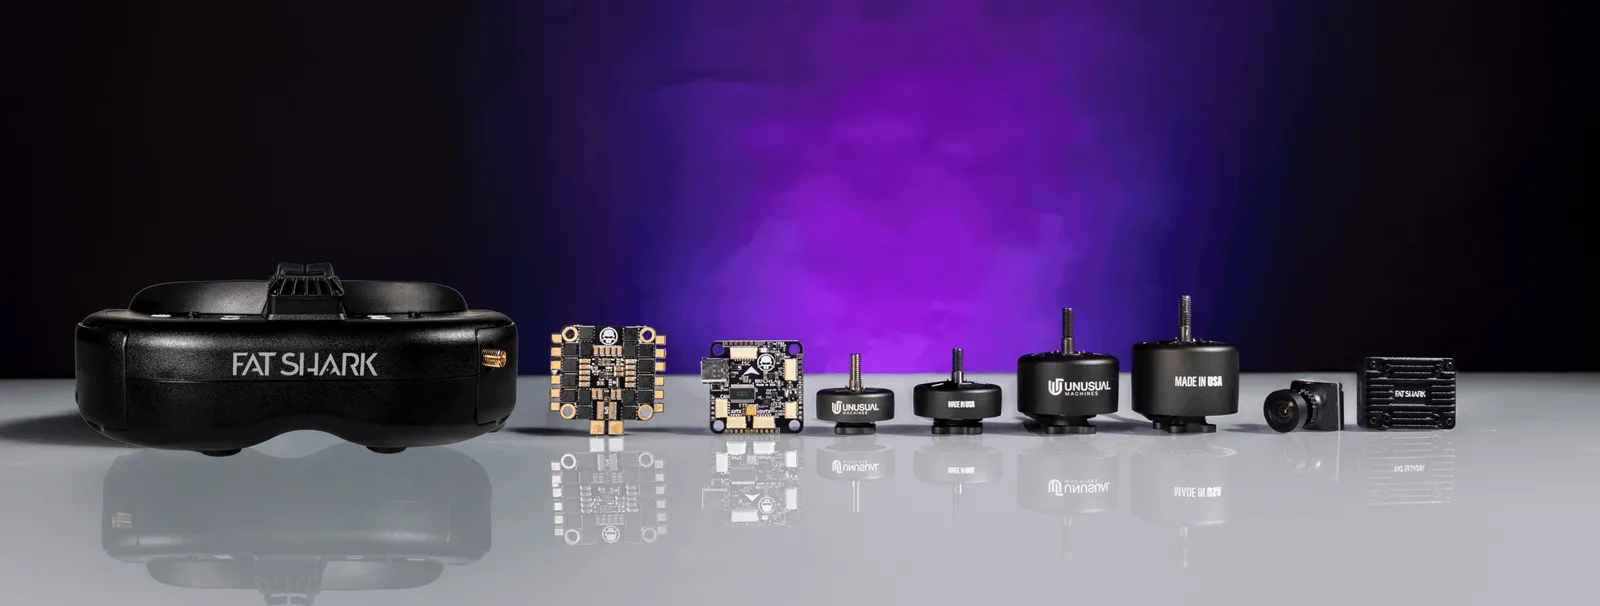
Unusual Machines makes the motors, cameras, controllers and now batteries inside small drones, and sells them mostly to American drone makers that supply the US military. Its revenue has grown more than sixfold this year, but the company is still loss-making, depends on a few customers and has invested heavily in some of them.
What Unusual Machines does
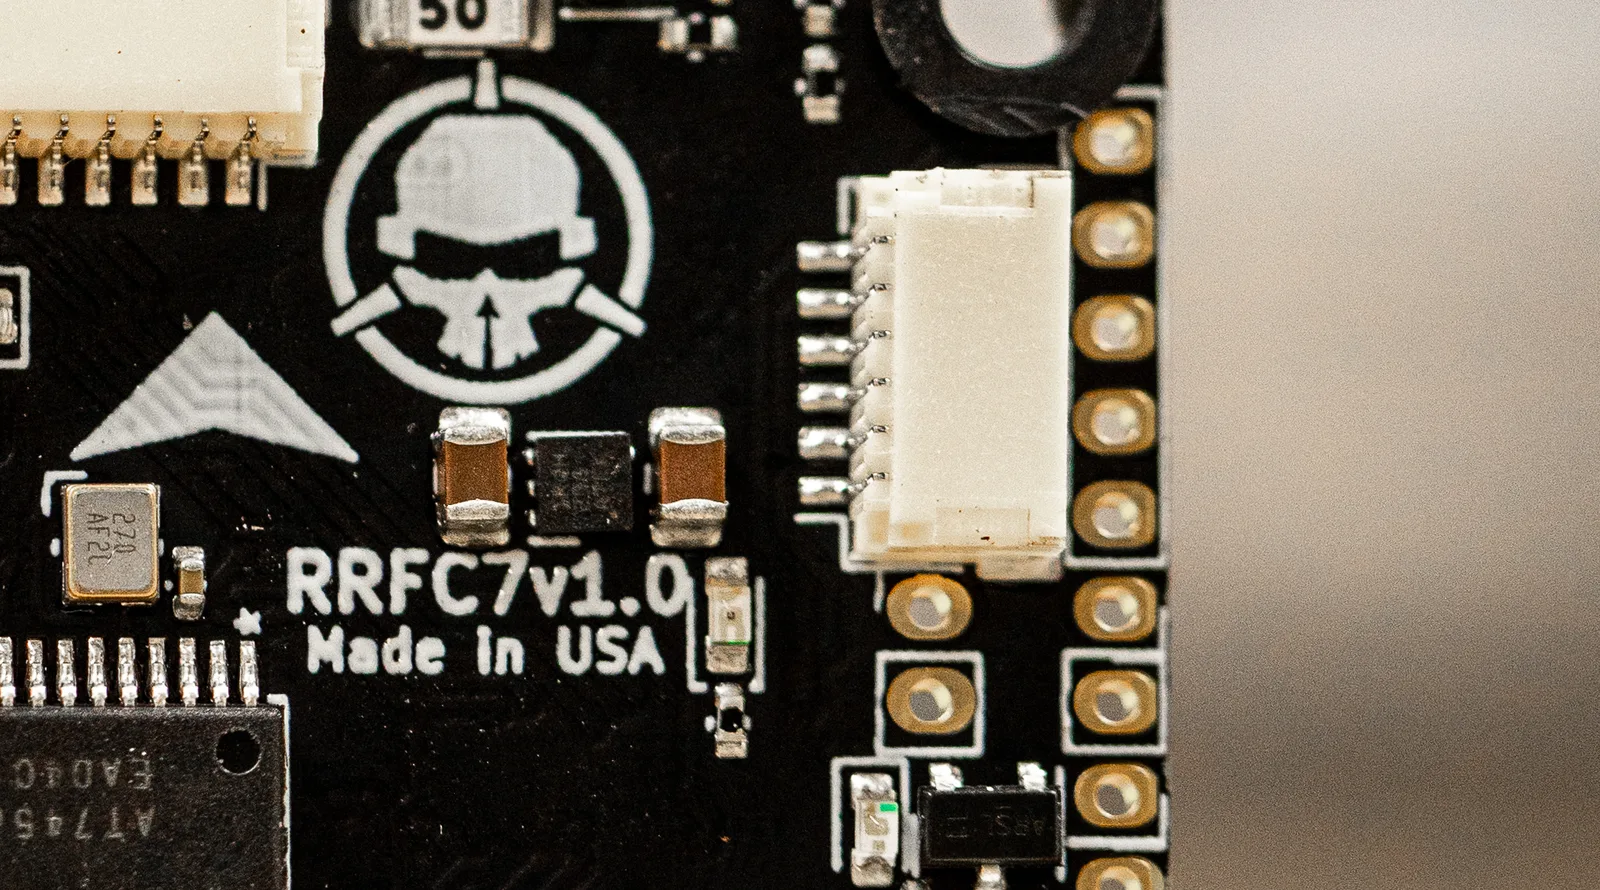
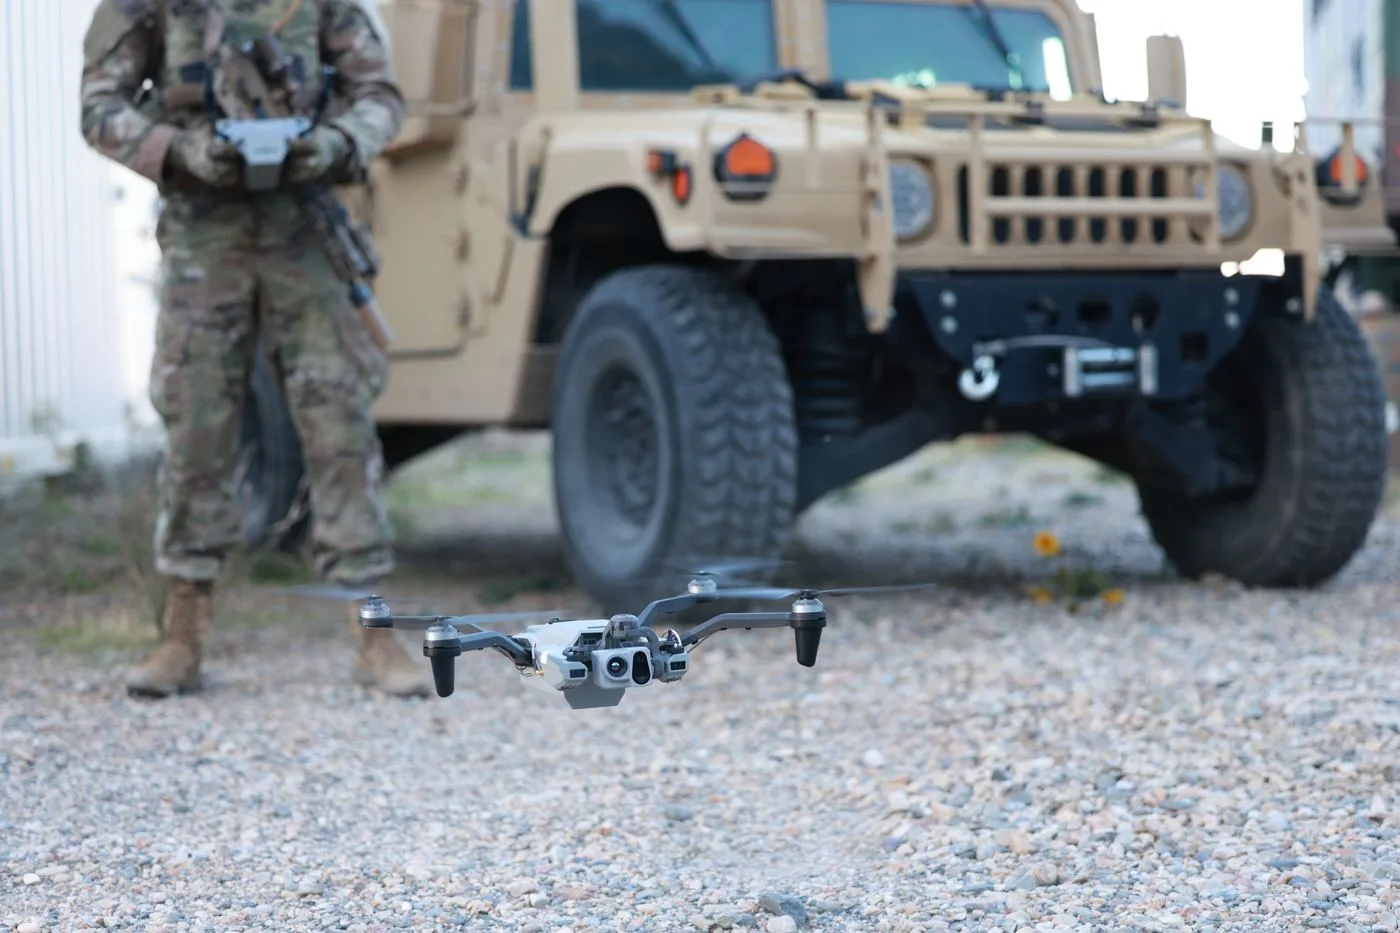
The company is based in Orlando, Florida, and its shares trade on NYSE American. Its pitch is a domestic supply chain: parts that meet US defence sourcing rules, so drone makers can avoid Chinese components. Its product range covers motors, flight controllers, electronic speed controllers, video systems, cameras, FPV headsets used to fly drones by live video, additive manufacturing and, since October, batteries and power systems.
It also runs two consumer brands for hobby pilots, Fat Shark and Rotor Riot. Most of the money now comes from enterprise customers, which made up about 90% of third-quarter revenue.
Demand has been lifted by Pentagon programmes to buy large numbers of small drones and counter-drone systems. On its November earnings call, management pointed to the Drone Dominance programme, whose second-phase orders were placed in October, with a third phase funded for early 2027.
Unusual Machines: share price, chart and news
The latest numbers
| Measure | Q3 2026 | Q3 2025 |
|---|---|---|
| Revenue | $13.9m | $2.1m |
| Gross margin | 35.4% | 39.4% |
| Operating loss | $8.4m | $5.0m |
| Net result | $25.0m loss | $1.6m profit |
| Adjusted EBITDA | $0.7m loss | not given |
Revenue for the first nine months was $38.7m, against $6.3m a year earlier. The third quarter was below the second quarter's $16.7m. The net loss was driven by an $18.4m unrealised loss on its equity stakes. Chief executive Allan Evans said in the shareholder letter: "I continue to believe that Unusual Machines can achieve positive adjusted EBITDA in 2027."
The market it is chasing
The company cites an estimate from research firm Fact.MR that the US market for drone components is worth $3bn to $5bn. On the November call, Evans pointed to about $4.5bn of counter-drone contracts awarded to ten companies, and said Unusual Machines hopes to supply many of the parts used in the Drone Dominance programme, which he put at potentially a couple of hundred million dollars through 2027, while stressing that requirements and awardees keep changing.
Capacity, not orders, is the current limit. Management said production is almost fully booked through the first quarter of 2027, and that its best-selling product accounts for about 19% of revenue. A planned automated motor line is expected to add about 100,000 motors a month once fully running. Commercial demand is a later opportunity: Evans expects it to pick up in late 2027 once the Federal Aviation Administration finalises its proposed Part 108 drone rule, which he expects within about six months.
Headcount has grown quickly, from 240 at the end of June to more than 340 in early November, including the Upgrade Energy team.
Cash, investments and share count
Balance sheet at 30 September 2026
- $162.0m cash, down from $229.6m three months earlier
- $98.4m short-term investments, plus a $5.0m note receivable
- 49.98m shares outstanding, up from 37.76m at the end of 2025
Working capital was $342.1m. Inventory and prepayments for inventory rose to $65.9m from $42.4m three months earlier, ahead of the fourth-quarter revenue target. The share count rose by about 32% in nine months, diluting existing holders, and the Upgrade Energy deal adds further shares after the quarter end.
Acquisitions and stakes in customers
Unusual Machines has used its cash to buy capacity and take positions across the drone industry:
- Upgrade Energy: completed on 19 October, this Torrance, California battery-pack maker cost up to $52m, according to DroneXL: about $25m in shares (1,792,012 shares at $13.95), $1m in cash and up to $26m more if revenue targets are met. It had revenue of $3.32m in the third quarter. DroneXL also questioned whether some Upgrade packs may use cells from a China-based supplier; Upgrade's chief executive said the company manufactures in the US and provides compliance documents where required, and DroneXL said it had no evidence that packs sold to defence customers contained those cells.
- Powerus: a $30m equity investment in June, followed by a $16.9m parts order from Powerus on 22 October.
- XTEND AI Robotics: an extra $20m in September, taking the total investment to $27.5m. XTEND is also a customer.
- XTI Aerospace: an investment, and Evans became its chairman in October.
These links help secure orders but create conflicts and concentration. About $2.0m of third-quarter revenue came from related parties.
Risks and what to watch
The company is small, loss-making and exposed to US defence budgets and programme timing. Customer concentration is high and, on management's own account, likely to rise through 2027. Its stakes in listed drone companies have already produced large paper losses and can swing further. Gross margins remain below the 40% target, scaling new factories carries execution and quality risk, and any shortfall in cash could lead to more share sales. A possible loan from the Pentagon's Office of Strategic Capital is under discussion but not agreed. The shares have been very volatile, falling about 45% between the August and November results.
What to watch
- Fourth quarter 2026: management's revenue target of $25m, repeated on the 5 November call
- Fourth quarter 2026: the new automated motor line coming online and about 100,000 square feet of extra space
- Early 2027: Drone Dominance phase three and domestic camera production
- 2027: whether the company reaches positive adjusted EBITDA, as Evans expects
Sources
- Unusual Machines via Newswire: Unusual Machines Third Quarter 2026 Shareholder Letter
- Webull: Unusual Machines Q3 2026 Earnings Call Transcript
- Unusual Machines via Newswire: Unusual Machines Completes Acquisition of Upgrade Energy, Expanding U.S. Drone Battery Manufacturing
- DroneXL: Unusual Machines, Upgrade Energy and the question of battery cells
- Unusual Machines via Access Newswire: Unusual Machines Receives $16.9 Million Purchase Order from Powerus for American-Made Drone Components
- Unusual Machines via Access Newswire: Unusual Machines Invests an Additional $20 Million in XTEND AI Robotics
- Earnings Whispers via Finviz: Unusual Machines misses on GAAP investment markdowns, but revenue beat and reaffirmed $25m Q4 target