BlackSky Technology runs a small fleet of high-resolution imaging satellites and sells fast, frequent pictures of specific places to defence and intelligence agencies. After its best quarter yet, the company is profitable on an adjusted EBITDA basis, but it carries debt, depends on government budgets and still has satellites to launch.
What BlackSky does
BlackSky is based in Herndon, Virginia, and listed on the New York Stock Exchange. Rather than mapping the whole planet, it focuses on revisiting important sites, such as ports, airbases and factories, many times a day. Customers order images through its Spectra software, which also runs AI tools that pick out vehicles, aircraft and ships.
Its newest Gen-3 satellites take pictures at 35 centimetres resolution, by day and night and in stereo. The fifth Gen-3 satellite launched in September and began earning revenue within 24 hours. The company earns money in three ways:
- Space-based intelligence and AI services: subscriptions and contracts for data and analytics, $32.7m of third-quarter revenue.
- Mission solutions: building Gen-3 satellites for foreign governments, $4.7m.
- Advanced technology programmes: government-funded development, mainly of AROS, a next-generation satellite due to launch in 2028, $5.4m.
The premium product is the Assured subscription, which gives a customer guaranteed priority on the satellites over its areas of interest.
BlackSky Technology: share price, chart and news
The latest numbers
Q3 2026, three months to 30 September
- $42.8m revenue, up 118% year on year
- $12.8m adjusted EBITDA, a 29.9% margin
- $355m backlog, about $45m due in the fourth quarter
Cost of sales fell to 21% of revenue from 35% a year earlier, because the extra subscription revenue used satellites that were already in orbit. Cash operating expenses were $21.4m. Net income of $18.5m was lifted by a $19.7m gain on derivatives; over nine months, BlackSky lost $32.0m. Operating cash flow turned positive in the quarter.
Over the first nine months, adjusted EBITDA was a $12.4m profit, against a $7.9m loss in the same period of 2025, and the net loss narrowed to $32.0m from $69.4m. Total operating expenses in the third quarter were $33.4m, up from $29.6m, a much slower rise than revenue. Management said large satellite deliveries in the fourth quarter will change the revenue mix, and its guidance implies flat to lower adjusted EBITDA than in the third quarter.
How the model works
BlackSky's strategy is to win a customer with a small trial, then convert it into a larger subscription. The company describes this as land and expand. Management said on the November call that the annual run rate of its high-margin services had passed $100m, and that it had secured the backlog needed for 50% growth in that part of the business in 2026.
The economics improve as each satellite fills up. Chief financial officer Henry Dubois said more than 90% of each additional dollar of services revenue now reaches the bottom line, because new subscriptions use satellites that are already paid for. The opposite also holds: if a satellite is lost or a launch slips, capacity and revenue are delayed.
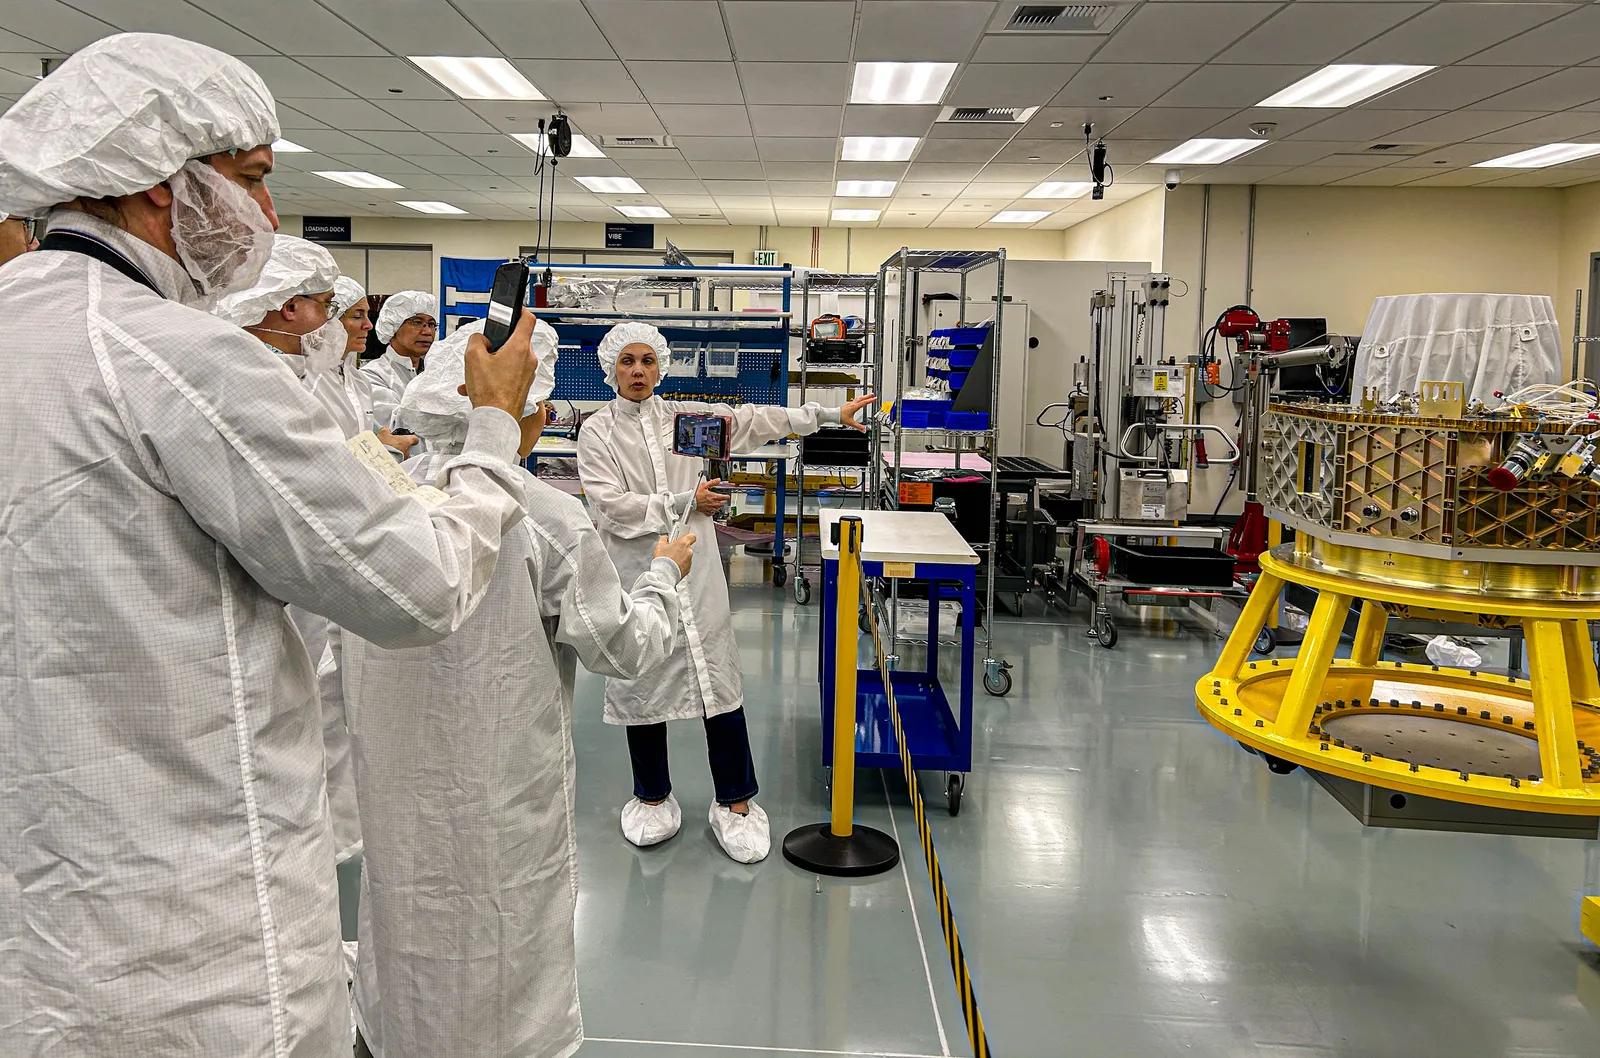
Selling satellites to governments is the second engine. BlackSky has more than 20 satellites in production, and its first Gen-3 sovereign satellite was ready to ship less than a year after the contract was signed. An analyst on the call noted that these deliveries carry lower margins than subscriptions.
Balance sheet and share count
| Item at 30 September 2026 | Amount |
|---|---|
| Cash, restricted cash and short-term investments | $231.1m |
| Long-term debt | $204.5m |
| Current portion of debt | $15.4m |
| Derivative liabilities | $19.5m |
| Shares outstanding | 41.1m |
Cash had fallen from about $244m three months earlier, according to Earnings Whispers. Capital spending reached $46.5m in the first nine months. The CFO said the company has enough liquidity to finish its baseline Gen-3 constellation in 2027. The share count rose from 35.9m at the end of 2025, an increase of about 14% that dilutes existing holders.
Growth beyond the US
Several recent contracts have come from outside the US government. In September it was named exclusive supplier of high-resolution optical satellites for a $1bn initiative led by Marlan Space, Loft Orbital and Mistral AI, which plans an initial 50-satellite constellation for users in France, Europe and the UAE. BlackSky has only an initial development contract so far, and its value has not been disclosed.
On 10 November it signed a one-year, seven-figure Assured contract with a new international defence ministry, which moved from a first meeting to an Assured subscription in under nine months. Chief executive Brian O'Toole said: "In a dynamic world, the value of intelligence is measured in minutes." BlackSky also renewed a seven-figure space-monitoring contract with HEO and joined a SkyFi pilot that feeds facility-monitoring insights to Robinhood users.
Risks and what to watch
The main risks are concentration and execution. Much of BlackSky's revenue comes from defence and intelligence agencies whose budgets can change. The third quarter included a short, non-recurring US government pilot, and backlog was broadly flat. One Gen-3 launch has slipped into 2027, and further launch or manufacturing delays would push revenue back. The company has more than $200m of debt, and future capital needs could mean more share issuance. The shares are volatile and have swung widely over the past year.
What to watch
- 2 December 2026: BlackSky's investor day, listed in the company's announcements
- Fourth quarter: two more Gen-3 launches and several sovereign satellite deliveries
- 2026 guidance: revenue of $140m to $150m and adjusted EBITDA of $18m to $24m
- Coming months: the scope and value of the French and UAE consortium programme
Sources
- BlackSky Technology (SEC Form 8-K): BlackSky Reports Third Quarter 2026 Results
- BlackSky Technology: Q3 2026 earnings call transcript
- BlackSky Technology via Business Wire: BlackSky Named Exclusive Provider of Very High-Resolution Electro-Optical Constellation for New International Initiative
- BlackSky Technology via Business Wire: BlackSky Wins Seven-Figure Contract with New Major International Ministry of Defense
- Finviz: BKSY quote page and news list
- Earnings Whispers via Finviz: BlackSky's record Gen-3 quarter delivers margin breakout and higher guidance