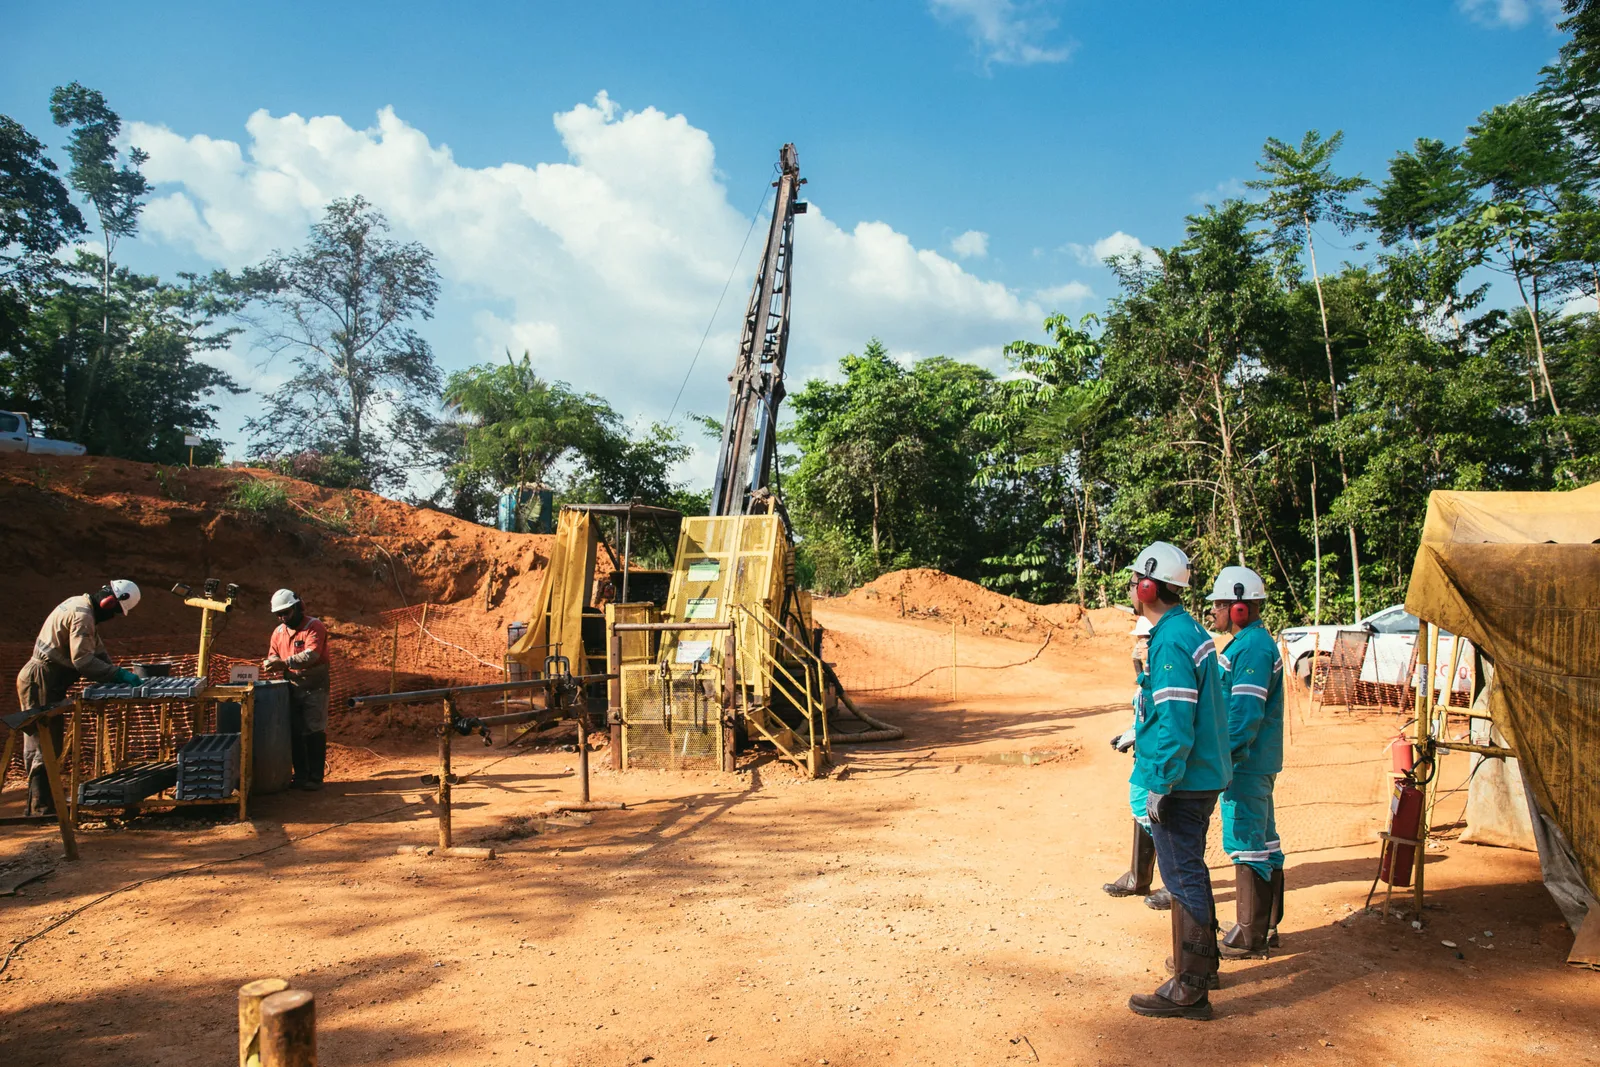
Ero Copper is a copper and gold miner whose operations are all in Brazil: two copper operations, Caraíba and Tucumã, a gold mine at Xavantina and an exploration project at Furnas. This profile covers its assets, the latest reported numbers, its debt and the risks behind them.
What Ero does and where
Ero describes itself as a Brazil-focused copper and gold producer. It has offices in Vancouver and São Paulo, and its shares trade on the Toronto Stock Exchange and the New York Stock Exchange under the symbol ERO. It reports in US dollars, while most of its costs are in Brazilian reais, which makes the exchange rate an important driver of its margins.
In the third quarter of 2026 the weighted average number of basic shares was 104,351,583, and 105,977,099 on a diluted basis.
Ero Copper: share price, chart and news
The operations
Caraíba (copper, Bahia). Ero owns 99.6% of the Caraíba operations in the Curaçá Valley of north-eastern Bahia, about 385 kilometres north-north-west of Salvador. They include the Pilar and Vermelhos underground mines, the Surubim open pit and a mill of about 4.2 million tonnes a year. The company reports proven and probable reserves of 73.1 million tonnes at 0.90% copper, holding 654,000 tonnes of contained copper. It is building a new, larger shaft at Pilar to reach the deeper high-grade zone, though it has not given a completion date publicly on its operations page or in its latest results.
Measured and indicated resources at Caraíba total 161.1 million tonnes at 0.91% copper. In the third quarter of 2026 the operations produced 9,387 tonnes of copper at a C1 cash cost of $2.89 per pound, from 1,161,102 tonnes milled at 0.90% copper.
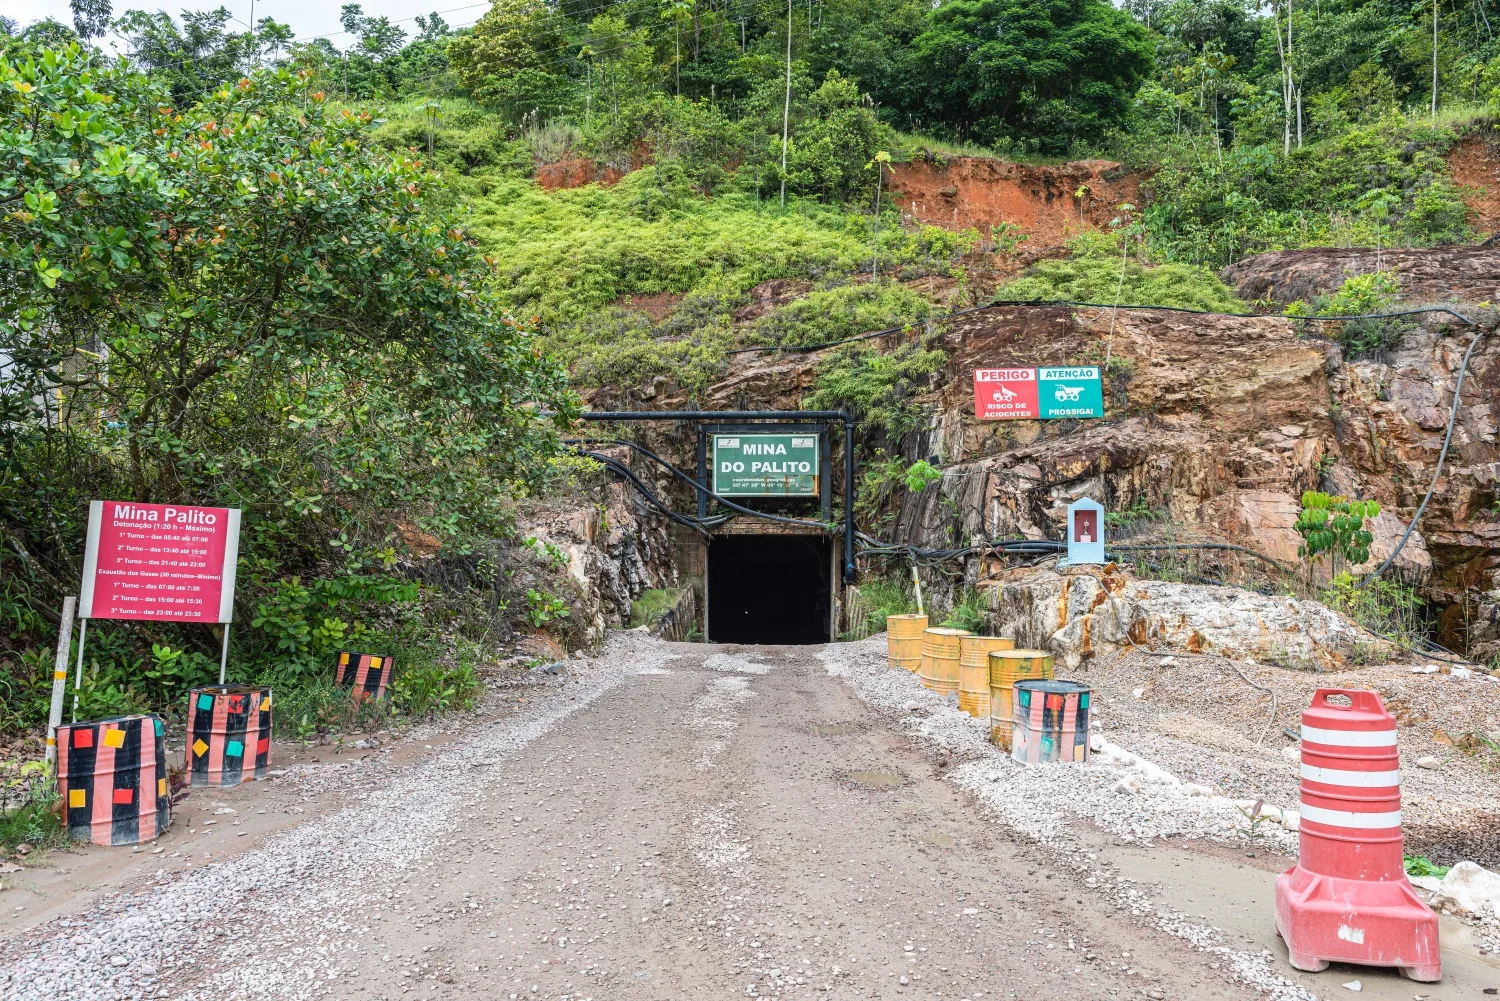
Tucumã (copper, Pará). This open-pit mine in the Carajás mineral province, also 99.6% owned, produced its first saleable concentrate in July 2024 and reached commercial production on 1 July 2025. Its design capacity is 4.0 million tonnes of ore a year. Reserves are 43.1 million tonnes at 0.83% copper, with 356,600 tonnes of contained copper. Ero's website gives 2026 guidance of 32,500 to 37,500 tonnes of copper from Tucumã, against 28,272 tonnes in 2025. In the third quarter of 2026 it produced 8,958 tonnes at $2.12 per pound, processing 814,137 tonnes at 1.30% copper with 85.0% recovery.
Xavantina (gold, Mato Grosso). Ero owns 97.6% of this underground gold mine, which works the Santo Antônio and Matinha veins. Reserves are 2.1 million tonnes at 6.92 grams per tonne, or 466,200 ounces. Mined output was 37,291 ounces in 2025. Royal Gold holds a stream on the mine: it receives 25% of the gold produced until 160,000 ounces have been delivered, then 10%, and pays a fraction of the spot price for each ounce. In 2026 the mine has been supplemented by gold recovered from historic concentrate stockpiles.
Furnas (copper-gold). Ero is earning a 60% interest from Vale Base Metals. It completed 45,000 metres of phase 3 drilling in the third quarter of 2026, which it says meets the exploration part of the earn-in, and expects a pre-feasibility study in 2027.
Latest reported numbers
Ero published record third-quarter results on 2 November 2026.
Q3 2026
- 18,345 t copper produced, up 6% on the quarter
- $348.0m revenue
- $353.5m net debt at 30 September
| Measure | Q3 2026 |
|---|---|
| Consolidated copper C1 cash cost | $2.51/lb |
| Gold produced (incl. stockpiles) | 25,258 oz |
| Net income attributable | $116.2m ($1.10 per diluted share) |
| Adjusted EBITDA | $200.6m |
| Cash flow from operations | $191.2m |
| Cash and equivalents | $114.1m |
| Available liquidity | $264.1m |
| Net debt to trailing adjusted EBITDA | 0.5x |
Net debt fell by about $99 million in the quarter, and leverage dropped from 1.2 times at the end of 2025. Trailing twelve-month adjusted EBITDA was $656.6 million. Capital spending was $222.3 million over nine months, against full-year guidance of $285 million to $330 million.
For 2026, Ero guides to 67,500 to 77,500 tonnes of copper at a consolidated C1 cost of $2.25 to $2.45 per pound, raised from $2.15 to $2.35. Total gold guidance is 75,000 to 80,000 ounces, of which 30,000 to 35,000 ounces are expected from mining and about 45,000 ounces from the historic stockpiles.
Main risks
Risks investors should weigh
- Rising costs. Copper and gold cost guidance went up in November, which the company linked to a stronger real, inflation tied to the US-Iran conflict and delayed access to higher-grade ore at Surubim.
- Currency. Costs are largely in reais while revenue is in dollars. Hedges produced $30.3 million of realised gains in the first nine months of 2026, but hedges expire.
- Gold quality. Mined gold guidance was cut to 30,000 to 35,000 ounces at an all-in sustaining cost of $3,300 to $3,600 an ounce. The stockpile ounces that lift total output are finite.
- Debt. Leverage is lower, but net debt was still $353.5 million at the end of September.
- Single country. All assets are in Brazil, so permits, tax and politics there affect the whole company.
Tucumã is also still being optimised: modular tailings filters are due to be installed and commissioned in the fourth quarter of 2026, and the company says that work is not reflected in its 2026 guidance. Copper price moves feed straight into revenue.
What to watch next
| When | What |
|---|---|
| Q4 2026 | Installation and commissioning of modular tailings filters at Tucumã |
| Q4 2026 | The quarter Ero expects to be its strongest for copper in 2026 |
| Year-end 2026 | Completion of Tucumã's tailings filtration expansion |
| Early 2027 | Full-year 2026 results against copper guidance of 67,500 to 77,500 tonnes |
| 2027 | Furnas pre-feasibility study |
With Tucumã in commercial production, Ero is directing most of its spare cash to repaying debt. The test for 2027 is whether Tucumã runs steadily at design rates and whether unit costs fall back as the company expects, rather than continuing to rise with the Brazilian real.