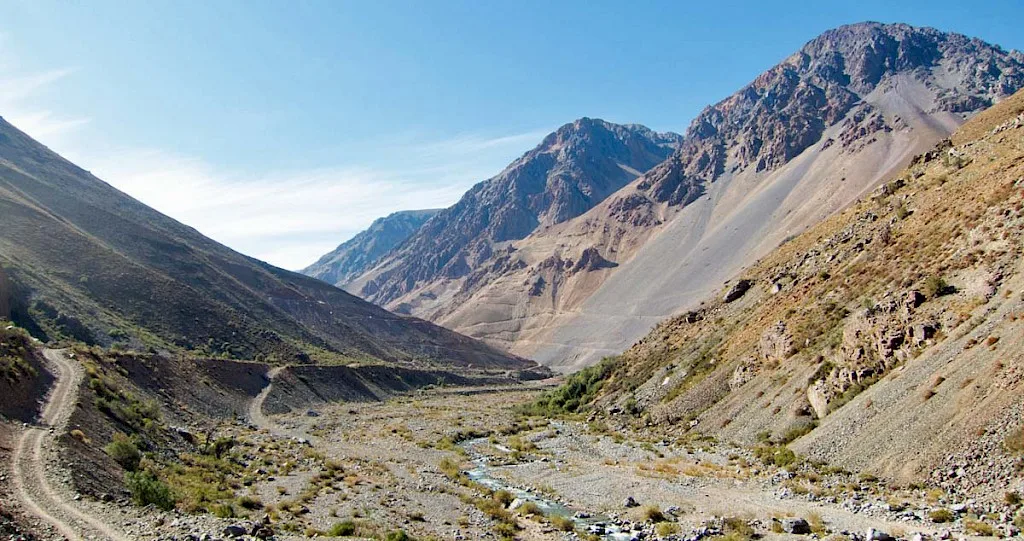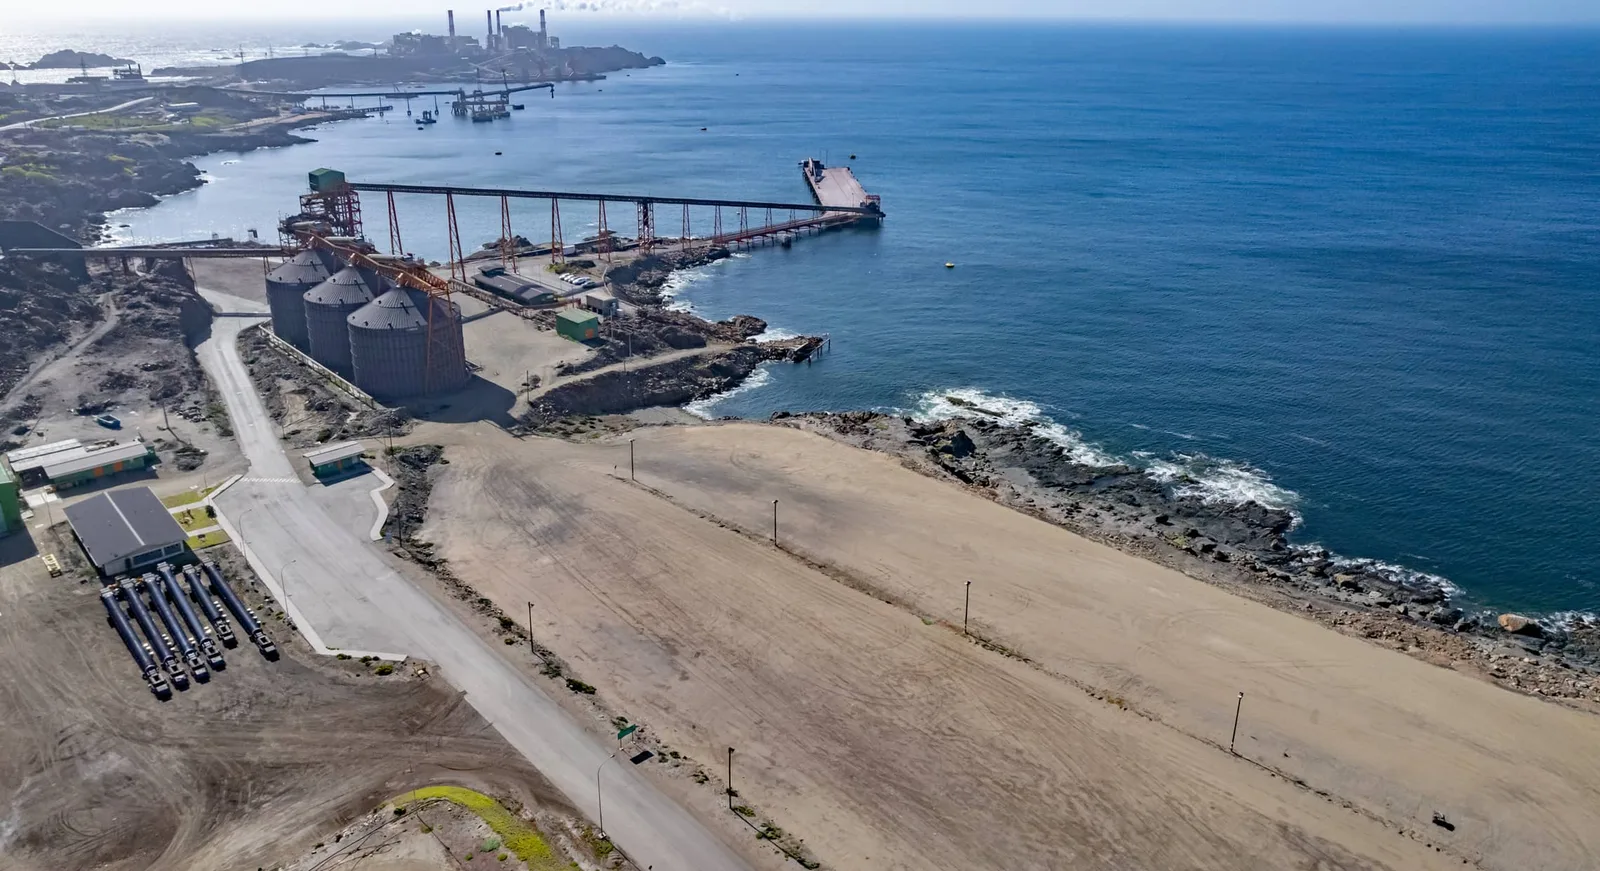
Hot Chili is a Perth-based copper developer whose business is almost entirely in Chile: the Costa Fuego copper-gold project in the low coastal range of the Atacama region, a water company meant to supply it, and a new discovery at La Verde that is reshaping its plans. This profile sets out what it owns, its latest reported numbers and the main risks.
What Hot Chili does and where
The company's shares trade on the ASX and the TSX Venture Exchange under HCH and over the counter in the US as HHLKF. It has no production and no revenue, so its value rests on the size and economics of its copper deposits and on its ability to fund a mine.
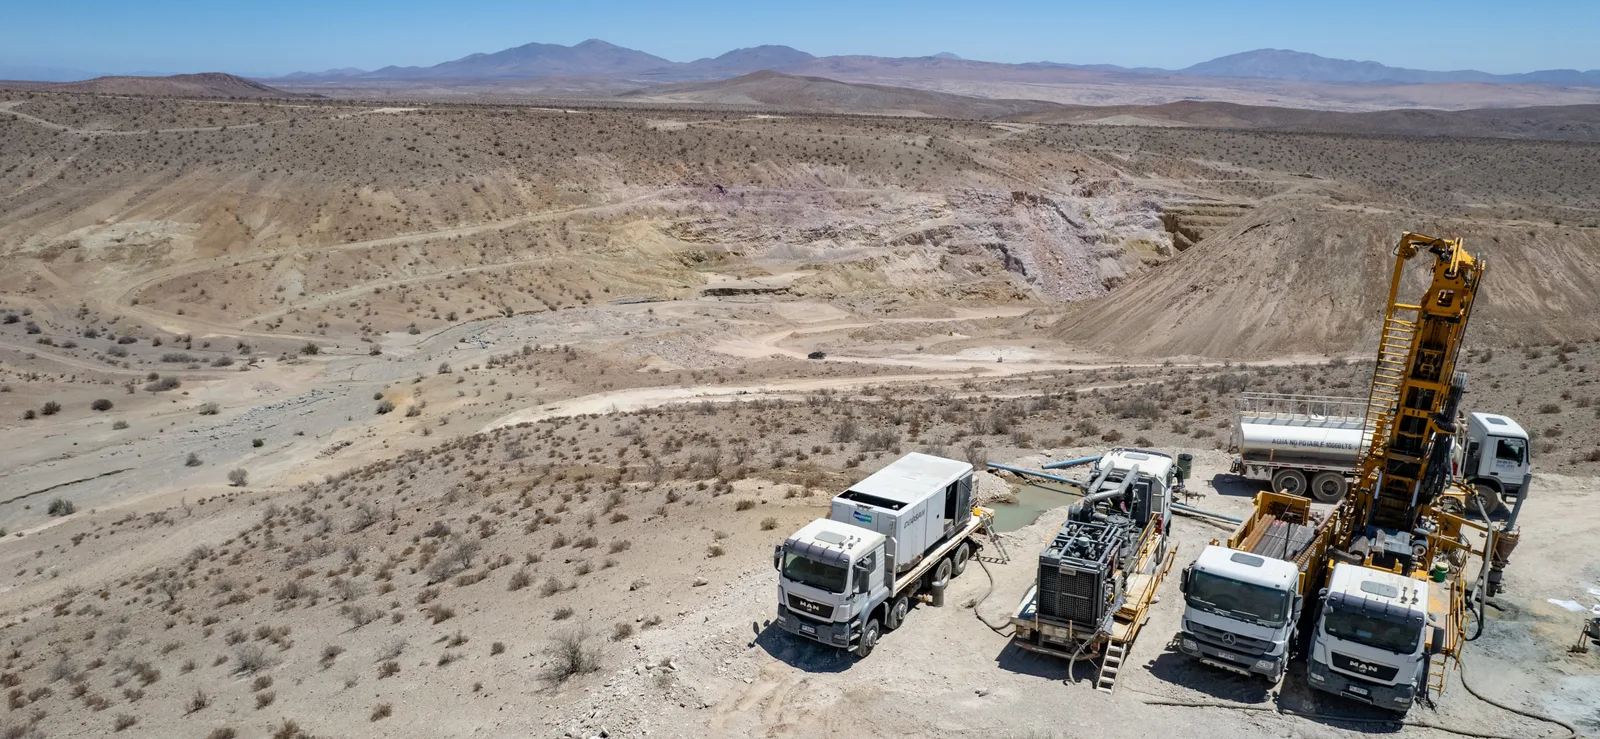
Costa Fuego groups several deposits around a planned central processing hub at Productora. They include Cortadera, where the company is finalising a large open-pit option for the later years of the mine plan in place of the earlier open-pit and block-cave design. During the September quarter a Hot Chili subsidiary also exercised its purchase option over the San Antonio ground and took ownership of 30 mining concessions; the payment was US$2 million.
The newest piece is La Verde, a copper-gold porphyry about 30 km south of the hub. In October Hot Chili said step-out drilling had found a second porphyry centre there, La Verde South.
Hot Chili: share price, chart and news
Key assets
Costa Fuego. The 2025 pre-feasibility study (PFS) rests on measured and indicated resources of 798 million tonnes at 0.45% copper equivalent, plus 203 million tonnes of inferred resources at 0.31%. Probable reserves stand at 502 million tonnes. The study projected about 116,000 tonnes of copper equivalent a year over the first 14 years, a post-tax net present value of US$1.2 billion and an internal rate of return of 19%, using a long-term copper price of US$4.30 a pound. The company has said each 10 cents a pound above that assumption adds roughly US$100 million to the post-tax value.
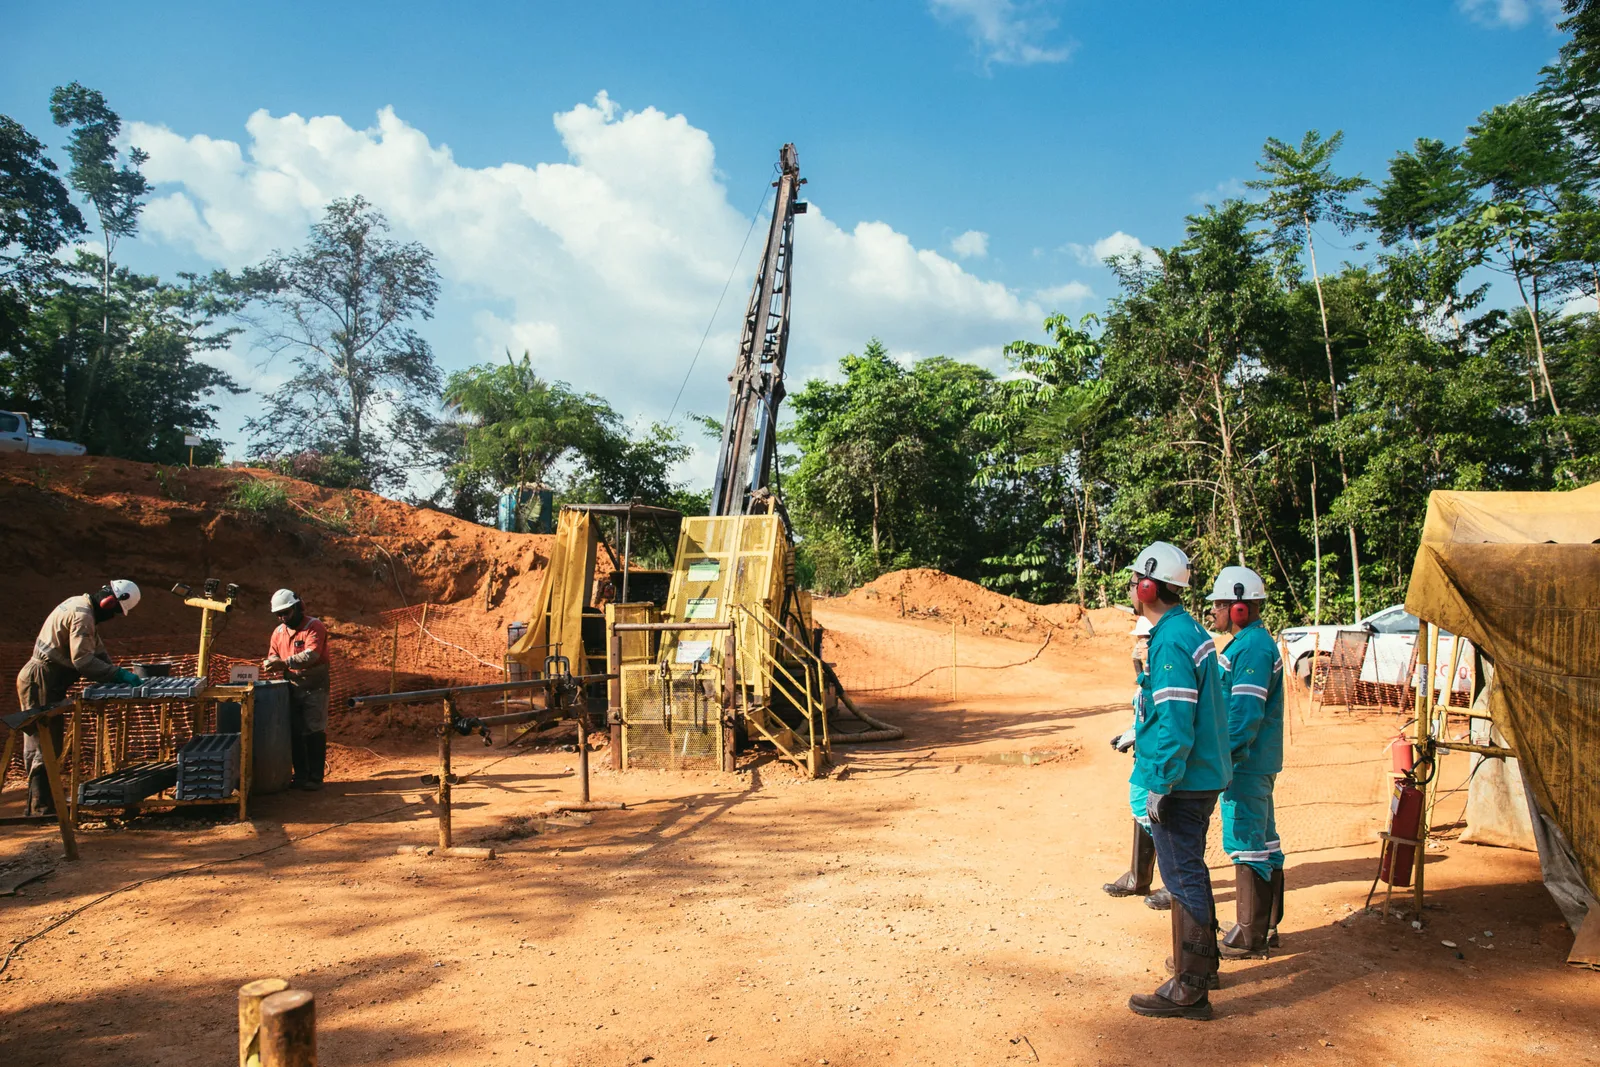
La Verde. Drilling reached 50,000 m when the 40,000 m second phase finished. Across two porphyry centres, the mineralised footprint now measures about 1,400 m by 780 m and extends 800 m deep. Standout results reported in the September quarter include 398 m at 0.45% copper equivalent from surface in hole DKP063, with 62 m at 0.91% from 20 m, and 472 m at 0.41% from 49 m in DKD060. There is no La Verde resource yet.
Huasco Water. Hot Chili owns 80% of this water business, which holds a maritime concession for seawater access in the Huasco valley. The first plan is to supply 500 litres a second to Costa Fuego, with a possible expansion to 1,300 and then 2,300 litres a second through a second concession that is still being processed.
Latest numbers
The quarterly report for the three months to 30 September 2026 was released on 30 October.
At 30 September 2026
- A$29.3m cash, with no debt
- A$10.1m spent on exploration and studies in the quarter
- 202.9m ordinary shares on issue
The quarter's cash also reflected the closing of an amended agreement with OR Royalties, which brought in A$20.4 million after costs for an extra US$15 million royalty. OR's total consideration is now US$30 million and its royalty covers La Verde. Staff costs were A$1.3 million and administration A$1.5 million. With the drilling programme finished, Hot Chili expects exploration spending to fall materially in the coming quarters.
Besides the shares, there are 1.21 million options exercisable at A$2.145 until August 2028, 4.73 million performance rights and 420,302 service rights.
| Costa Fuego PFS (2025) | Figure |
|---|---|
| Measured and indicated resources | 798 Mt at 0.45% CuEq |
| Probable reserves | 502 Mt |
| Output, first 14 years | about 116,000 t CuEq a year |
| Post-tax NPV and IRR | US$1.2bn and 19% |
| Funding needed to build | about US$1.27bn |
Main risks
Funding and dilution. The company's own cautionary statement puts funding needs at about US$1.27 billion, including working capital and financing charges, and says money may only be available on terms that dilute shareholders. A strategic partnering process, advised by BMO Capital Markets, has drawn non-binding and conditional proposals, but Hot Chili says a deal is not certain. At the 25 November annual meeting shareholders will vote on ratifying earlier placement shares and on a special resolution for an additional 10% placement capacity.
Study risk. The PFS is preliminary and predates La Verde. A revised study is being prepared, and its numbers could differ, up or down.
Permits and communities. Two environmental impact assessments, one for Huasco Water and one for Costa Fuego, are being prepared. Heavy rain in July and August delayed fieldwork, though the company says the second-quarter 2027 filing date still holds. Consultation includes Indigenous organisations in the Huasco valley. The company launched a community grant scheme, the Produce Futuro Fund, in September; it drew more than 300 applications, and 55 grants are due to be awarded this quarter. One lost-time injury, a fractured finger during diamond drilling, was recorded in the September quarter.
Royalty burden. Selling royalties has kept dilution down, but it reduces the share of future revenue left for shareholders. The amended OR agreement includes an updated buy-back provision that applies on a change of control.
Exploration risk. Visual logs at La Verde South still need assays, and drill results do not guarantee a resource.
What to watch next
Dates and milestones
- 25 November 2026: annual general meeting in Applecross, Western Australia, at 9.30am local time
- December 2026: assays expected for diamond hole DKD100 at La Verde South
- Maiden La Verde resource estimate and revised Costa Fuego PFS: the company says both remain on track
- January 2027 (expected): next quarterly report, for the three months to 31 December
- Early 2027: drill rigs return to focus on La Verde South
- Second quarter of 2027: planned submission of both environmental assessments
Earlier company material also set out a final investment decision in 2029 and first production in 2031. Those dates depend on permits and on financing that has not yet been arranged.
Sources
- Hot Chili: Quarterly report for the period ending 30 September 2026 (30 October 2026)
- Hot Chili: Notice of annual general meeting (23 October 2026)
- Hot Chili news: Hot Chili tightens metrics on South American copper growth engine (September 2026)
- Hot Chili news: Hey neighbour! Hot Chili discovers second porphyry next door to La Verde (October 2026)