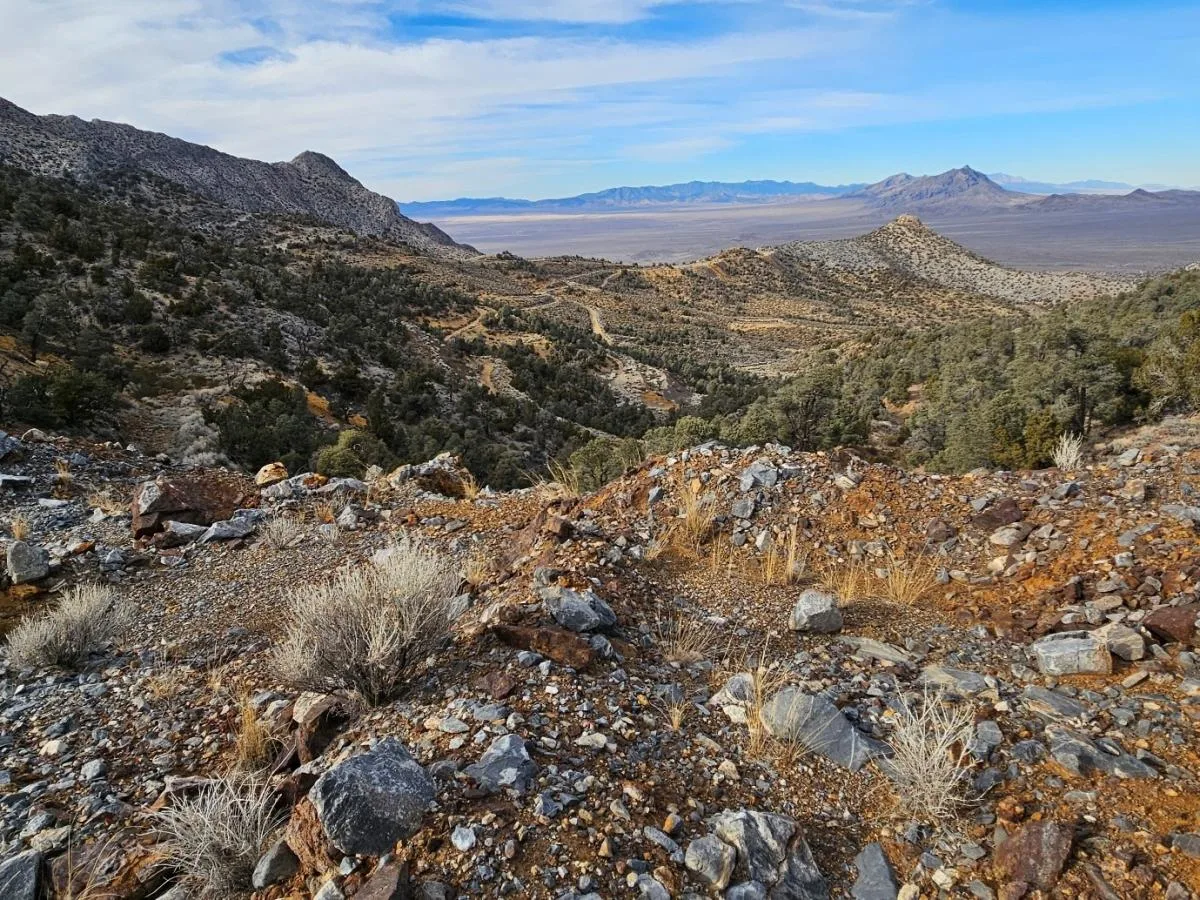
Guardian Metal Resources wants to restart mined tungsten production in the United States, a country that has had none for more than a decade. It has a finished pre-feasibility study for one Nevada project, drilling under way at a second, and US$52.5m in the bank at the end of June. It does not yet have the permits or the roughly US$290m it needs to build a mine.
What Guardian Does
Guardian is a UK-incorporated company whose business is entirely in Nevada. Its shares trade on London's AIM market as GMET, on the NYSE American as GMTL since 20 March 2026, and on the US OTCQB as GMTLF.
It is focused on tungsten, a very hard, heavy metal used in armour-piercing munitions, cutting tools, electronics and industrial alloys. China dominates supply and has restricted tungsten exports since February 2025, which has pushed Western governments to look for domestic sources. In July 2025 the US Department of War invested US$6.2m in Guardian's American subsidiary under the Defense Production Act to pay for the Pilot Mountain study.
Guardian has two main projects, Pilot Mountain and Tempiute, plus smaller tungsten claims (Pilot North, Cinch and White Elephant). On 11 November it said it plans to move its gold, silver and copper projects into a separate AIM-listed company by the second quarter of 2027, keeping a stake.
Guardian Metal Resources: share price, chart and news
Pilot Mountain: The Flagship
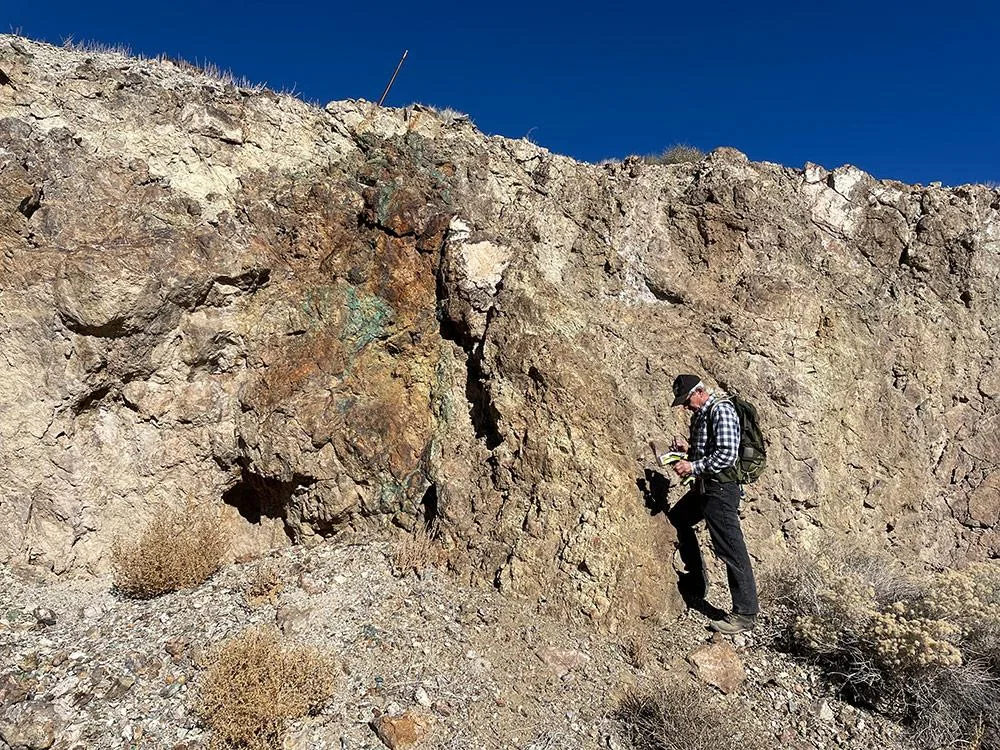
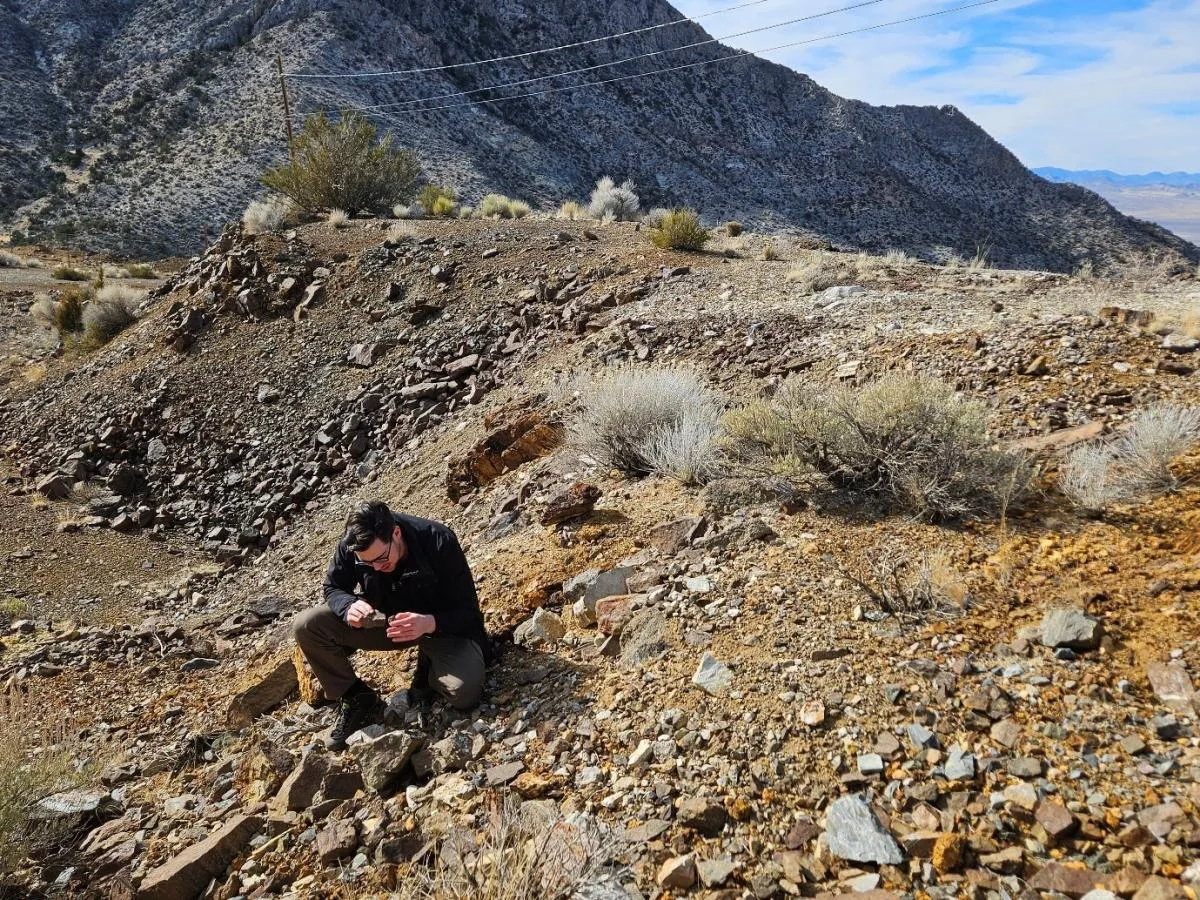
Pilot Mountain is wholly owned and planned as a conventional open-pit mine with a mill on site. The June 2026 pre-feasibility study (PFS) converted most of the indicated resource into probable reserves of 11.8 million tonnes at 0.171% tungsten trioxide (WO3), containing 20,275 tonnes of WO3 plus silver. Those reserves come from only two zones, Desert Scheelite and Garnet, about 2 kilometres apart.
| PFS item | Figure |
|---|---|
| Initial capital cost | US$288.7m, including US$39.1m contingency |
| Mill feed | 1.4 million tonnes a year |
| Output | about 2,000 tonnes of WO3 in concentrate a year |
| Initial mine life | 8 years, 15,916 tonnes of WO3 in total |
| After-tax NPV at 8% | US$660.3m at the base-case price |
| After-tax IRR | 59.6% at the base-case price |
| Base-case price | US$197,300 a tonne of WO3 |
The base-case price is about 35% below the 12 June 2026 market price of ammonium paratungstate, a common benchmark, of US$304,000 a tonne. At that higher price the study shows an after-tax NPV of US$1.366bn. The gap shows how much the economics depend on tungsten staying expensive.
Drilling since the study has found more mineralisation outside the planned pits. At the Tremor Zone, a blind discovery made while drilling near the planned tailings site, hole PM26-088 returned 64.15 metres at 0.20% WO3. The first holes at Good Hope included 12.95 metres at 0.79% WO3 near surface. The Tremor results forced a move of the planned tailings facility, which Guardian says should not materially change costs or timing.
Tempiute: A Former Producer
Tempiute was one of the largest US tungsten mines when it was run by Union Carbide, until it closed in the 1980s. Guardian holds the project under an option agreement that can give it up to 100% ownership. It has staked more ground there and in June paid US$1.3m for Lincoln Estates Group, which owns 841 acres of land and 2,540 acre-feet a year of water rights less than 10 miles from Tempiute.
A 41-hole regional drilling programme found tungsten-bearing skarn in several areas beyond the old workings. A second programme of about 46 holes is aimed at a first mineral resource estimate around the historical South Thumb and Schofield zones. In September Guardian reported 92.0 metres at 0.34% WO3 in hole TP26-046, with assays from 24 more holes then pending, and said it would rehabilitate old underground workings from October so that rigs can drill from underground. It is also studying the legacy tailings and stockpiles left at surface as a possible early source of feed.
The Numbers
Year to 30 June 2026
- US$52.5m cash at 30 June, up from US$1.9m a year earlier
- US$10.0m loss for the year, against US$2.7m in 2025
- US$89.3m raised in equity during the year
Guardian has no revenue. In the year to June it used US$6.0m in operations and spent US$26.5m on its mining assets. Most of the money raised came from the NYSE American listing, which brought in about US$68.3m before costs. The directors say the definitive feasibility study at Pilot Mountain and a maiden resource at Tempiute, both planned for the period to June 2027, are fully funded.
After an option exercise admitted in early November, Guardian had 199,597,008 ordinary shares in issue. In October it appointed David Hendriks, most recently chief operating officer of Centerra Gold, as its own COO, and named Ron Espell, who had already worked on its permitting, as vice-president for environment and permitting.
Main risks
- Funding: the mine needs about US$288.7m of initial capital, more than five times the June cash balance, so more equity, debt or partner money will be needed
- Dilution: further share sales, option and warrant exercises would reduce existing holdings
- Permits: Pilot Mountain still needs federal approval of its mine plan under the National Environmental Policy Act
- Price: the economics rely on high tungsten prices, which depend partly on Chinese export policy
- Study risk: a PFS is less precise than a definitive study, and Tempiute has no mineral resource yet and is held under an option
- Corporate: the spin-out is non-binding and could change or not happen
What to Watch
| When | What |
|---|---|
| Near term | Filing of the Pilot Mountain Mine Plan of Operations with the Bureau of Land Management |
| Coming months | Remaining Tempiute phase two assays and underground drilling |
| By June 2027 | Pilot Mountain definitive feasibility study and a first Tempiute resource, per the funding plan |
| Mid-2027 | Federal environmental review, which the PFS timeline assumes |
| By Q2 2027 | Targeted AIM listing of the gold, silver and copper spin-out |
| Q4 2028 | Targeted first production at Pilot Mountain |
Guardian has said it might decide to build Pilot Mountain on the strength of the PFS without a full feasibility study, but no such decision has been made. For investors, the next two years are about permits and money: whether Guardian can secure both on terms that leave existing shareholders with a meaningful share of a future mine.
Sources
- Guardian Metal Resources: Financial Results for the Year Ended 30 June 2026
- Guardian Metal Resources: Pilot Mountain Pre-Feasibility Study Results
- Guardian Metal Resources: Acquisition of Lincoln Estates & Water Rights
- Guardian Metal Resources: Drilling Results Support Potential Resource Growth
- Guardian Metal Resources: Positive Tempiute Tungsten Drilling Results
- Guardian Metal Resources: Strengthening of Senior Management Team
- Guardian Metal Resources: Option Exercise
- Guardian Metal Resources: Proposed Spin-Out of Non-Tungsten Projects