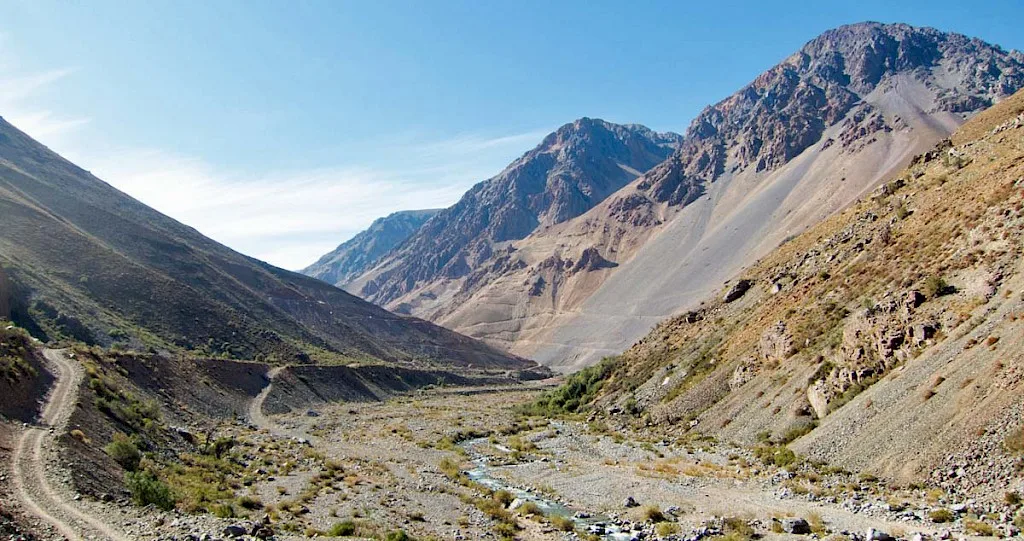
Los Andes Copper is a Vancouver-based company with one main asset: the Vizcachitas copper-molybdenum-silver project in central Chile, which it owns outright. A 2023 pre-feasibility study describes a large open-pit mine, but the company has no revenue, an interim chief executive and court cases still running. This profile sets out the project, the latest numbers and the main risks.
What Los Andes does and where
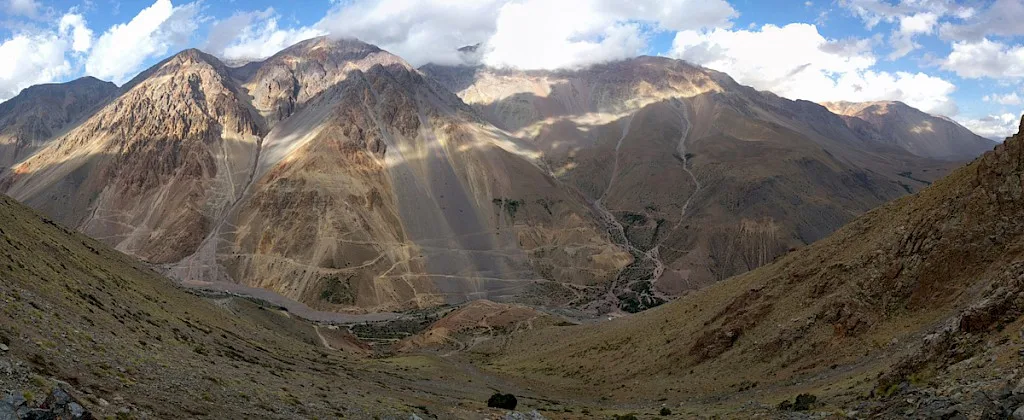
The shares are listed on the TSX Venture Exchange under LA and trade in the US over the counter as LSANF. Vizcachitas sits in the Andes in San Felipe province, Valparaiso region, about 120 km north of Santiago and 46 km northeast of the town of Putaendo, at about 1,950 m above sea level. It lies in the same mineral belt as large porphyry mines such as Los Pelambres and Rio Blanco.
At 30 June 2026 the company held 52 exploitation concessions over 10,771 hectares and 174 exploration claims covering 47,440 hectares. It also owns non-consumptive water rights on the Rocin river with studies for a 28 to 30 MW run-of-river hydro plant.
In January 2026 chief executive Santiago Montt resigned after being appointed Minister of Mines in the incoming government of President José Antonio Kast. Chief geologist Antony Amberg became interim chief executive, and the board has been searching for a permanent replacement.
Los Andes Copper: share price, chart and news
The Vizcachitas project
The pre-feasibility study (PFS), announced in February 2023, plans a conventional open pit feeding a 136,000-tonne-a-day concentrator over a 26-year life. It would produce a copper concentrate carrying silver and a separate molybdenum concentrate. Copper would provide 88% of net revenue and molybdenum 10%.
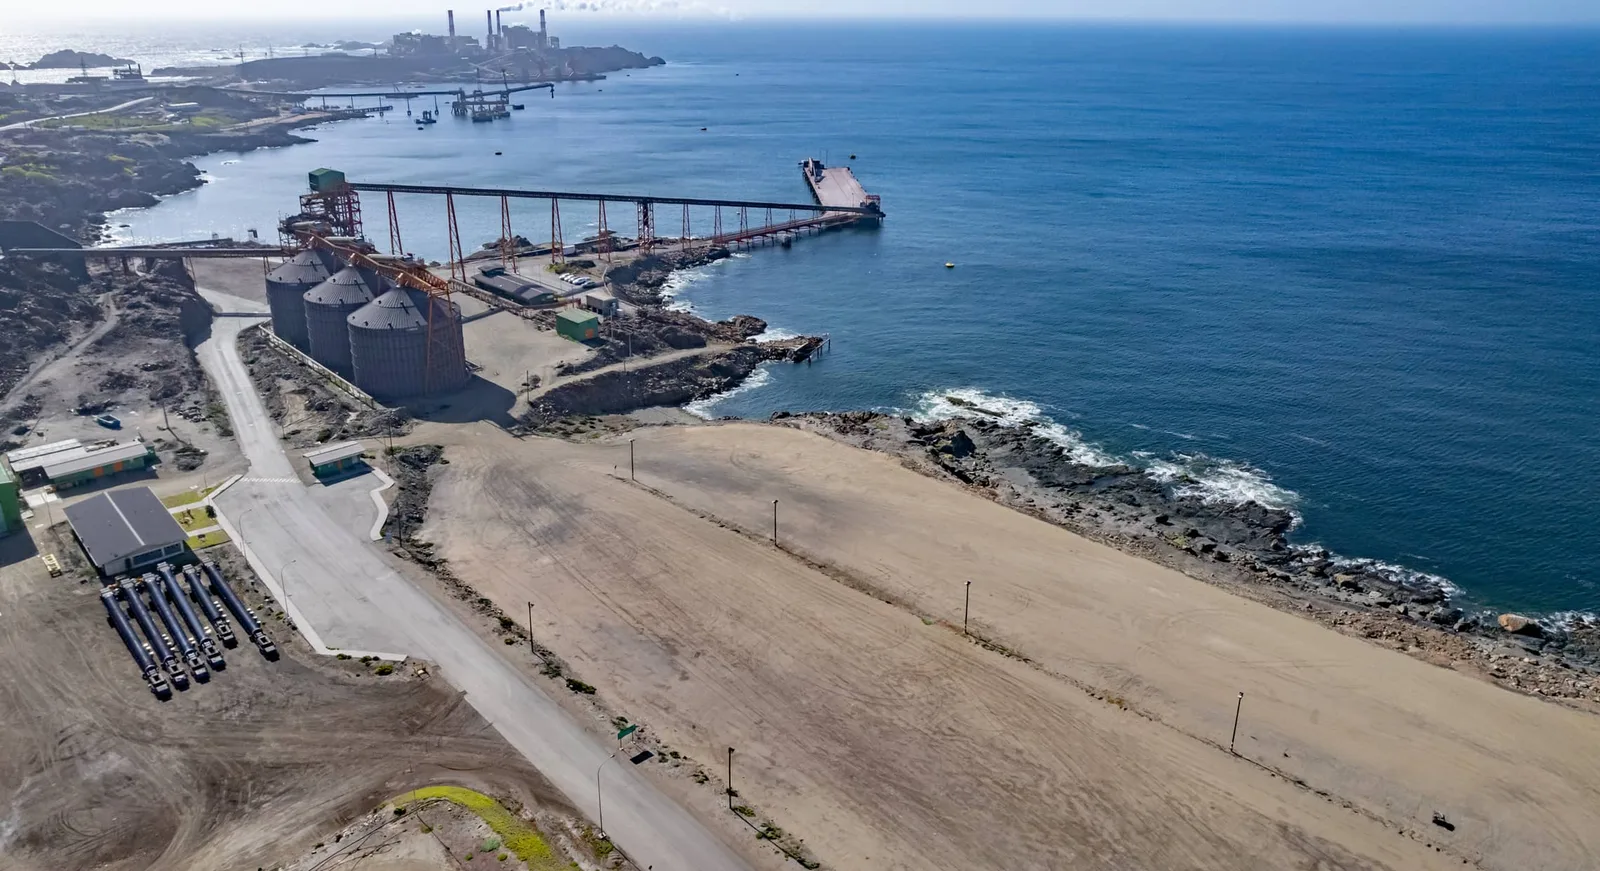
The design uses desalinated seawater from a third-party consortium, with which the company has signed a letter of intent, and filtered, dry-stacked tailings. The company says this roughly halves water use compared with conventional thickened tailings. Power would come through a 60 km line to the national grid, and concentrate would travel 145 km by truck to the port of Ventanas.
Crushing would use high-pressure grinding rolls, which the company says cut power use by about 25% compared with the mill design in its 2019 preliminary economic assessment. Beyond the initial US$2.44 billion, the study adds about US$1.5 billion of deferred and sustaining capital over the mine's life. All-in sustaining costs are put at US$2.13 a pound for the first eight years and US$2.35 over the life of the mine.
| Vizcachitas PFS (2023) | Figure |
|---|---|
| Proven and probable reserves | 1.22bn t at 0.41% copper equivalent |
| Measured and indicated resources | 1,541 Mt at 0.436% copper equivalent |
| Inferred resources | 1,823 Mt at 0.384% copper equivalent |
| Copper output | 183,017 t a year for 8 years; 152,883 t life of mine |
| Initial capital cost | US$2.44bn |
| Post-tax NPV (8%) and IRR | US$2.8bn and 24% at US$3.68/lb copper |
| C1 cash cost | US$0.93/lb first 8 years; US$1.25/lb life of mine |
The company's website also shows a post-tax value of US$5.48 billion and an IRR of 37% at US$5.00 a pound copper. Those figures rest on study prices set in 2023, and costs have moved since.
Latest numbers
The company's financial year ends on 30 September. The latest published accounts cover the nine months to 30 June 2026, reported in Canadian dollars.
At 30 June 2026
- C$17.6m cash, down from C$22.8m at 30 September 2025
- C$5.4m net loss for the nine months
- 30.4m shares outstanding at 20 August 2026
Working capital was C$11.6 million. The company capitalised C$4.1 million of exploration spending in the nine months. The loss included a C$2.0 million loss on the derivative tied to its convertible debentures, which moves with the share price. In the June quarter alone it reported net income of C$1.0 million, helped by non-cash gains.
The balance sheet has been shaped by royalty sales and convertible debt rather than large share issues. Royalty holders include Ecora Resources, which paid US$20 million in 2023, Franco-Nevada, Metalla and RCF. In April 2026 Los Andes converted a US$5 million debenture into 638,573 shares. Two convertible debentures held by Queen's Road Capital, of US$4 million and US$5 million, remain outstanding. They pay 8% a year, three percentage points of it in shares. On 1 September the company elected to settle US$67,495 of that interest with 7,281 shares at a deemed price of C$12.92 each.
Main risks
Financing. The company states plainly that it needs more money to begin feasibility work and could have to curtail development without it. Building the mine would cost about US$2.44 billion up front, many times the company's C$17.6 million of cash.
Courts and community. In October 2025 Chile's Environmental Court rejected claims by the Municipality of Putaendo and others against the company's drilling permit. The municipality appealed, and the case was before the Supreme Court as of August 2026, with a ruling expected during 2026. A separate 2022 lawsuit by 24 individuals alleges environmental damage from drilling done between 2007 and 2017, which the company calls unfounded.
Royalty step-ups. The Ecora royalty rate rises in up to three steps if production is delayed beyond 30 June 2030. Los Andes can avoid the second and third increases only by paying US$15 million, or US$20 million if copper is above US$5 a pound, each time.
Leadership and study age. The company has an interim chief executive, and the PFS dates from 2023.
What to watch next
Milestones
- Supreme Court ruling on the drilling-permit appeal, expected by the company during 2026
- Appointment of a permanent chief executive
- Audited annual results for the year to 30 September 2026, which Canadian rules for venture issuers require within 120 days of the year end
- Next quarterly interest settlement on the Queen's Road debentures, which have been dated March, June and September this year
- Any financing to start feasibility work at Vizcachitas
Sources
- Los Andes Copper: MD&A for the nine months ended 30 June 2026 (20 August 2026)
- Los Andes Copper: Election to issue common shares for US$9 million convertible debenture interest (1 September 2026)
- Los Andes Copper: Management change (20 January 2026)
- Los Andes Copper: Vizcachitas project overview
- Los Andes Copper: Stock information and share structure
- Los Andes Copper: 2026 news releases