Sigma Lithium produces lithium oxide concentrate, a raw material for battery chemicals, from a single operation in south-east Brazil. After a year of court cases and stoppages, it is restarting production, refinancing its debt and planning to roughly double capacity. Here is what the company owns, what its latest numbers show and what comes next.
What Sigma does and where
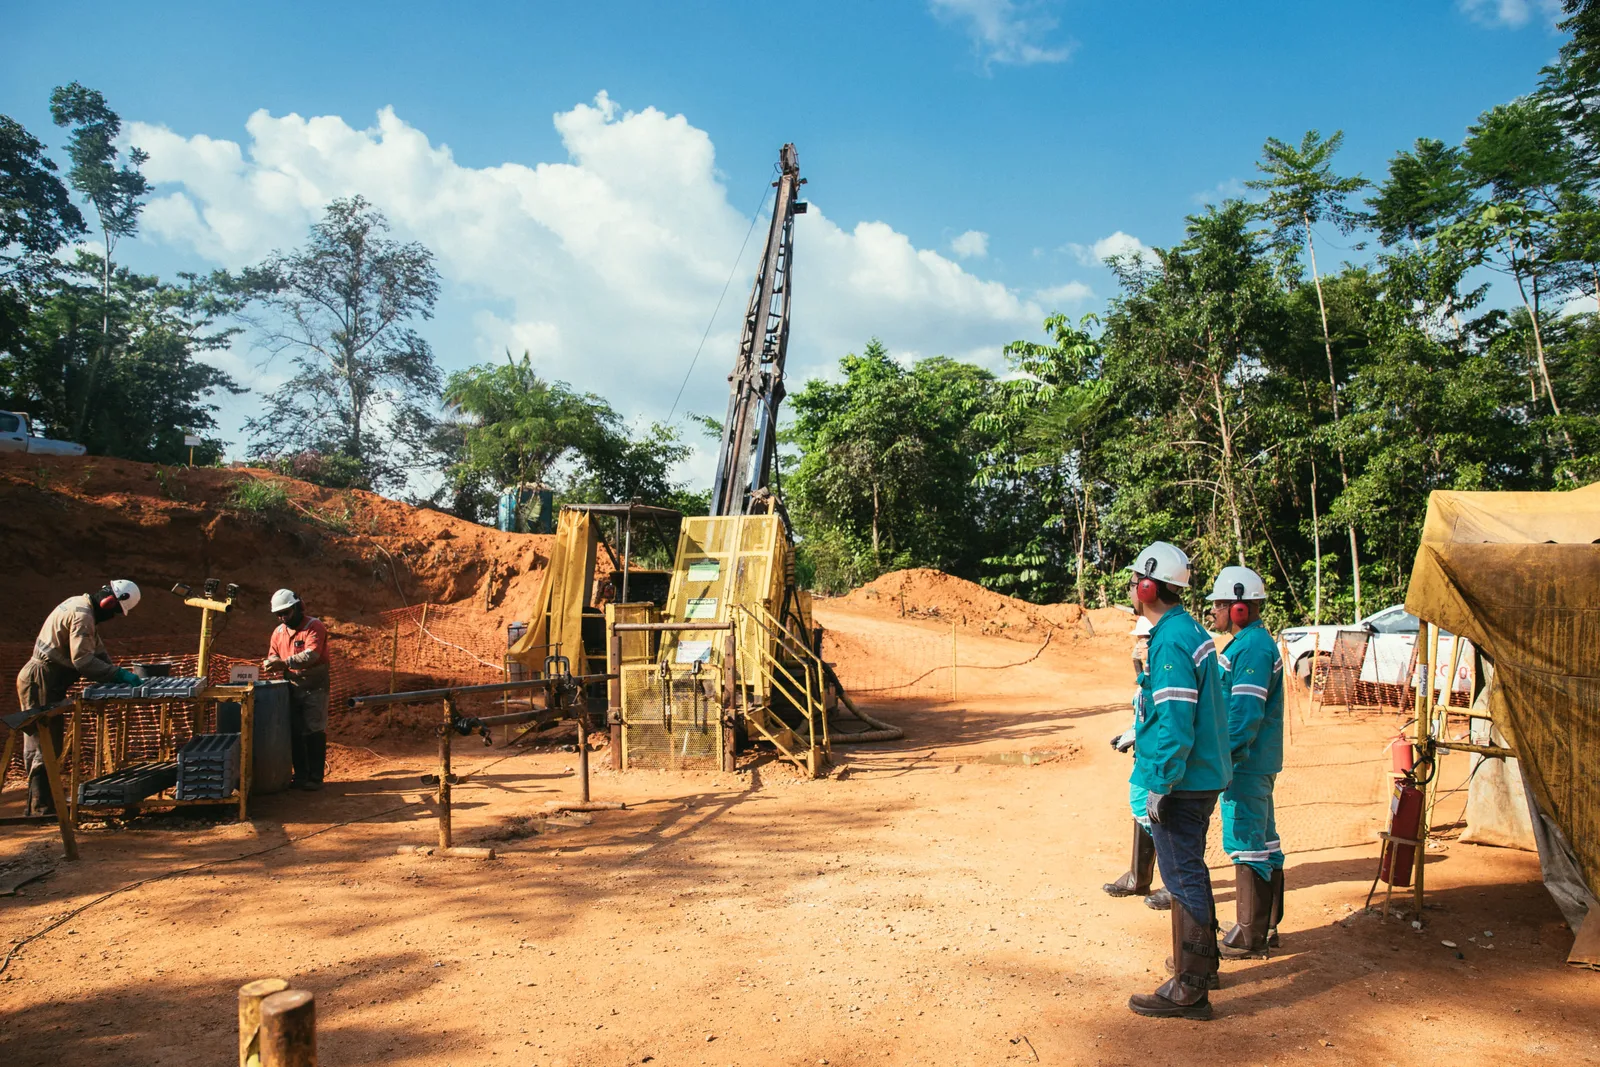
Sigma's operation, Grota do Cirilo, lies in the municipalities of Araçuaí and Itinga in the Jequitinhonha Valley of Minas Gerais. The company owns it outright through its Brazilian subsidiary, Sigma Mineração. It holds 29 mineral rights covering 185 square kilometres within a land package of about 19,000 hectares.
Production began in April 2023. The company calls its processing facility the Cleantech Industrial Plant. Alongside its cost at the plant gate, it reports a cost per tonne including freight and insurance (CIF). Its licences also cover a second mine, Barreiro, and a second processing plant.
Sigma is listed on Nasdaq and the TSX Venture Exchange under the symbol SGML, and on the ASX as SAU through depositary interests. Ana Cabral is co-chairperson and chief executive. The company had 112,690,313 shares in issue at 30 September 2026 and reports in US dollars.
Sigma Lithium: share price, chart and news
Key numbers
| Measure | Q3 2026 | Nine months 2026 |
|---|---|---|
| Production | 7,300t | 66,300t |
| Gross revenue | $22.3m | $115.4m |
| Adjusted EBITDA | minus $6.7m | $35.7m |
| Net loss | $25.9m | $17.4m |
| Operating cash flow | $24.2m | $51.3m |
| CIF cost per tonne | $518 | $505 |
The third quarter was hit by two suspensions. The first ran from 17 July to 22 August, until Sigma entered a conduct adjustment agreement with Minas Gerais authorities. The second began on 30 September, when a federal court issued a preliminary injunction in a lawsuit brought by a non-governmental organisation. A federal appeals court upheld Sigma's environmental licences on 6 October, and production restarted in early October. By 10 November the company had produced 11,000 tonnes of high-grade concentrate since the restart.
Realised prices averaged $1,485 a tonne in the quarter. Sigma's all-in sustaining cost guidance for 2026 is $668 a tonne, cut from $710 in a 2 November preview; the third quarter came in at $642.
Balance sheet and the new bond
At 30 September Sigma held $10.4m of cash and owed $140.1m in loans and export prepayments, $127.0m of it due within a year. Net debt was $105m on the company's measure. Working capital was negative by $218.6m, and the accounts say this may cast doubt on its ability to continue as a going concern, although management is comfortable preparing them on that basis.
The $125m convertible bond priced on 2 November is meant to change that profile. It pays a fixed 7%, matures in about November 2031, lets holders demand repayment after about three years and converts at $6.51 a share. The money repays the Synergy Capital export prepayment, which cost about 11.45%. Sigma says pro forma short-term debt falls to about $19m, while pro forma net debt is $145m.
If all the bonds converted, about 19.2m new shares would be issued, roughly 17% of the current share count on our calculation. Sigma says it has not issued equity since 2021. It also says it has been self-funded since July 2023 and has repaid more than $90m of debt since the second quarter of 2024.
Beyond the bond, the company pointed in its third-quarter preview to up to $62m of potential short-term liquidity: about $10m of receivables for high-grade sales, about $20m of unsold low-grade inventory and $32m of remaining offtake instalments. Sigma said the timing of that money depends on sales and on lithium prices, so it is not cash in hand.
Growth plans
- 2027: 330,000 tonnes from the first plant, made up of about 68,000 tonnes a quarter of high-grade concentrate and 15,000 tonnes a quarter from tailings reprocessing, at an all-in sustaining cost of $620 a tonne.
- Phase 2: construction of a second plant resumes in 2027, adding 250,000 tonnes a year to reach 580,000, funded by a BRL 492m loan from development bank BNDES with a 16-year term.
- Phase 3: targeted for 2028, taking capacity to 830,000 tonnes a year, supplied by a second mine with about 30 million tonnes of resources.
Sigma estimates that at concentrate prices of $1,000 to $1,500 a tonne, the first plant would generate $125m to $290m of pre-tax cash flow in 2027. These are company projections that depend on prices and on operations running without interruption, which was not the case in 2026.
Risks and what to watch
Main risks
- Permits and courts: further court steps follow the October appeal ruling, including a court-appointed expert's assessment, and mining regulator ANM has issued an improvement notice on a slope at the depleted North Pit, which Sigma says is not a stoppage
- Liquidity: thin cash and negative working capital, with going-concern wording in the accounts
- Controls: auditor Grant Thornton gave an adverse opinion on internal control over financial reporting at the end of 2025; Sigma targets remediation by the end of 2026
- Disputes: $27.8m of supplier balances disputed by Sigma at 30 September, plus claims it rates as possible losses; an arbitration brought by LG Energy Solution was decided in Sigma's favour
- Prices: revenue depends on volatile lithium concentrate prices
- Dilution: the convertible bond could add about 19.2m shares
| Timing | Event |
|---|---|
| On or about 16 Nov 2026 | Closing of the $125m convertible bond and repayment of Synergy Capital |
| Q4 2026 | Sale of about 21,000 tonnes of high-grade-equivalent inventory |
| End of 2026 | Target for fixing internal control weaknesses |
| 2027 | Phase 2 construction restarts; 330,000 tonne production goal |
| 2028 | Phase 3 target of 830,000 tonnes a year |
| About Nov 2029 | Bondholders' option to demand repayment |
For investors, the central question is whether Sigma can run its plant without further legal or regulatory stoppages long enough to rebuild cash, because every expansion plan and cash-flow projection assumes it can.
Sources
- US SEC: Sigma Lithium 3Q 26 results release (Form 6-K)
- US SEC: Sigma Lithium interim financial statements to 30 September 2026 (Form 6-K)
- US SEC: Sigma Lithium MD&A for the six months to 30 June 2026 (Form 6-K)
- US SEC: Sigma Lithium Previews 3Q 26 Earnings (Form 6-K)
- Newsfile via Finviz: Sigma Lithium Prices Offering of US$125 Million Convertible Bonds Due 2031