Alkane Resources, the gold and antimony miner with mines in Australia and Sweden, produced 40,740 gold-equivalent ounces in the September quarter and ended it with A$440 million in cash and bullion, after paying the first dividend in its history. It kept its full-year guidance unchanged.
A quarter below the cost guidance range
Alkane's first quarter of the 2027 financial year, which runs from July to June, brought 39,823 ounces of gold and 396 tonnes of antimony. Converted at market prices, that equals 40,740 gold-equivalent ounces, the company said in its quarterly report on 23 October.
The all-in sustaining cost (AISC) was A$2,805 per gold-equivalent ounce, below the full-year guidance range of A$2,900 to A$3,200. Group cash costs were A$2,424 an ounce. Managing director Nic Earner called it "a solid start to FY27 for Alkane".
Sales were lower than production. Alkane sold 38,348 gold-equivalent ounces for revenue of A$206 million, down from 47,411 ounces and A$257 million in the June quarter. The average gold sales price was A$5,128 an ounce, against A$5,599 in the previous quarter, and the antimony price fell to A$23,842 a tonne from A$30,602. The mines generated A$102 million of operating cash flow.
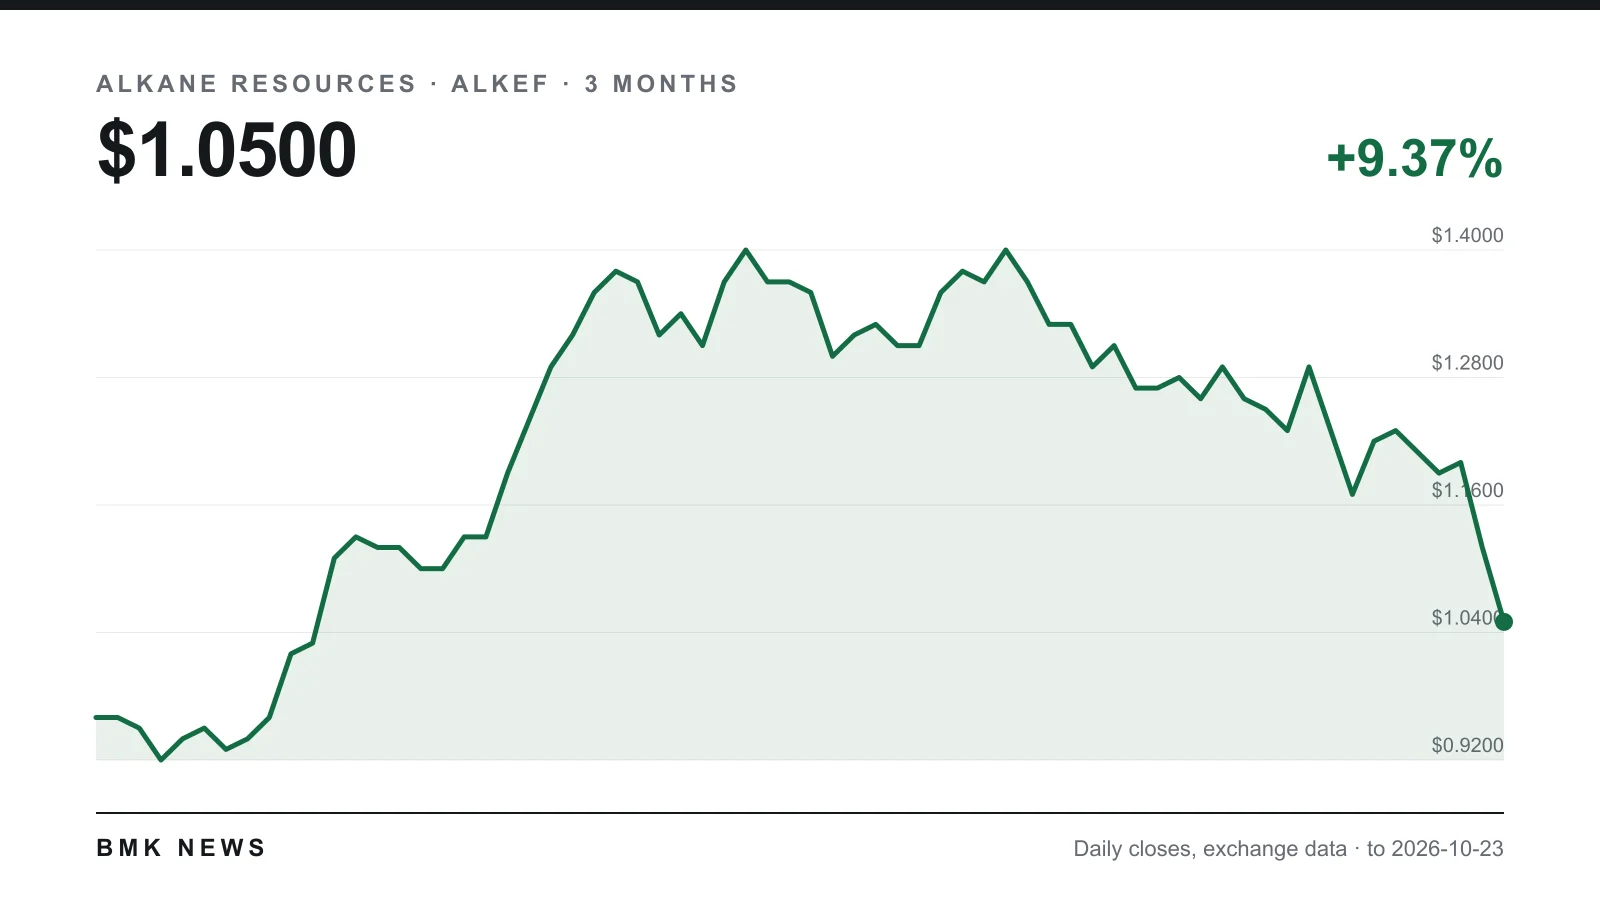
Alkane Resources: share price, chart and news
How the three mines performed
| Mine | Output (Q1 FY27) | AISC | Site cash flow |
|---|---|---|---|
| Tomingley, New South Wales | 21,506 oz gold | A$2,340/oz | A$52m |
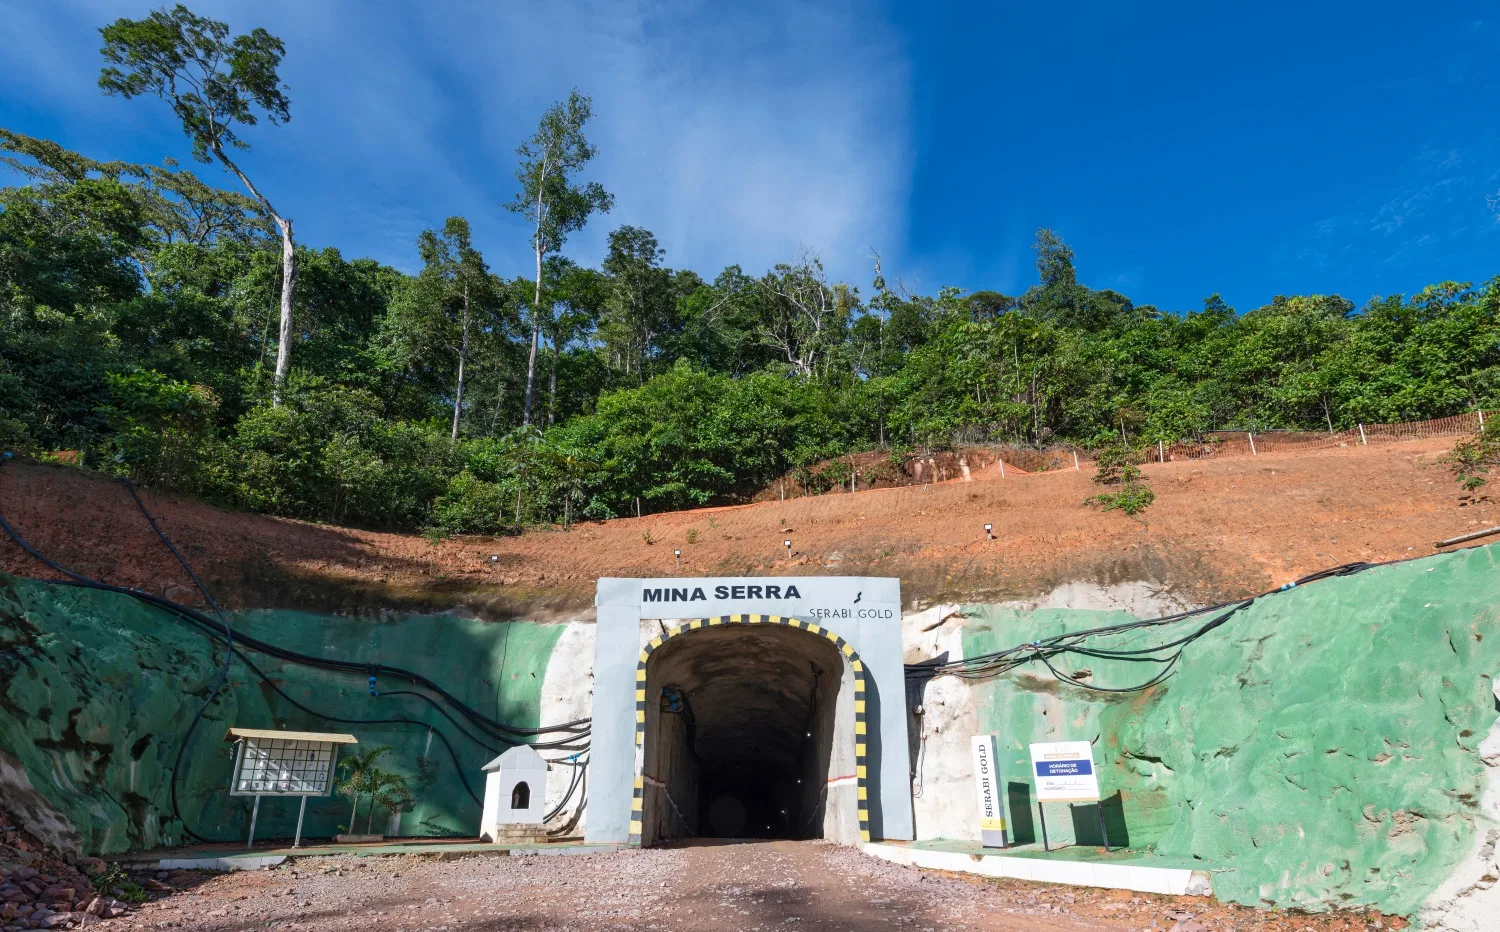
| Costerfield, Victoria | 8,752 oz AuEq (7,835 oz gold, 396 t antimony) | A$3,194/oz | A$29m |
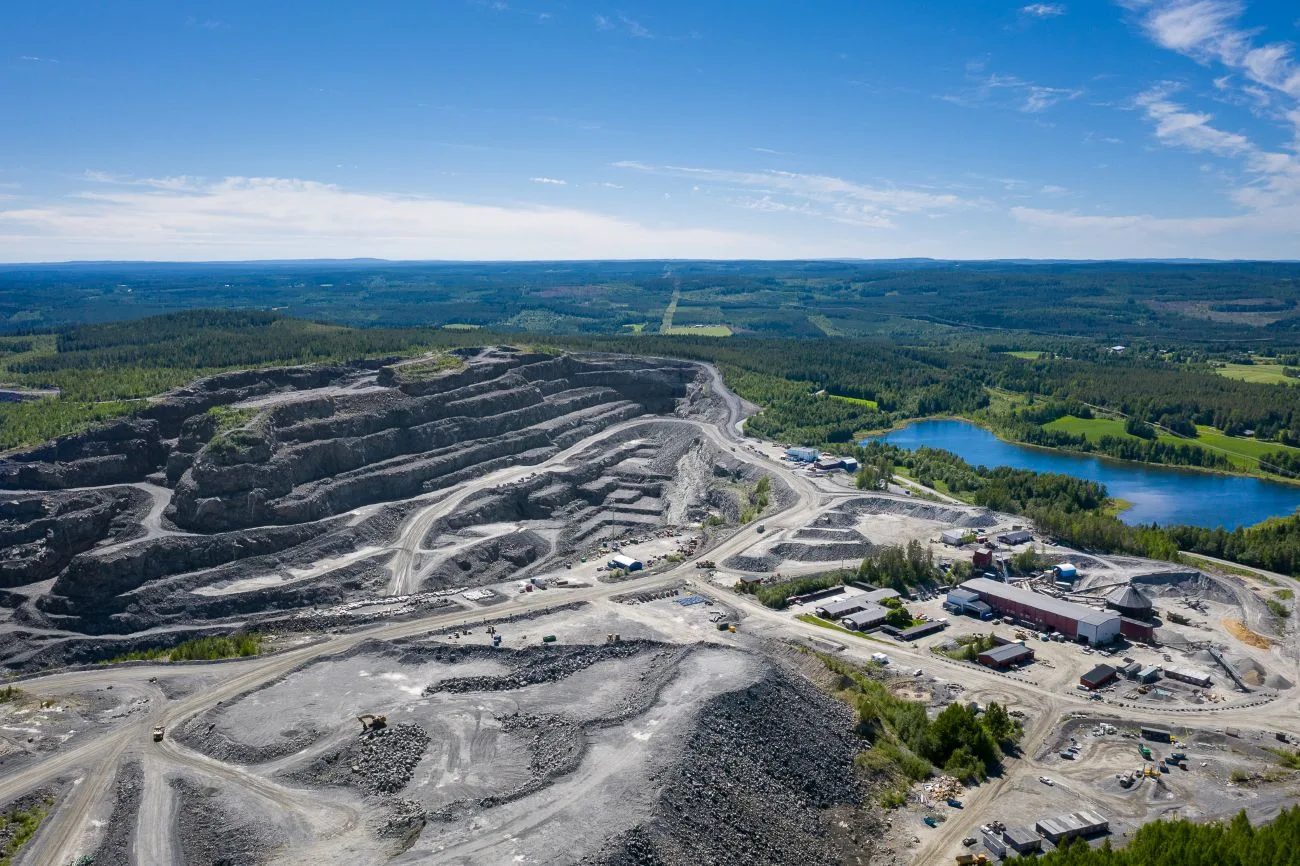
| Björkdal, Sweden | 10,482 oz gold | A$3,012/oz | A$21m |
Tomingley set monthly records for both mining and processing, and its output rose from 20,896 ounces in the June quarter. Its average sales price was held down by 7,800 ounces delivered into forward contracts at A$2,884 an ounce, far below the market.
Costerfield's gold-equivalent output fell from 11,659 ounces, and its AISC rose from A$2,568 an ounce. The site also took a negative price adjustment of about A$1 million as antimony prices declined; the closing Shanghai price was down 9% on the previous quarter. Björkdal moved the other way, with AISC falling from A$4,184 to A$3,012 an ounce, and its revenue included a A$10 million positive price adjustment on concentrate sales.
Cash, dividend and buyback
Q1 FY27
- 40,740 oz gold-equivalent production
- A$2,805/oz all-in sustaining cost
- A$440m cash and bullion at 30 September
Including A$19 million of listed investments, Alkane's liquid assets totalled A$459 million. During the quarter it paid A$13 million of income tax and transferred A$24 million for its maiden fully franked dividend of 2 cents a share, with a further A$4 million for Toronto-listed holders paid on 1 October.
The company expects final income tax payments for the 2026 financial year of A$55 million to A$60 million in the December quarter. It has a A$110 million revolving credit facility that remains undrawn and A$16 million of equipment financing. In August the board approved an on-market buyback of up to A$50 million over twelve months.
Capital spending in the quarter totalled A$59 million, of which about A$37 million was for growth. The biggest item was A$16 million for diverting the Newell Highway at Tomingley, which will open up the San Antonio open pit. Alkane now expects traffic to switch to the new road early in the June 2027 quarter, subject to weather, with open-pit mining to follow.
Exploration and what comes next
Alkane released two drilling updates after the quarter. On 15 October it reported a 1,651-metre hole under the Peak Hill mine that intersected epithermal mineralisation about a kilometre below the old pit, and it plans 6,600 metres of follow-up drilling. On 20 October it published first assays from Nagambie in Victoria, where it can earn 60% by spending A$12.5 million over three years.
The company reaffirmed guidance of 163,000 to 177,000 gold-equivalent ounces for the year to June 2027 at an AISC of A$2,900 to A$3,200 an ounce.
Points to watch
- December quarter: A$55 million to A$60 million of tax payments will reduce cash.
- Antimony price: lower prices cut Costerfield's revenue and its gold-equivalent output.
- Hedges: forward sales well below spot prices reduce Tomingley's realised price.
- Björkdal: ore extraction from the Nylunds open pit is due to begin, and the new Storheden portal to be established, in the current quarter.
Alkane is now a profitable mid-tier producer with a strong cash position, but its results remain tied to gold and antimony prices, and its growth projects, including the highway diversion and Storheden, carry the usual risks of delays and cost overruns.
Sources
- Alkane Resources: Quarterly Report, September 2026 (ASX, 23 October 2026)
- Alkane Resources: September 2026 Quarter Production Update (ASX, 9 October 2026)
- Alkane Resources: Deep drilling at Peak Hill (ASX, 15 October 2026)
- Alkane Resources: Drilling extends gold-antimony system at Nagambie (ASX, 20 October 2026)
- Alkane Resources: Final dividend and share buy-back (ASX, 21 August 2026)