Aya Gold & Silver is a Canadian company whose business sits almost entirely in Morocco: one producing silver mine, Zgounder, a large gold-silver project at Boumadine that is now in feasibility study, and a growing exploration portfolio. This profile sets out what it owns, its latest reported numbers and the main risks.
What Aya does and where
Aya describes itself as a precious metals company anchored in Morocco, with its corporate office in Mont-Royal, Quebec. Its shares trade on the Toronto Stock Exchange and, since a listing announced in May 2026, on Nasdaq, both under the symbol AYA. In June 2026 the company said it had been added to the VanEck Gold Miners ETF (GDX).
The company reports in US dollars. Its revenue comes from silver doré produced at Zgounder and, in 2026, also from pyrite sold out of an old stockpile at Boumadine that the company began reclaiming under a plan announced in November 2025.
Aya Gold & Silver: share price, chart and news
Key assets
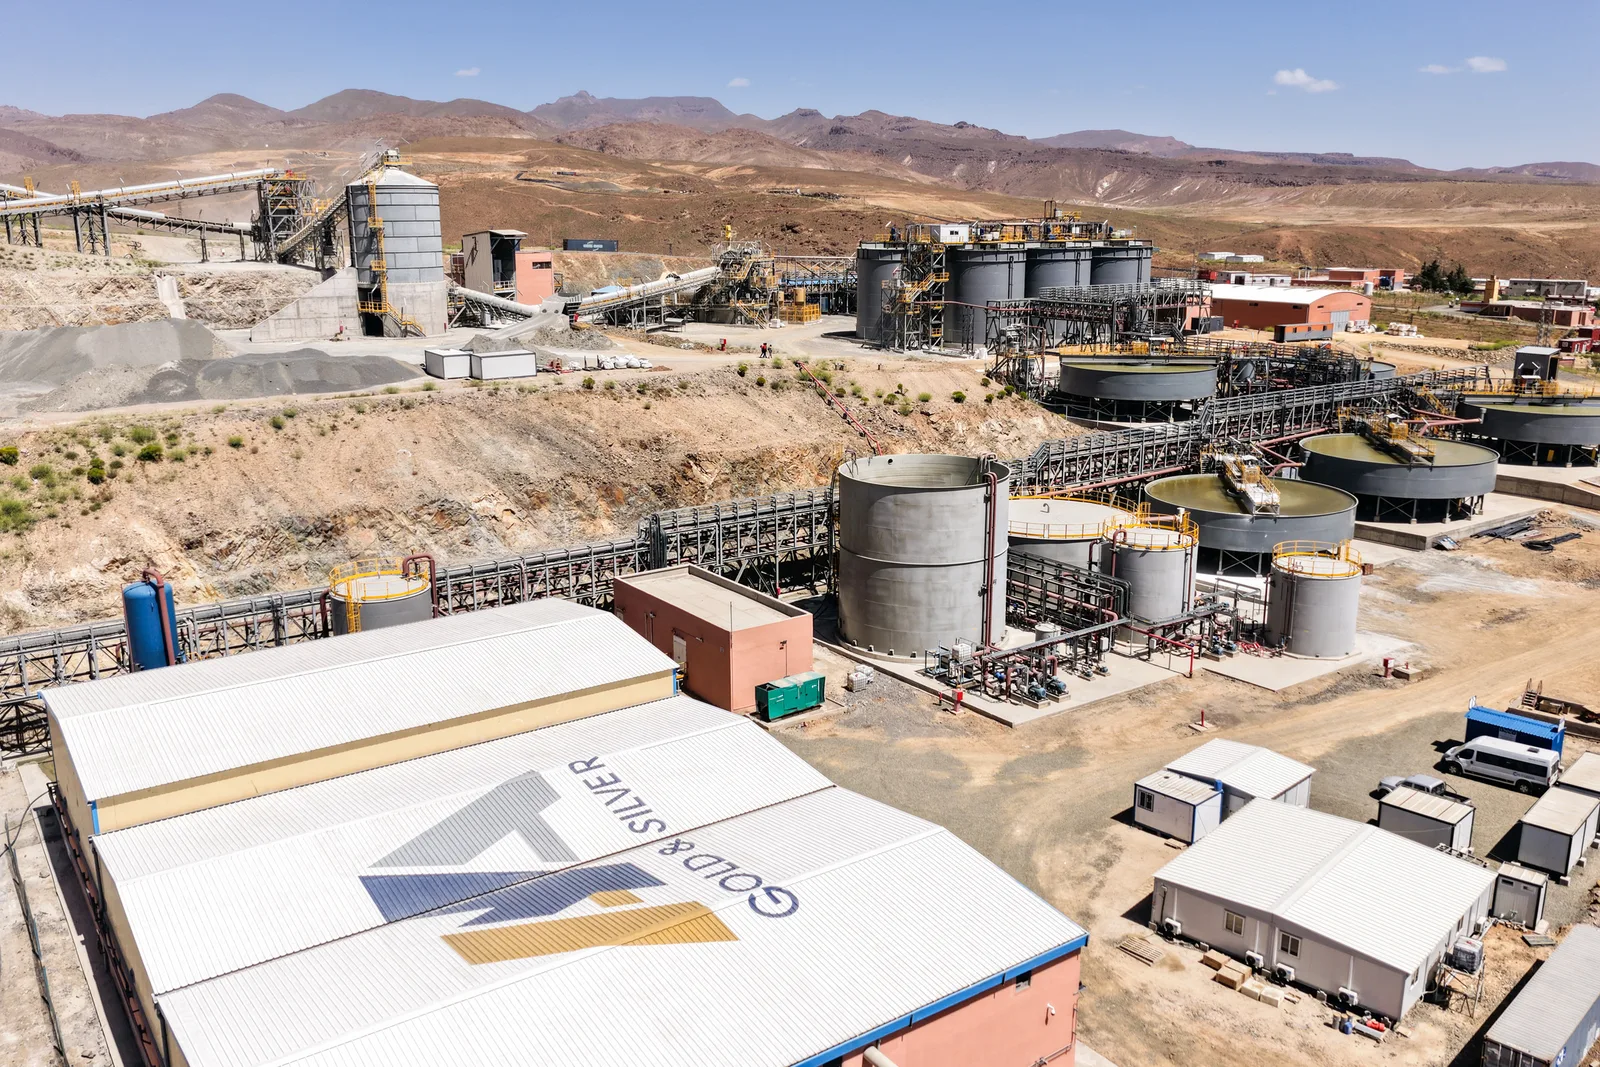
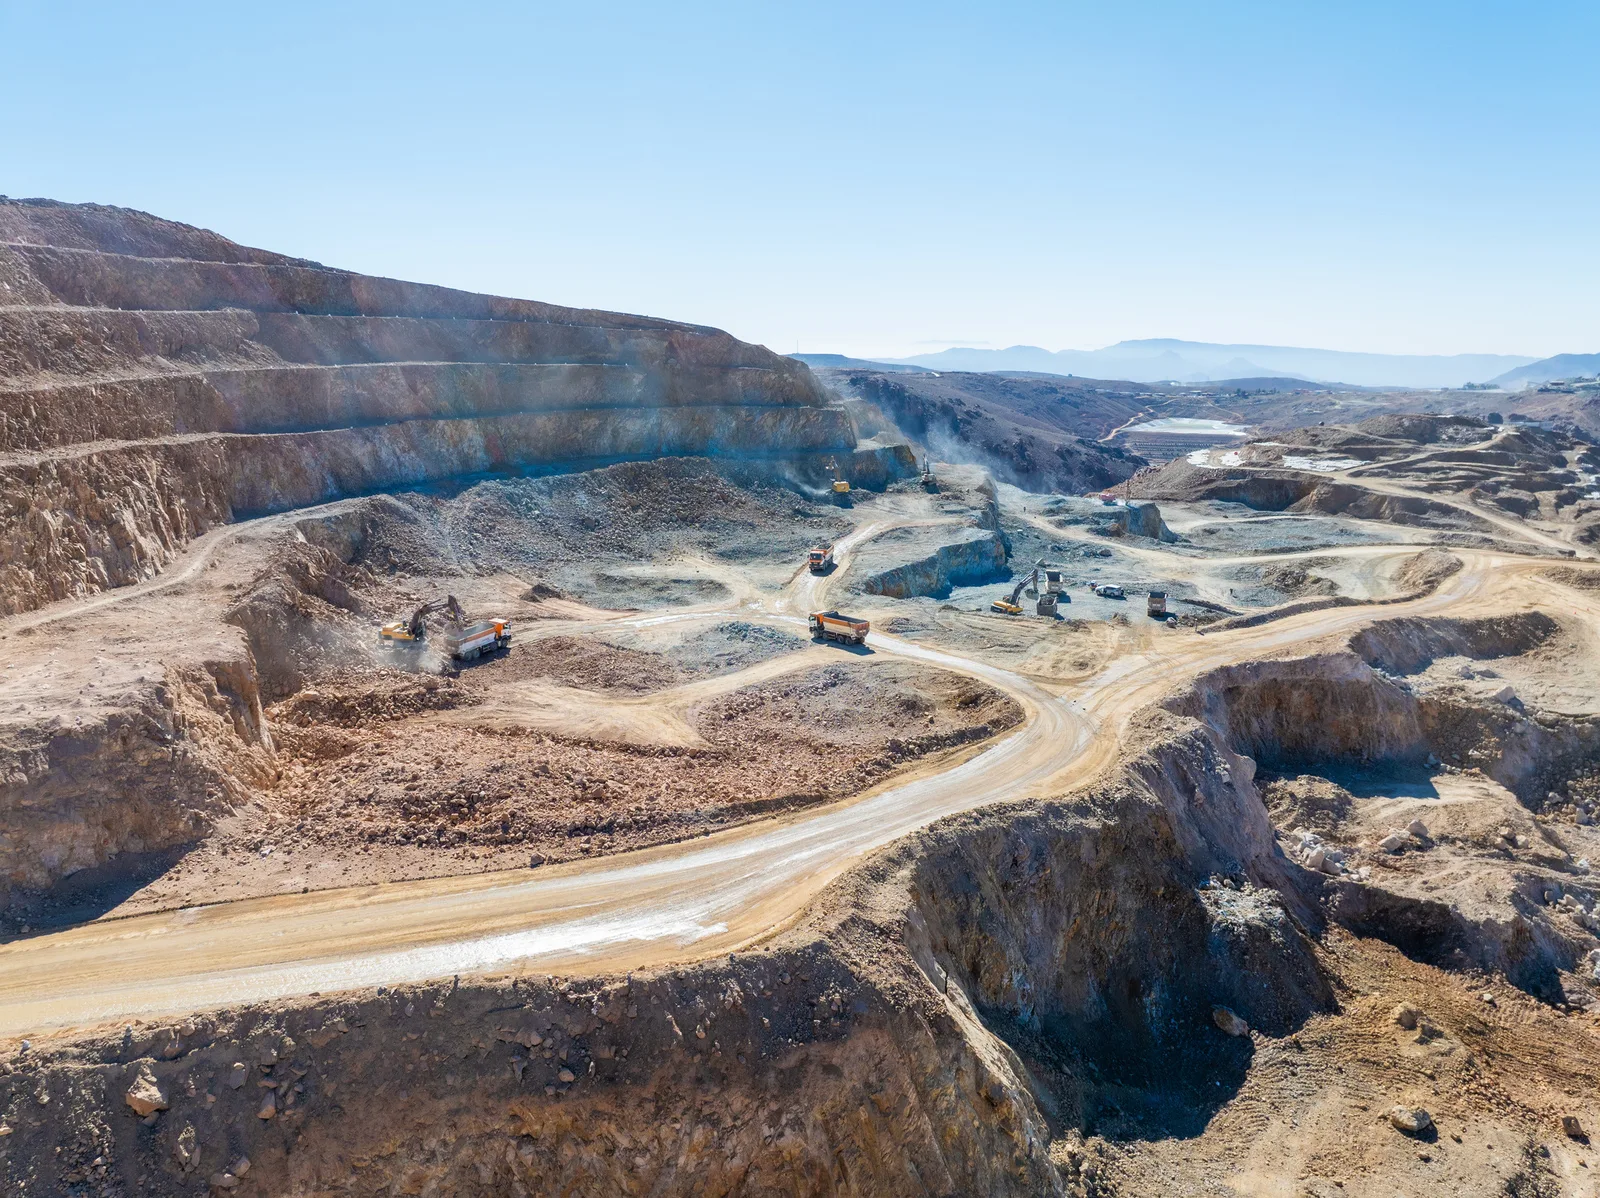
Zgounder (silver). The mine lies in Taroudant province in the central Anti-Atlas mountains. Aya's project page lists it as wholly owned. An expanded plant reached commercial production on 29 December 2024; it is designed for 3,650 tonnes a day through 2026 and 3,850 tonnes a day after that. In the third quarter of 2026 the mill averaged 4,096 tonnes a day.
The company reports proven and probable reserves of 73 million ounces of silver at 145 grams per tonne, as at 30 September 2025, and measured and indicated resources of about 100 million ounces at 165 g/t. Its mine plan runs to 2036, with average output of about 6 million ounces a year. Open-pit pushbacks are planned from late 2026 through 2027.
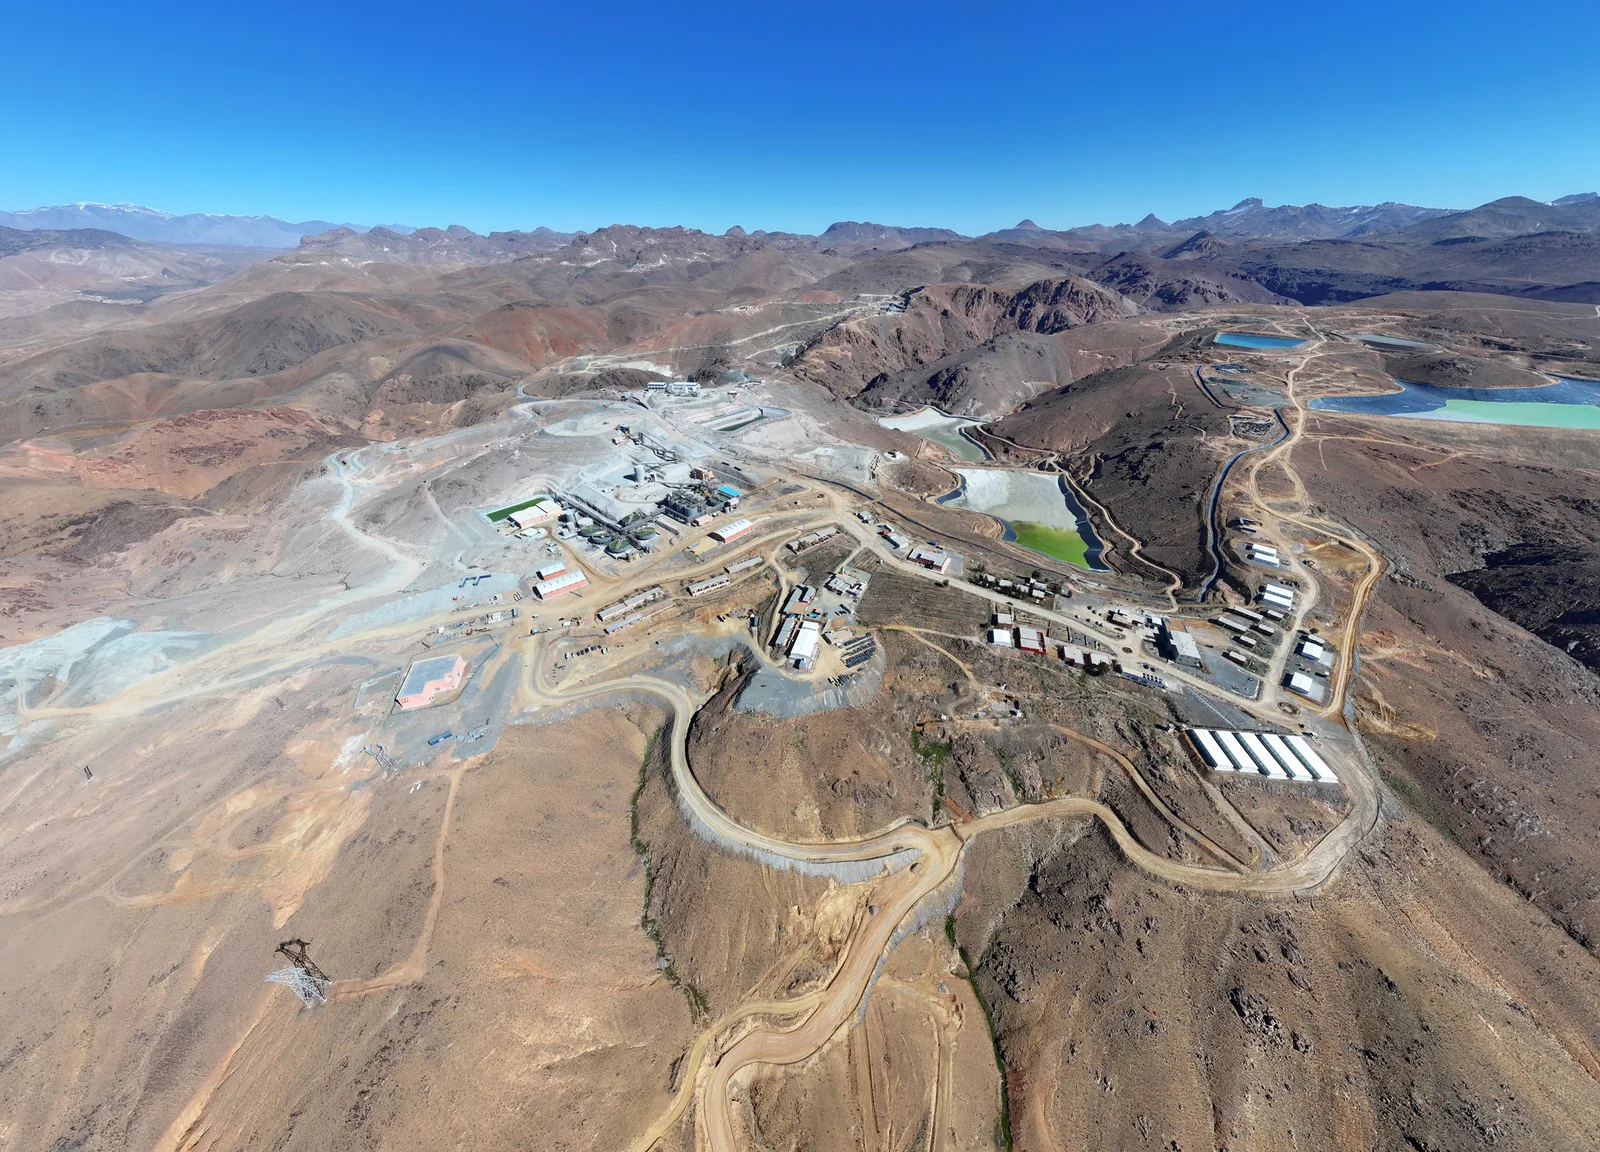
Boumadine (gold, silver, zinc, lead). The project sits in Errachidia province, about 70 kilometres south-west of the city of Errachidia, and already holds a mining licence. A preliminary economic assessment (PEA) published on 9 September 2026 set out the following base case.
Boumadine PEA, September 2026 (after tax, base case)
- $3.5bn net present value at a 5% discount rate
- 93% internal rate of return
- $463m initial capital, including $99m contingency
The PEA assumes 8,000 tonnes a day of processing, a 14-year life and average output of 271,000 gold-equivalent ounces a year over the life of mine, at all-in sustaining costs of $1,300 per gold-equivalent ounce. Base-case prices were $3,500 gold and $50 silver. The updated resource includes 8.6 million tonnes indicated and 45.4 million tonnes inferred; because the PEA leans on inferred material, it is preliminary and not a basis for reserves.
Drilling continues alongside the study. Infill drilling at Boumadine reached 181,685 metres by 31 October 2026, past the 180,000-metre target, and the company reported intercepts such as 392 g/t silver equivalent over 24.3 metres in its third-quarter update.
Exploration and other projects. Aya also holds Imiter Bis and, in 2026, added a 259 square kilometre Anti-Atlas portfolio in August and the Tizi copper-silver permits, about 35 kilometres west of Zgounder, in October. It says its Moroccan land package now exceeds 1,200 square kilometres. In November it signed a term sheet to sell the Azegour copper-tungsten-molybdenum project, south-south-west of Marrakech, to Sama Resources in exchange for up to 19.11% of Sama's shares.
Latest reported numbers
The company called the third quarter of 2026 a record in its 12 November results.
| Measure | Q3 2026 | Change on Q3 2025 |
|---|---|---|
| Production (AgEq oz) | 2,034,628 | +51% |
| Zgounder silver produced (oz) | 1,497,749 | +11% |
| Revenue | $103.3m | +90% |
| Net income | $35.0m | +182% |
| Operating cash flow | $48.1m | +115% |
| Consolidated cash cost per AgEq oz sold | $15.51 | -25% |
Over the first nine months, revenue was $317.4 million and net income $118.6 million. Cash and equivalents stood at $183.8 million at 30 September, plus $16 million restricted, with working capital of $153.7 million. Non-current financial liabilities were $43.6 million. The results release does not state a share count.
For 2026 the company guides to 6.6 to 6.8 million AgEq ounces, including about 1.0 million from the Boumadine reclaim, and Zgounder cash costs below $21.50 an ounce.
Main risks
Risks investors should weigh
- Single country. All producing and development assets are in Morocco, so permits, tax and policy there matter to the whole company.
- Metal prices. Revenue tracks silver, and Boumadine's value depends on gold, silver, zinc and lead prices.
- Development and funding. Boumadine needs an estimated $463 million of initial capital before production, and its environmental and social impact assessment is still under way.
- Temporary output. The Boumadine reclaim is expected to last only about 20 to 24 months from November 2025.
- Litigation. Aya is in a dispute with Duro Felguera over the Zgounder plant contracts, before a Spanish appeal court and ICC arbitration.
The company does not report all-in sustaining costs for Zgounder in its quarterly release, which makes margin comparisons with other silver producers harder. Its realised silver price of $69.32 an ounce in the third quarter was well above the $50 used in guidance, so a lower silver price would hit cash flow directly.
What to watch next
| When | What |
|---|---|
| Late 2026 | Start of open-pit pushbacks at Zgounder |
| Pending | Definitive agreement and approvals for the Azegour sale to Sama |
| Early 2027 | Full-year 2026 production against the 6.6 to 6.8 million AgEq ounce guidance |
| Through 2027 | A 400,000-metre drilling programme at Boumadine |
| H2 2027 | Boumadine feasibility study and environmental assessment |
Aya ended the third quarter with cash, low financial liabilities and rising output. The next test is whether Zgounder holds its costs as the pit is pushed back, and how the company proposes to pay for Boumadine once the feasibility study is published.