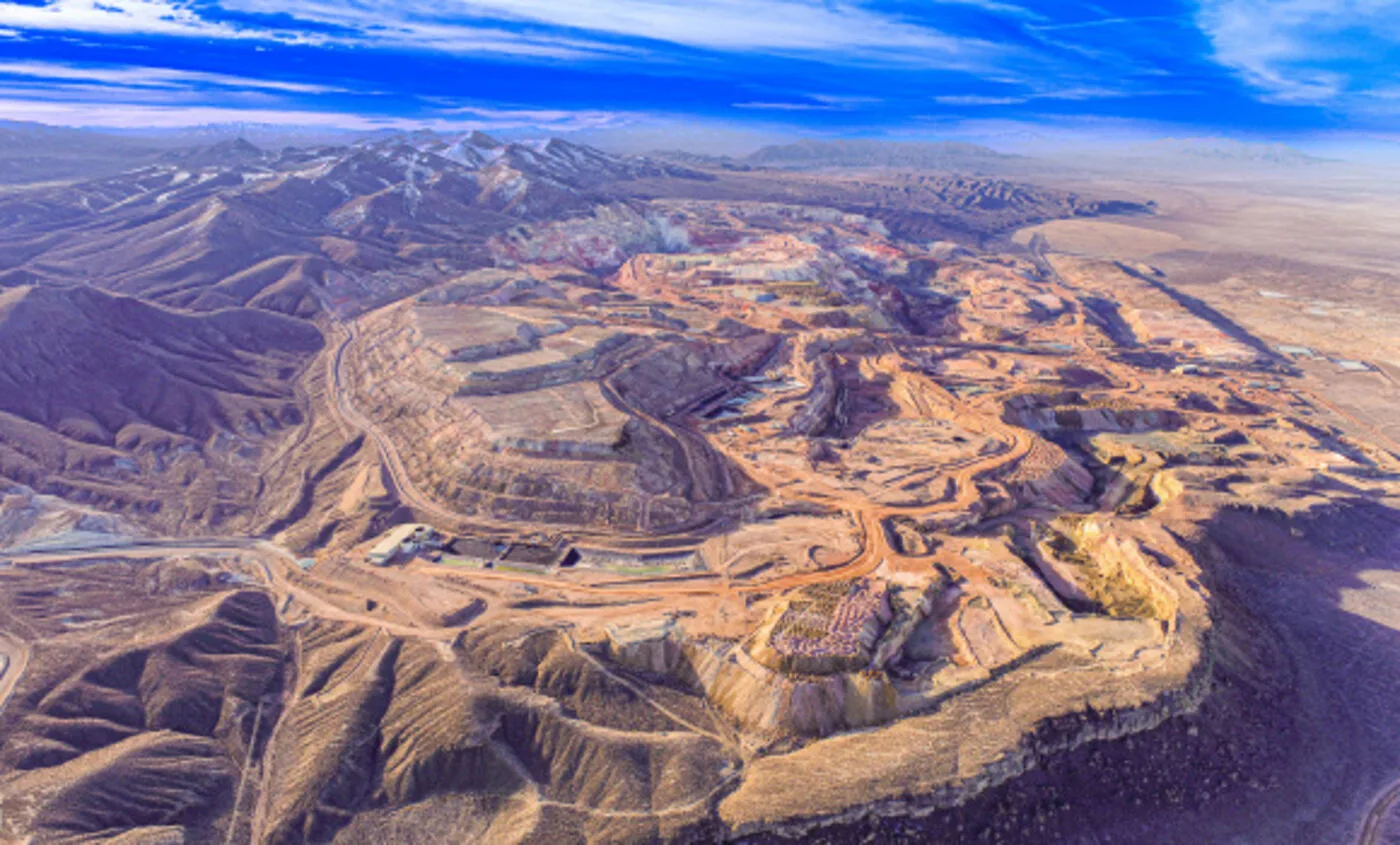
Hycroft Mining owns a very large gold and silver resource at its Nevada mine, $211m of cash and no debt, but no production. Its story now turns on high-grade silver discoveries at Vortex and Brimstone and on whether they can be mined underground, while warrants that convert into about 3.7 million shares expire in March.
What Hycroft Owns and Where
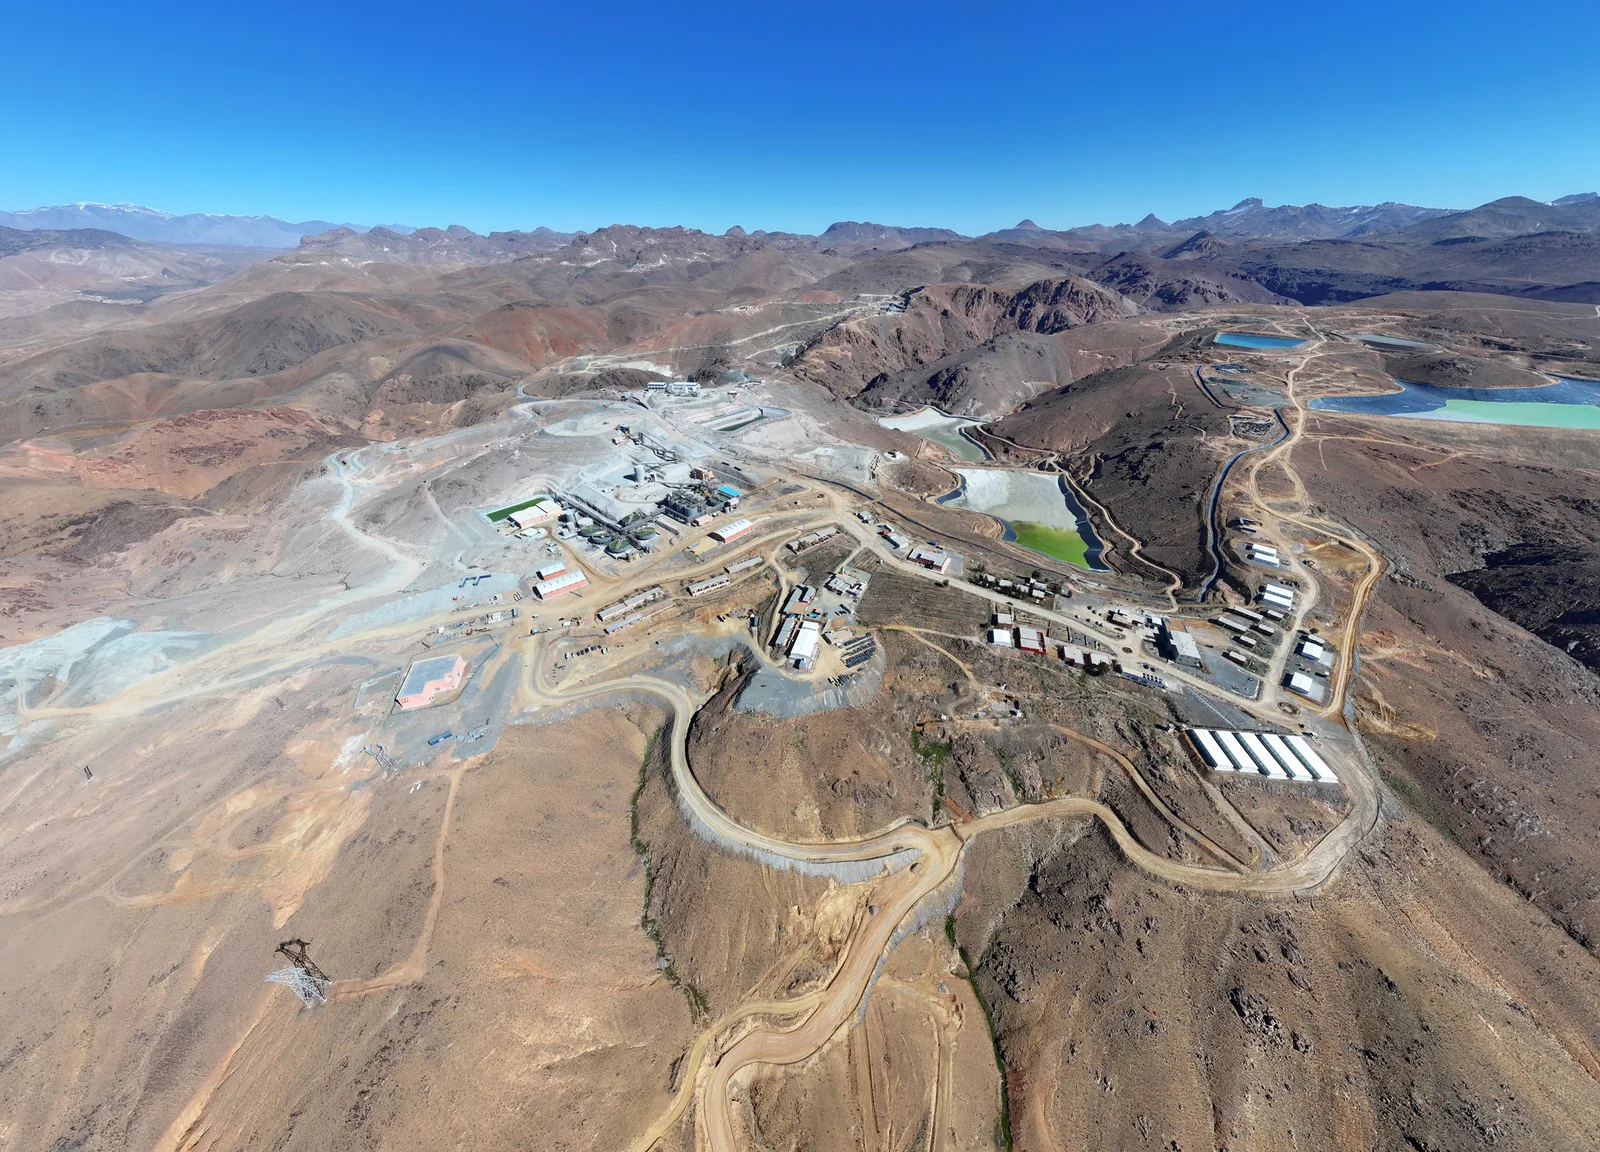
The Hycroft Mine sits on the western flank of the Kamma Mountains, on the eastern edge of the Black Rock Desert, about 54 miles west of Winnemucca in Humboldt and Pershing counties, Nevada. The company is listed on Nasdaq as HYMC and based in Winnemucca. It has worked the site before through heap leaching, and is now testing whether a heap-leach restart makes sense.
Its mineral resource, effective 21 January 2026, is very large but low grade on average. The figures are in short tons, the US measure.
| Category | Tons | Gold (oz/ton) | Silver (oz/ton) | Gold (m oz) | Silver (m oz) |
|---|---|---|---|---|---|
| Measured and indicated | 1,686.8m | 0.010 | 0.33 | 16.4 | 562.6 |
| Inferred | 569.7m | 0.009 | 0.23 | 5.0 | 132.8 |
Hycroft Mining: share price, chart and news
The June Study
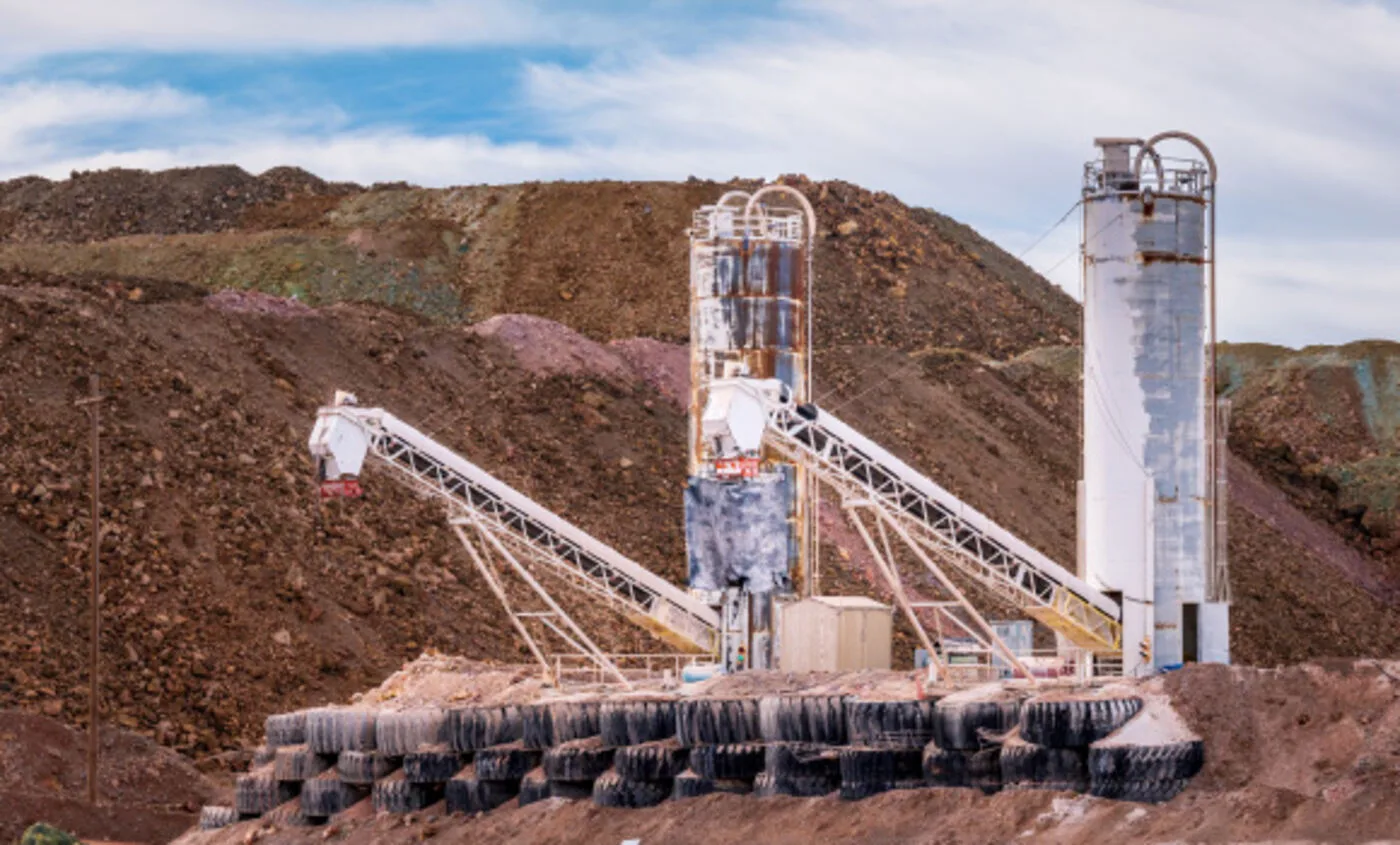
On 2 June Hycroft published an initial assessment under US rules (S-K 1300). It is an early-stage study, not a pre-feasibility or feasibility study. It describes a flotation mill with pressure oxidation and cyanide leaching, plus heap leaching for oxide material, running for 51 years.
| Measure | Base case ($3,600 gold, $48 silver) | Spot prices on 25 May |
|---|---|---|
| After-tax NPV at 5% | $4.3bn | $10.0bn |
| After-tax IRR | 16.9% | 30.1% |
| After-tax payback | 4.7 years | 2.9 years |
The base case needs $2.43bn of initial capital and $3.11bn of sustaining capital. It produces an average of 204,000 ounces of gold and 6.8 million ounces of silver a year, at all-in sustaining costs of $2,147 an ounce of gold equivalent. Recoveries in the mill are 82.8% for gold and 77.5% for silver.
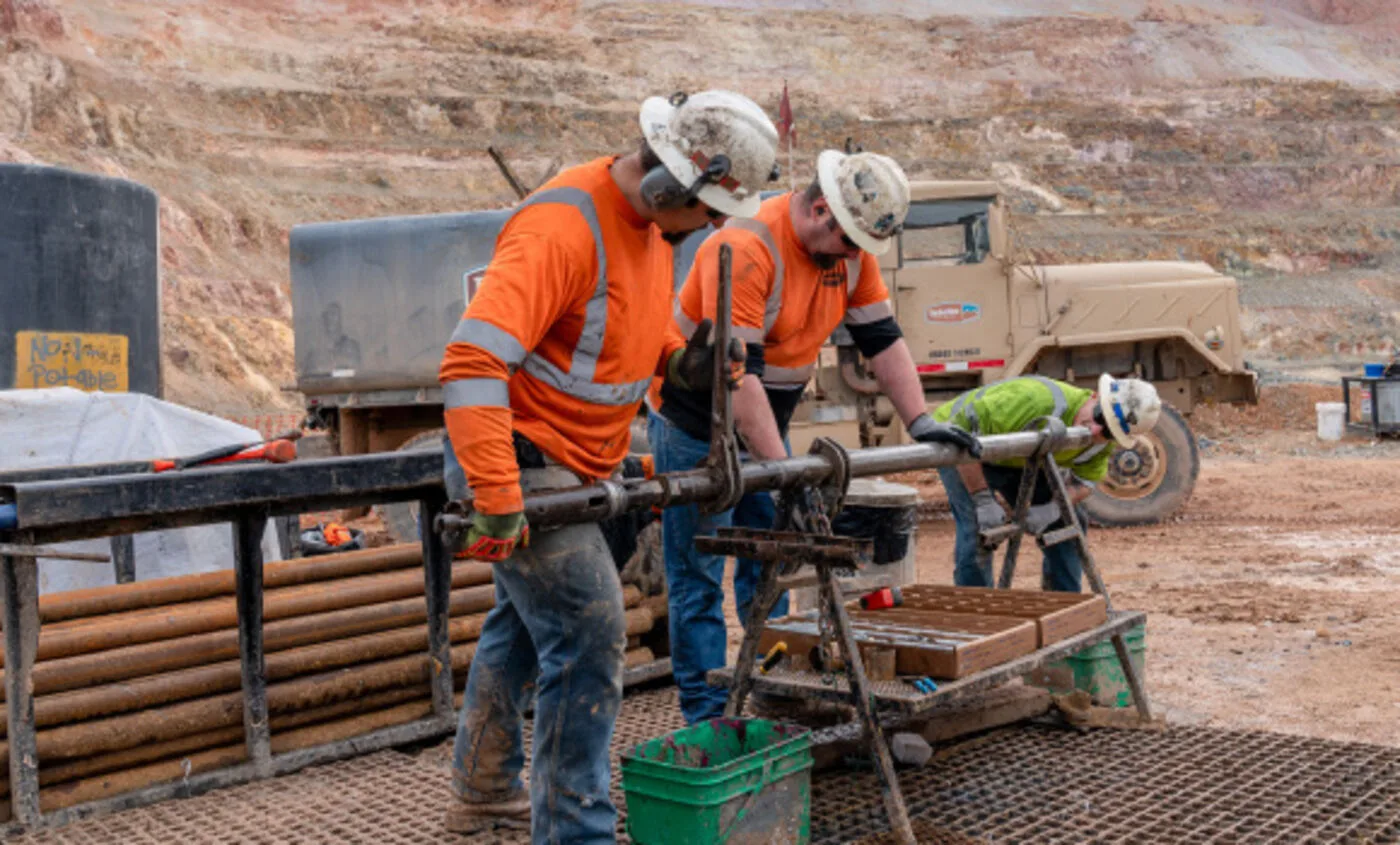
Before any mill is built, the company is also weighing a cheaper first step. A reverse circulation drill programme that began in late 2025 mapped the quantity, location and character of oxide and transition material that could suit heap leaching, and metallurgical tests on it are under way. Hycroft says it will decide on next steps once those tests are finished, which it now expects in the first half of 2027.
The team has changed this year as well. Diane Garrett became executive chairman as well as chief executive in May, Michael Deal was named chief operating officer in July, effective 24 August, and four new independent directors have joined the board.
The High-Grade Discoveries
The newer interest is in two high-grade silver systems, Vortex and Brimstone. On 13 October Hycroft reported its best hole yet at Vortex: 19.6 metres grading 30.49 g/t gold and 1,726.72 g/t silver, with visible gold. About 18,700 metres have been drilled since the 2025-2026 programme began. "Both systems continue to grow and remain open in all directions and at depth," Garrett said with the third-quarter results.
A conceptual design for a high-grade underground mine and processing plant, drawn up with RESPEC and Hatch, is substantially complete and will feed into project optimisation in 2027. A trade-off study comparing roasting with pressure oxidation is being finalised, with results expected in the first quarter of 2027.
Cash, Shares and Dilution
Hycroft at 30 September 2026
- $211.2m unrestricted cash, plus $14.6m restricted, and no debt
- 93.18m shares outstanding on 26 October
- 7.84m shares issuable if all 40.97m warrants are exercised
The third-quarter net loss was $26.1m, or 28 cents a share, and the nine-month loss $95.2m. Exploration and development costs rose to $26.5m in nine months from $9.3m, and operations used $51.7m of cash. Interest income on the cash pile was $5.8m over the nine months.
Dilution is a live issue. Hycroft sold 1.48 million shares through its at-the-market programme this year for $35.8m net, and $55.3m of capacity remains. Of the warrants, 36.81 million expire on 15 March 2027. After an earlier 1-for-10 share consolidation, ten of them buy one share for a combined $10.68, so together they would add about 3.68 million shares, around 4% of the count, and raise about $39m. Another 4.16 million warrants at $4.20 run to June 2028. In all, the warrants could add about 7.8 million shares, roughly 8%.
At the 11 November close of $18.70 the company was worth about $1.74bn, against $211m of cash. A perpetual 1.5% net smelter return royalty, granted under its Sprott royalty agreement for $30m, applies to future production.
The Main Risks
What could go wrong
- No revenue. Hycroft is not producing and lives off its cash.
- Financing. Initial capital of $2.43bn in the June study is more than ten times its cash.
- Permits. The revised plan of operations needs Bureau of Land Management approval after an environmental assessment or impact statement.
- Study risk. The economics come from an initial assessment, the least detailed type of study.
- Litigation. A stockholder suit filed on 23 September 2026 in the Delaware Court of Chancery, Assad v. Sprott, challenges how Eric Sprott gained a controlling position through 2025 financings, as well as bylaw changes and 2025 equity awards; three suits by warrant holders are also pending.
- Metal prices and reclamation. Undiscounted reclamation costs are estimated at $358.6m.
What to Watch Next
| When | What |
|---|---|
| Q4 2026 | Roasting versus pressure oxidation trade-off finalised; two more core rigs arrive |
| Q1 2027 | Release of the trade-off results |
| 15 March 2027 | Expiry of 36.81m warrants, convertible into about 3.68m shares |
| 16 March 2027 | CFO Stan Rideout moves to a strategic adviser role; a search for a new CFO is under way |
| H1 2027 | Heap-leach metallurgical test work due to finish |
| 2027 | Project optimisation, including the underground design |
Sources
- Hycroft Mining: Hycroft Reports Q3 2026 Results and Maintains Strong Balance Sheet (2026-10-27)
- U.S. Securities and Exchange Commission (EDGAR): Hycroft Mining Holding Corp. Form 10-Q for the quarter ended 30 September 2026 (2026-10-27)
- Hycroft Mining: Hycroft Delivers $10 Billion NPV From Technical Report at Spot Prices (2026-06-02)
- Hycroft Mining: Hycroft Drills New Best Hole Ever (2026-10-13)
- Hycroft Mining: Hycroft Provides Project Update, Unveils Refreshed Brand Identity (2026-09-21)
- Yahoo Finance: Hycroft Mining Holding Corporation (HYMC) historical prices (2026-11-13)
- Hycroft Mining: Hycroft Appoints Michael Deal as Chief Operating Officer (2026-07-15)