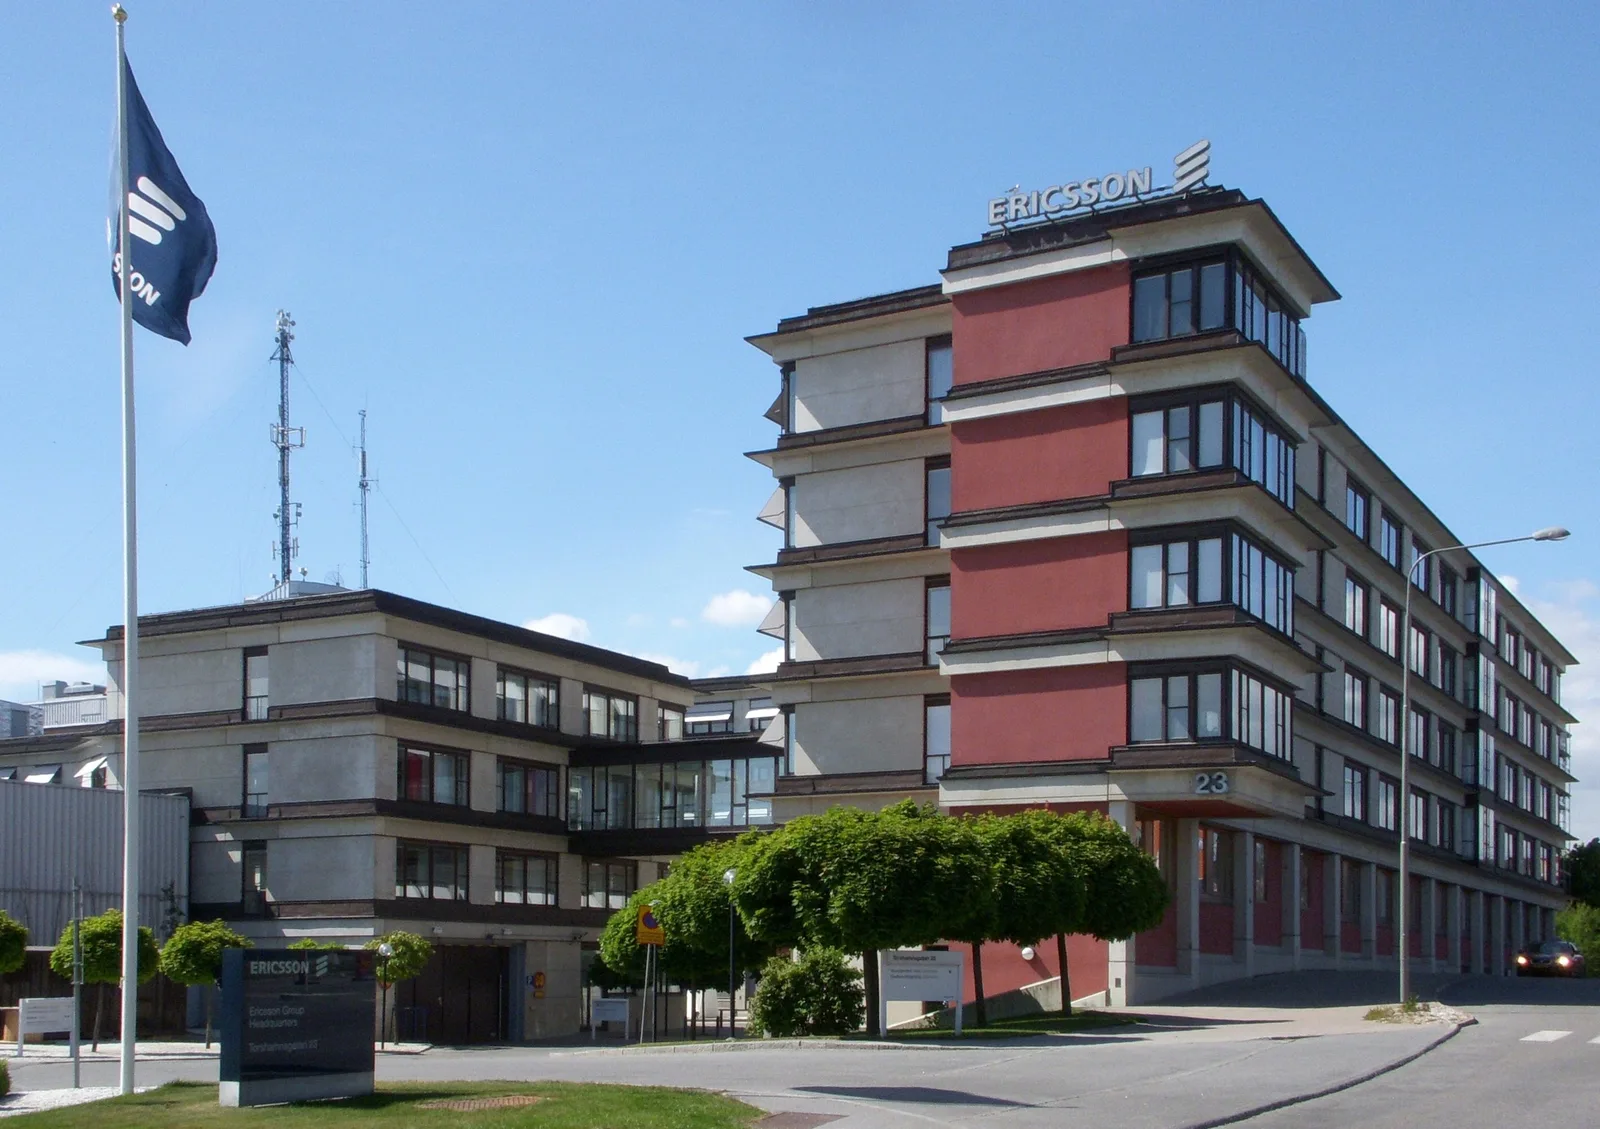
Ericsson's shares rose about 10 percent in Stockholm on 15 October after the Swedish network equipment maker reported a 6 percent rise in third-quarter sales, to SEK 59.5 billion, with organic growth of 7 percent. Net income halved, but only because the year-ago quarter included a large one-off gain.
The shares traded at SEK 107.25, up 10.45 percent, in Stockholm on the morning of the results. Investors looked past a cautious outlook in which chief executive Per Narvinger said the radio network market is flat and component costs will weigh on gross margins next year.
Sales Growth Led by Networks
Net sales rose to SEK 59.5 billion from SEK 56.2 billion a year earlier, and were 13 percent higher than in the second quarter. Stripping out currency moves and acquisitions, organic growth was 7 percent. That compares with organic growth of 4 percent for the first nine months, so the third quarter ran well ahead of the pace for the year as a whole.
Networks, the radio equipment business that sells to mobile operators, drove most of the growth. Three of Ericsson's four market areas grew organically. The networks margin also rose, helped by retroactive revenue from intellectual property rights, the licensing payments Ericsson collects on its patents.
The Enterprise segment's margin fell after the sale of iconectiv, while Cloud Software and Services held its margin steady.
Ericsson, third quarter 2026
- SEK 59.5bn net sales, up 6%
- 7% organic sales growth
- 17.0% adjusted EBITA margin
Why Profit Halved
The headline profit figures look weak but reflect a tough comparison. Net income fell 49 percent to SEK 5.8 billion from SEK 11.3 billion, and diluted earnings per share dropped to SEK 1.77 from SEK 3.33.
The third quarter of 2025 included a capital gain from a divestment worth SEK 1.72 per share. Without it, last year's earnings per share would have been about SEK 1.61, slightly below this year's figure.
| Measure | Q3 2026 | Q3 2025 |
|---|---|---|
| Net sales | SEK 59.5bn | SEK 56.2bn |
| Adjusted gross margin | 47.7% | 48.1% |
| Adjusted EBITA | SEK 10.1bn | SEK 15.8bn |
| Net income | SEK 5.8bn | SEK 11.3bn |
| Diluted EPS | SEK 1.77 | SEK 3.33 |
Adjusted EBITA, Ericsson's preferred measure of operating profit, was SEK 10.1 billion, a margin of 17.0 percent against 28.1 percent a year earlier. Excluding the prior-year capital gain, adjusted EBITA rose on the year.
The adjusted gross margin eased to 47.7 percent from 48.1 percent. Free cash flow before acquisitions was SEK 4.9 billion, down from SEK 6.6 billion, and the company ended the quarter with net cash of SEK 60.7 billion after buying back SEK 4.8 billion of its own shares.
A Cautious View of 2027
Narvinger said a consistent theme among the many customers he met during the quarter was the need for more intelligent and autonomous networks, and that Ericsson is already seeing efficiency gains from AI-enabled features deployed in operators' networks. "I am excited to lead the company in this period of rapid technology change," he said.
The outlook was more restrained. Ericsson described the market for radio access network (RAN) equipment as flat and said geopolitical uncertainty remains elevated. It expects higher component costs to be a headwind to gross margin next year, which would squeeze the profit Ericsson keeps from each krona of sales.
A Simpler Operating Structure
Ericsson also announced a simplification of its operating structure, which it said should sharpen customer focus, speed up decisions and bring efficiencies over time.
From 1 January 2027, a new Asia-Pacific market area will combine North East Asia, South East Asia, Oceania and India. Patrick Johansson, currently head of the Europe, Middle East and Africa market area, will lead it, and Ericsson will appoint a new head for that region.
The Business Area Enterprise Wireless Solutions will be broken up. Its neutral host and private 5G products will move into Business Area Networks, while its wireless WAN business stays standalone. Åsa Tamsons, who heads the unit, will leave that role on 31 December.
For investors, the quarter showed that Ericsson can grow sales even in a flat market, helped by patent income and operator spending on network upgrades. Whether that growth survives rising component costs is the question for next year's margins.