Ivanhoe Electric is trying to build a new underground copper mine in Arizona. Its Santa Cruz project has an updated preliminary feasibility study, local permits for early works and a preliminary letter for up to $1.1bn of US government-backed debt. It has not yet raised the money to build the mine, and the shares have fallen by nearly two thirds from their high of the past year.
What the company does
Ivanhoe Electric is a US mineral exploration and development company listed on the NYSE American and the Toronto Stock Exchange under the symbol IE. Robert Friedland is executive chairman and Taylor Melvin is president and chief executive.
Its main asset is the Santa Cruz copper project near Casa Grande, about 40 miles south of Phoenix. The company owns nearly 6,000 acres of private land there outright, including surface, mineral and water rights. It also holds the Tintic copper-gold project in Utah, a 50% exploration joint venture with Ma'aden in Saudi Arabia, a 90% stake in VRB Energy, a vanadium flow battery business, a 94.3% stake in Computational Geosciences, a data processing business, and 59.3% of Cordoba Minerals.
Ivanhoe Electric: share price, chart and news
The Santa Cruz plan
The 2026 preliminary feasibility study, published on 23 September, describes an underground mine with a 24-year life. It would produce about 75,000 tonnes of copper cathode a year on average over the first 15 years, using heap leaching and solvent extraction and electrowinning (SX-EW) to make 99.99% pure copper on site, with no smelter needed. The average grade over the mine life is 1.08% copper.
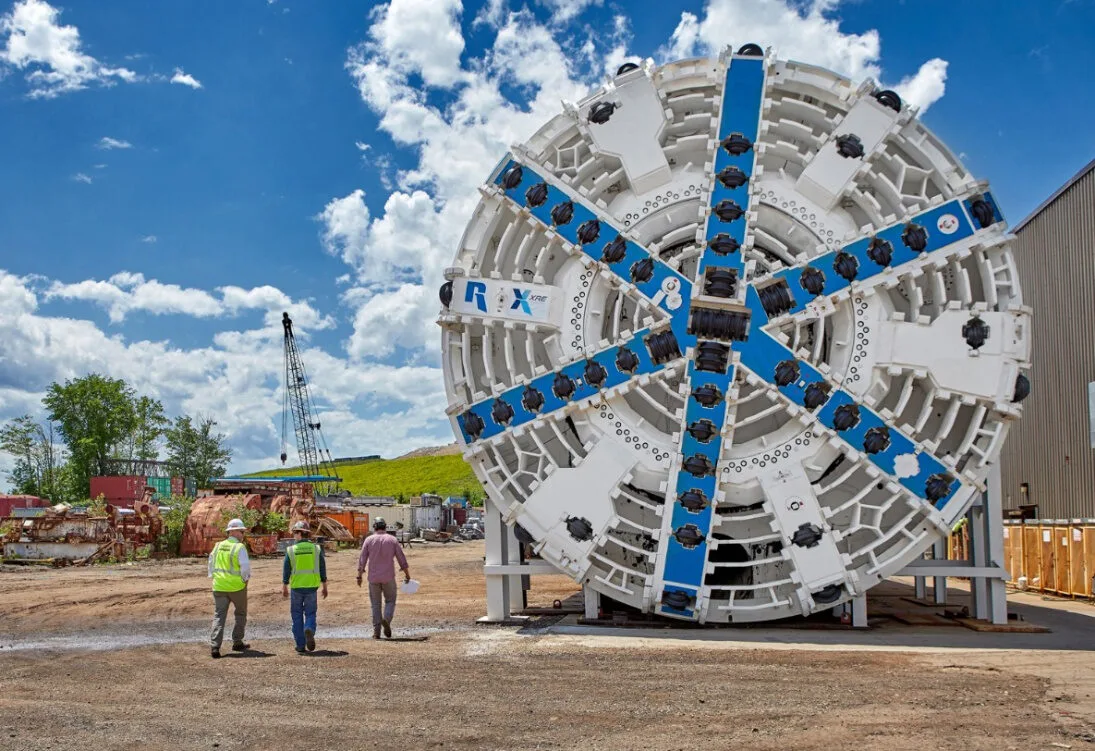
Access would be through a 4km decline cut by a tunnel boring machine. The 10-Q puts the machine's total price at $64.7m, of which $19.0m had been paid in deposits by 30 September.
| Santa Cruz 2026 study | Figure |
|---|---|
| After-tax NPV (8%), copper at $4.75/lb | $1.5bn |
| After-tax IRR, base case | 19% |
| Initial capital cost | $1.43bn |
| Average output, first 15 years | about 75,000 t of cathode a year |
| C1 cash cost / all-in sustaining cost, life of mine | $1.47/lb / $2.28/lb |
| Mine life | 24 years |
At the copper spot price of $6.79 a pound used in the study, the after-tax NPV rises to $3.5bn and the IRR to 30%. The mine plan uses only probable reserves. The company reports a further 1.44 million tonnes of contained copper in indicated resources outside the reserves and 3.33 million tonnes in inferred resources, which are not in the economics.
The latest numbers
Ivanhoe Electric does not earn revenue from mining. Its only revenue comes from data processing at Computational Geosciences: $708,000 in the third quarter and $2.29m in the first nine months of 2026, according to the 10-Q filed on 5 November.
The loss attributable to shareholders was $30.8m in the third quarter, or 19 cents a share, against $17.5m a year earlier. Over nine months that loss was much smaller at $13.7m, because the sale of Cordoba's Alacrán project in March produced a $124.7m gain. Spending on exploration and evaluation at Santa Cruz rose to $11.0m in the quarter from $4.4m a year earlier.
Balance sheet at 30 September 2026
- $214.8m cash and cash equivalents
- $90.5m cash used in operations in nine months
- 159.6m shares outstanding
Cash rose from $173.3m at the end of 2025, helped by Alacrán proceeds of $124.8m net of costs and cash disposed and $81.5m from warrants exercised in January and February at $7 a share. It has fallen since mid-year, from $256.9m at the end of June. Cash held by subsidiaries that are not wholly owned was $22.4m.
At the closing price of $7.66 on 10 November, the company's 159,626,671 shares are worth about $1.2bn. The stock has traded as high as $21.55 in the past year.
The main risks
Key risks
- Financing. The $1.43bn upfront cost is many times the cash on hand. The US EXIM letter for up to $1.1bn is preliminary and "does not constitute a financing commitment".
- Dilution. Any equity needed to complete the funding would dilute existing shareholders.
- Cost inflation. The 2026 study raised capital and operating costs compared with 2025, citing materials, labour, power and consumables.
- Execution. Tunnel boring, paste backfill and heap leaching at full scale all carry technical risk.
- Permits. The company holds city, county and state permits for surface works, the box cut and the start of the decline; any challenge or delay to approvals would push back the schedule.
- Copper price. The base case assumes $4.75 a pound; lower prices would cut the returns.
There are smaller balance sheet items to watch too. VRB Energy's convertible bond, carried at $35.9m, had its maturity extended to 31 December 2026; it converts into VRB equity earlier only if VRB raises equity or is sold. The share of losses from the Ma'aden joint venture reached $9.1m in the first nine months.
What to watch next
| When | What |
|---|---|
| From October 2026 | Box cut development at Santa Cruz, which the September study expected to start in October |
| 31 December 2026 | Maturity of the VRB Energy convertible bond |
| Spring 2027 | Expected final consideration by the US EXIM board |
| Summer 2027 | Planned start of tunnel boring |
| 2029 | Target for first copper cathode |
The NI 43-101 technical report for the study, dated 29 September, is posted on the company's website, where it is co-filed in Canada as a feasibility study. The company has also said it is in advanced talks on other financing options for Santa Cruz, without giving terms. How the rest of the $1.43bn is raised, and how much of it comes from new shares, is the biggest open question for shareholders.
Sources
- Ivanhoe Electric: Form 10-Q for the quarter ended 30 September 2026 (5 November 2026)
- Ivanhoe Electric: Form 10-Q for the quarter ended 30 June 2026 (7 August 2026)
- Ivanhoe Electric: 2026 Preliminary Feasibility Study for the Santa Cruz Copper Project in Arizona (23 September 2026)
- Ivanhoe Electric: Preliminary Project Letter from the Export-Import Bank of the United States (24 August 2026)
- Yahoo Finance: Ivanhoe Electric (IE) price history