Alstom shares lost more than a quarter of their value on Monday after the French train maker issued its second profit warning in seven months, cutting its margin target for the year from 6.5% to about 1% and warning that it will burn about €1.5 billion of cash, mostly because of delays on regional trains for Germany.
The stock closed in Paris at €11.685, down 26.09%, after falling as low as €10.89 during the session. At one point in the morning it was down 28%. Alstom was the worst performer in the SBF 120 index on a day when the CAC 40 rose 0.98% to 8,047.69. The shares have now lost 53.6% since the end of 2025, when they closed at €25.17.
A Much Weaker Year Than Promised
The warning came with preliminary, unaudited figures for the six months to 30 September. Orders held up, rising 5% to €11.0 billion, and sales rose 3% to about €9.3 billion. But the adjusted operating (EBIT) margin fell to about minus 4%, against 6.4% a year earlier, as the company booked gross margin adjustments on projects for Germany. Free cash flow for the half was an outflow of €1.248 billion, compared with €740 million a year earlier.
The full-year targets for the 12 months to March 2027 were cut across the board.
| Previous guidance | New guidance | |
|---|---|---|
| Adjusted EBIT margin | 6.5% | about 1% |
| Free cash flow | positive | about minus €1.5bn |
| Organic sales growth | about 5% | 2% to 4% |
| Railcar production | 4,400 to 4,500 | about 4,000 |
The new margin target assumes a recovery to about 6.5% in the second half. Alstom still expects its order intake to exceed sales over the year.
The Coradia Max Problem
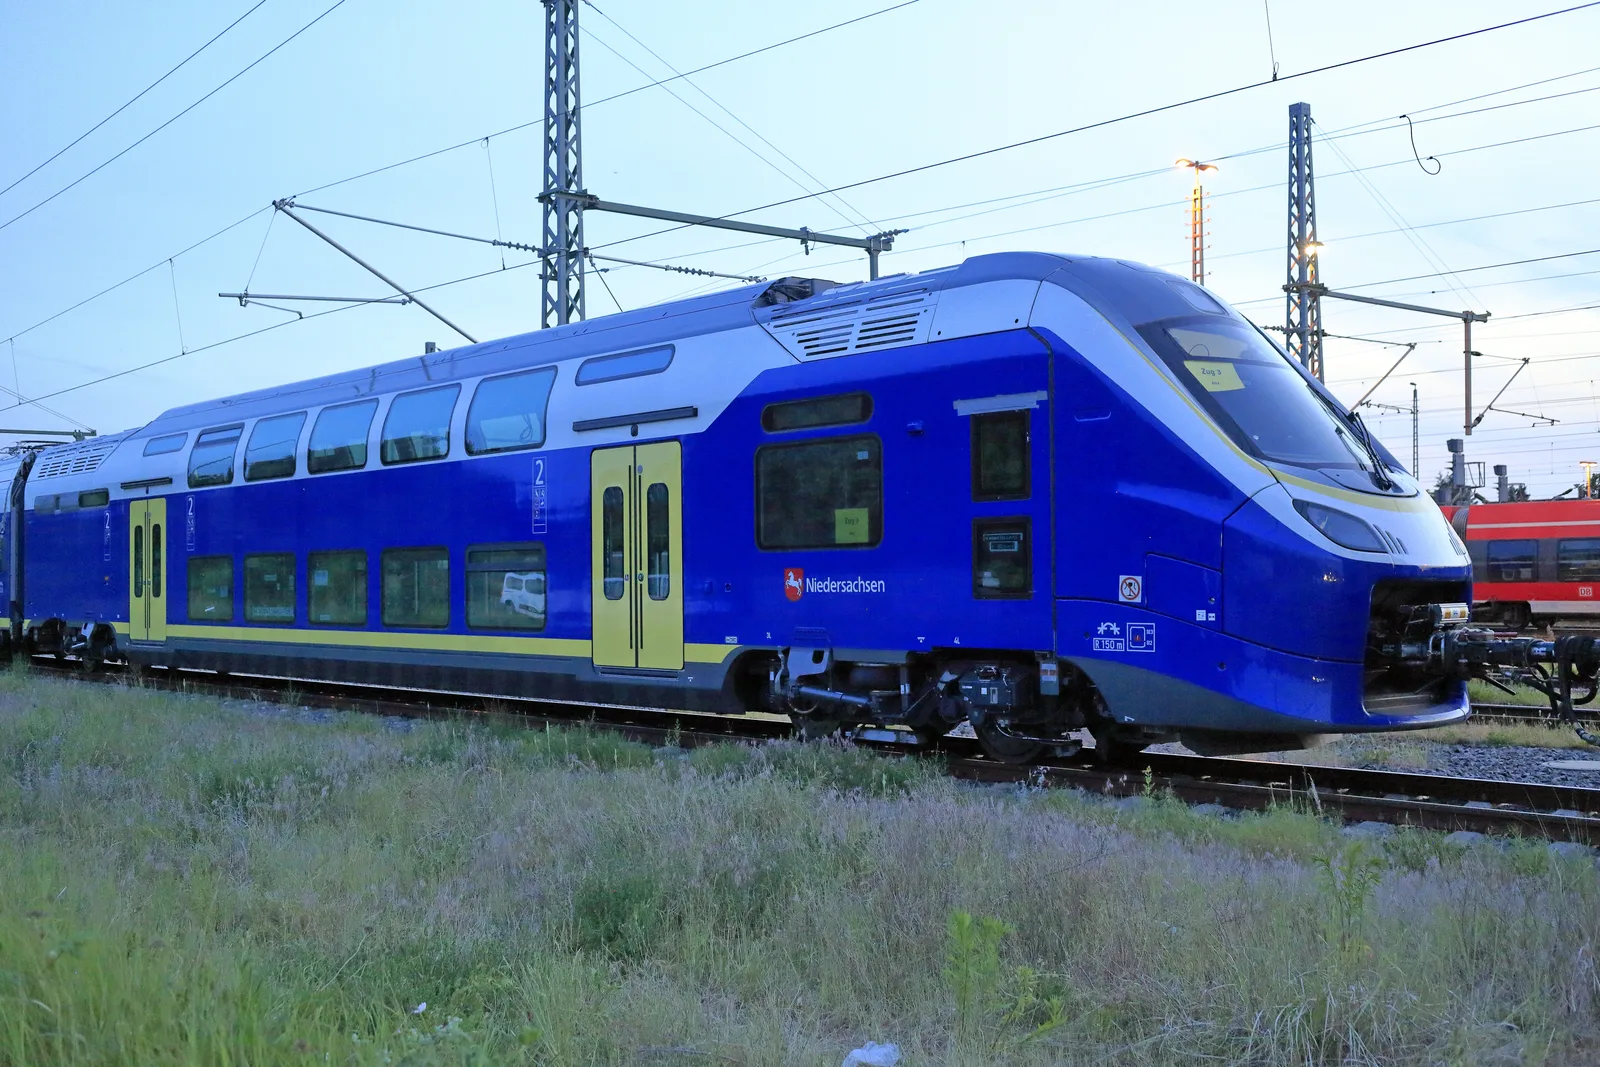
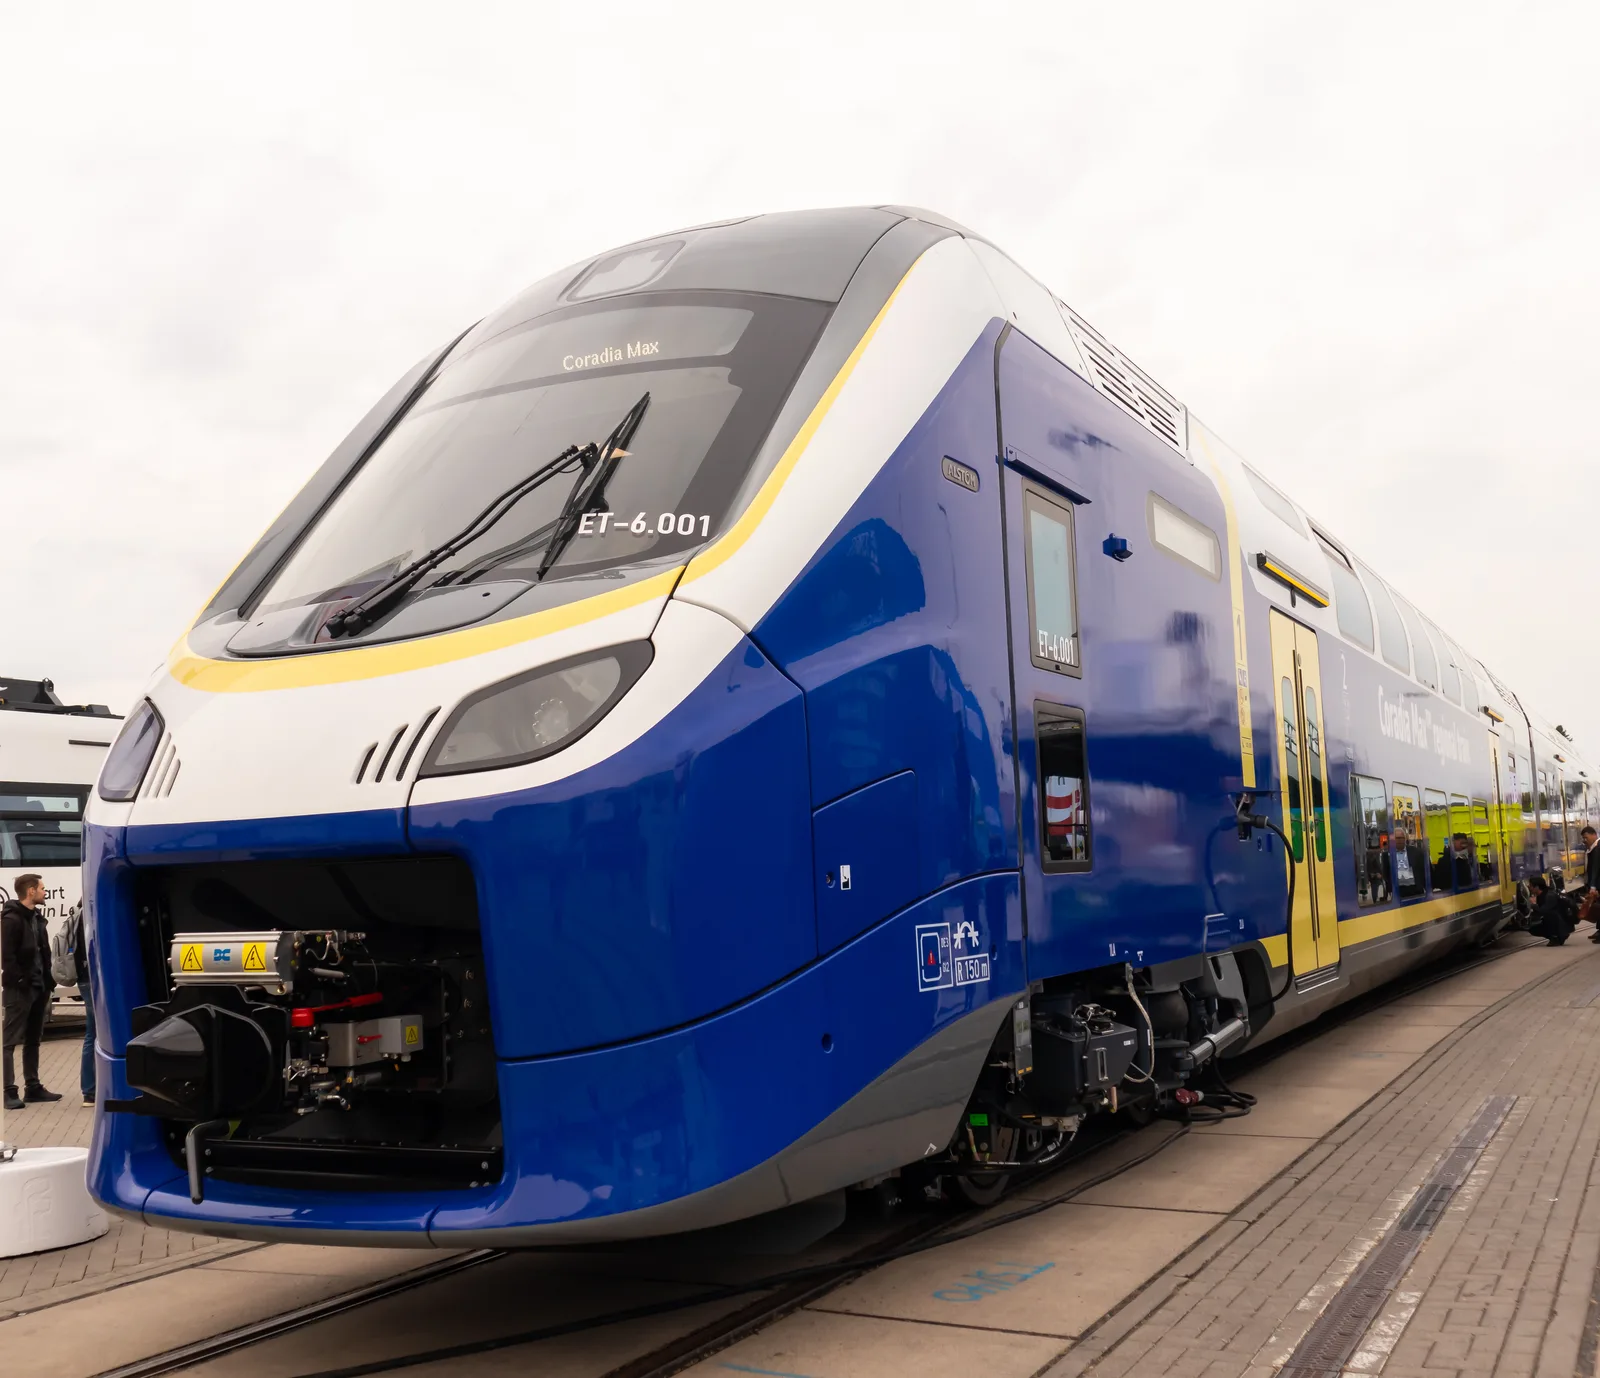
The cause is Coradia Max, a regional train platform sold to several customers in Germany and Central Europe. Six contracts, worth about €5 billion of the order book, are affected, and their gross margin is now negative.
Alstom found problems during testing. It paused work for more tests and to retrofit trains already built, then ran into further technical difficulties and new testing requirements. First deliveries have slipped by more than a year, to the first half of 2028. The six projects are now expected to enter commercial service between 2028 and about early 2030.
The delays push back milestone payments, which explains the cash hit, and trigger penalties from customers. Alstom is taking the full cost of the setbacks and their future effects upfront. UBS analyst Andre Kukhnin put the impact on the first-half margin at about €950 million, and chief financial officer Bernard Delpit said that covers both cost overruns and penalties.
Chief executive Martin Sion, who took over in April, blamed problems in development and project management. His first forecast cut, in April, also wiped more than a quarter off the share price.
Balance Sheet Comes Into Focus
Net debt rose to €1.1 billion at the end of September from €0.4 billion at the end of March. Alstom had €1.65 billion in cash and raised €694 million through a green hybrid bond in June. On 1 November it signed a new €2.0 billion revolving credit facility, running to November 2028 with no financial covenant, alongside an undrawn €2.5 billion facility and a €1.75 billion backup line.
What Alstom announced on debt
- The board has launched a review of all options, organic and non-organic, to cut debt by about €2 billion by September 2027.
- The aim is to keep an investment-grade credit rating.
- Decisions on the group's organisational model are expected in early 2027.
- Full half-year results are due on 17 November.
Analysts focused on the balance sheet. Oddo BHF put its outperform rating under review and said uncertainty over the balance sheet and the measures due by September would weigh on the shares for several months. Delpit said asset sales would make up most of the plan, and Sion said the group is not currently discussing a capital injection with the French state. Barclays analyst Vlad Sergievskiy asked whether the new forecast breaches the thresholds set by Moody's for margin, cash and debt; Delpit said the company is in open dialogue with the agency. AlphaValue described the warning as "catastrophique".
Why It Matters for Investors
Alstom is the world's second-largest train maker behind China's CRRC, and demand for rail is not the issue: orders keep coming in, including a €947 million maintenance contract with Greater Anglia and an €800 million metro deal in Hanoi announced in October. The problem is execution. The company has issued several profit warnings since 2021, partly linked to low-margin contracts inherited with Bombardier's rail business, and in 2023 and 2024 it cut guidance, sold assets and raised capital to bring debt down.
Two warnings in seven months under a new chief executive make it harder for investors to judge where the bottom lies. Management says it expects performance to normalise from the next financial year, with a medium-term adjusted EBIT margin of 8% to 10%. Investors will look for more detail on the debt plan and on the remaining project risk review on 17 November.
Sources
- The Irish Times: Luas maker Alstom shares fall 28% after train maker cuts profit forecast
- France Epargne: Alstom ramène sa marge annuelle à 1% et chute de 26% en Bourse
- Idéal Investisseur: Alstom lowers its annual targets
- RTTNews: Alstom H1 prel. revenue rises, cuts FY26/27 guidance
- ABC Bourse: Alstom passe à nouveau ses comptes à la paille de fer