TDG Gold's first economic study of its Shasta gold and silver project in British Columbia values a 9.9-year open-pit mine at C$1.18bn after tax, but it assumes silver at US$50 an ounce, and silver closed the week at US$41.08. The mine would cost C$604.9m to build, more than five times the C$110m the TSX Venture company expects from selling a stake in a neighbouring property, and most of the resource tonnes sit in the least certain Inferred category.
Shasta PEA in three numbers
- C$1.18bn after-tax NPV at a 5% discount rate, at US$3,550 gold and US$50 silver
- C$604.9m initial capital, with an accuracy range of 30% below to 50% above
- US$41.08 Friday's silver close, 18% below the study's price
What TDG Gold's Shasta study says
TDG Gold published the preliminary economic assessment, or PEA, on Tuesday 17 November. A PEA is the first and roughest study on the road to a mine. This one joins Shasta with the much smaller, higher-grade Mets deposit, both in the Toodoggone district of north-central British Columbia.
Two open pits would feed one mill of 4m tonnes a year, producing about 71,200 ounces of gold and 2.82m ounces of silver a year for 9.9 years. All-in sustaining costs, the running cost per ounce including upkeep, are put at US$1,283 per gold-equivalent ounce. Payback is 1.8 years from first production and the after-tax internal rate of return is 38.8%.
"The PEA defines what we can evaluate economically today," Paul Geddes, TDG's senior vice-president of business development and strategy, said in the release.
Why the silver price matters more than gold for Shasta
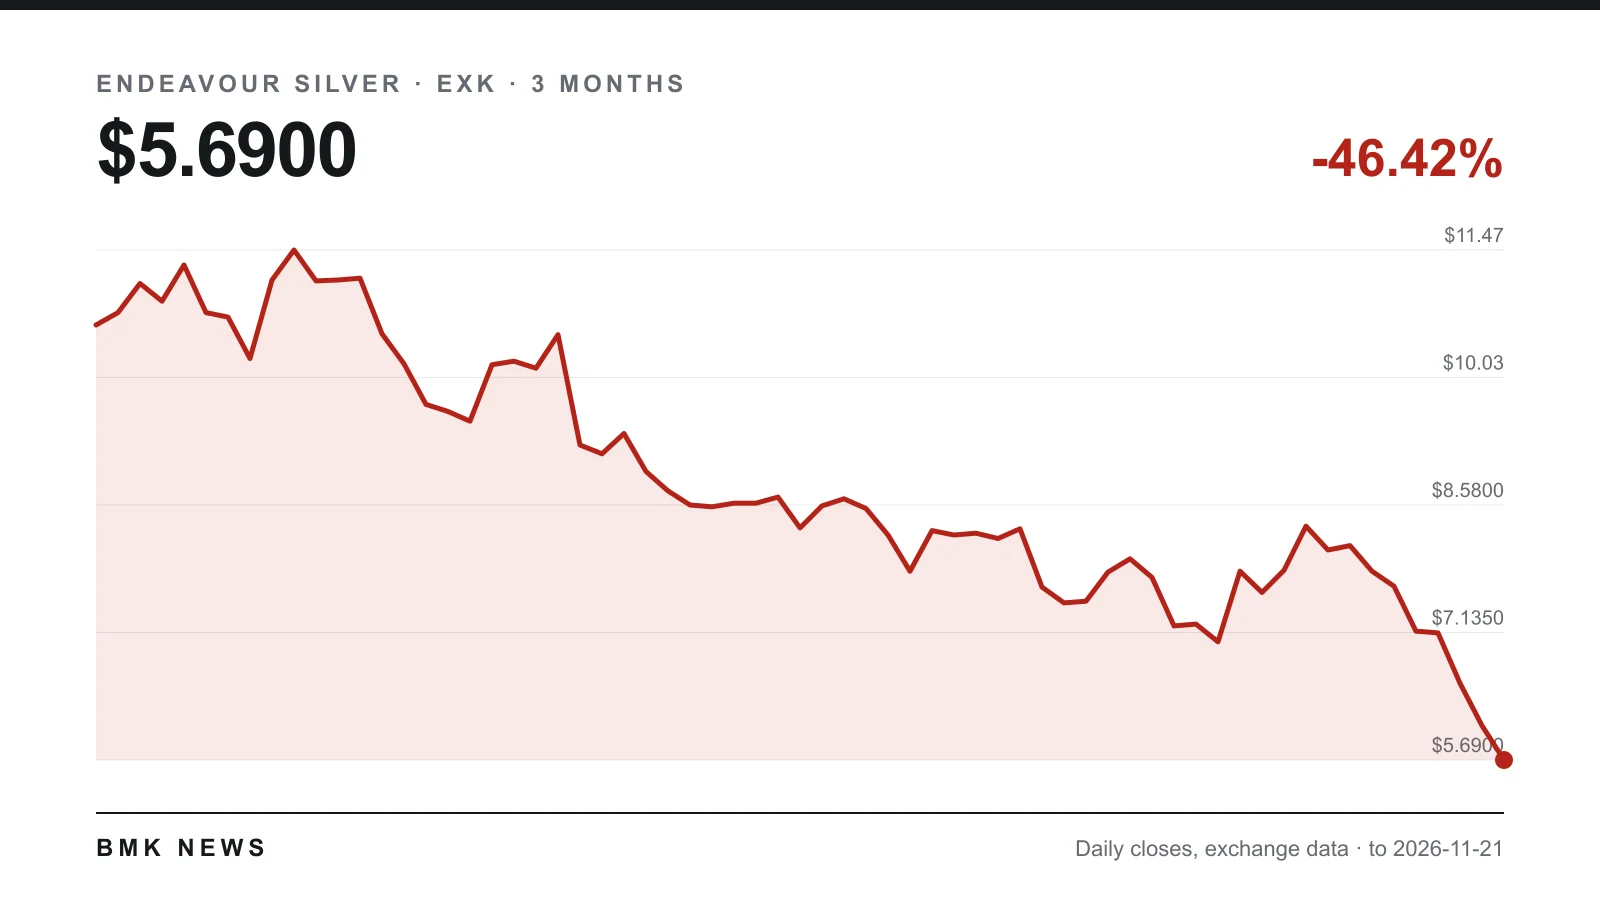
Gold closed on Friday at US$3,525.75, according to Investing News Network, within 1% of the study's US$3,550 even after gold's slide to its lowest since September 2025. Silver is the problem. It fell 18% in the week to US$41.08, and it supplies about 36% of Shasta's life-of-mine revenue at base-case prices.
The company's sensitivity table moves both metals together:
| Case | Gold (US$/oz) | Silver (US$/oz) | After-tax NPV | IRR |
|---|---|---|---|---|
| Base case | 3,550 | 50 | C$1.18bn | 38.8% |
| Prices 10% lower | 3,195 | 45 | C$942m | 33.0% |
| Prices 20% lower | 2,840 | 40 | C$703m | 26.7% |
On a straight-line BMK News reading of that table, Friday's prices cut revenue by about 7%, pointing to an NPV nearer C$1.0bn. The release also converts silver into gold-equivalent ounces at 71 to 1; on Friday the ratio was about 86 to 1. On our arithmetic that trims annual output to about 104,000 gold-equivalent ounces and lifts the cost per ounce to roughly US$1,370. That is why silver's slide to a yearly low hurts Shasta more than the gold price suggests.
How much of the Shasta resource is Inferred
The new resource has 17.12m tonnes Indicated and 27.37m tonnes Inferred across Shasta and Mets, so about 62% of the tonnes are Inferred, material the release calls "too speculative geologically" to become reserves. The plan schedules 38.21m tonnes of mill feed, more than twice the Indicated tonnage, and the release does not say how much of that feed is Inferred.
No new drilling has gone in since the December 2024 estimate. The company says higher metal price assumptions lowered the cut-off grade and enlarged the conceptual pit, adding lower-grade tonnes. Higher prices made the deposit bigger on paper; lower prices work in reverse.
How TDG Gold could pay for a C$605m mine
TDG had 281.3m shares in issue on 20 October and 305.6m fully diluted, counting 18.7m options and 5.6m warrants, according to its capital structure page. Its main source of new money is the deal it signed on Thursday 12 November to sell 51% of its Aurora West property to Freeport-McMoRan for C$110m in cash. Freeport can raise its stake by spending a further C$80m on exploration and paying TDG another C$40m. The sale needs TSX Venture Exchange approval, the restructuring behind it is expected in December, and Shasta stays 100% with TDG.
The C$110m covers about 18% of the build cost. The capital estimate is a Class 5 figure, accurate to between 30% below and 50% above, so the bill could reach about C$907m, all spent in the two years before production. The release itself warns that the capital figure does not necessarily represent the total outside financing needed. Koryx Copper's Haib study, priced at $5 copper, shows the same pattern this month.
The bull case and the bear case
- Bull: even with both metals 20% lower, the NPV of C$703m is 1.2 times the initial capital.
- Bull: a low strip ratio, conventional flotation, road access and C$110m of new cash without new shares if the Freeport deal closes.
- Bear: silver already sits near the study's downside case, and most resource tonnes are Inferred.
- Bear: no permit for a full mine, and a build bill more than five times the cash in prospect.
The permits Shasta still needs
The existing Mines Act permit covers about 175 hectares of historical workings, not the full project. TDG needs a provincial environmental assessment certificate, a federal impact assessment decision, an amended Mines Act permit, a discharge permit and a Fisheries Act authorisation to divert Jock Creek from year four, which the release calls a material engineering and permitting consideration. The company also says its existing relationships with First Nations do not amount to consent for the larger development.
Shares of juniors this far from production tend to swing harder than the metal, as our explainer on why gold miners fall harder than gold sets out.
What to watch next at TDG Gold
TDG says the NI 43-101 technical report will be filed on SEDAR+ within 45 days of 17 November, which points to about 1 January. Next come TSX Venture approval and the closing of the Freeport sale, then how TDG spends the money. The silver price against the study's US$50 is the number to track.
What is TDG Gold's Shasta project worth?
TDG Gold's PEA of 17 November 2026 puts Shasta's after-tax NPV at C$1.18bn at US$50 silver, or C$703m if gold and silver are both 20% lower.
How much will the Shasta mine cost to build?
Initial capital is C$604.9m, including C$92.6m of contingency, and the estimate could be 30% lower or 50% higher.
When is the TDG Gold Shasta technical report due?
TDG Gold says the NI 43-101 technical report will be filed within 45 days of 17 November 2026, by about early January 2027.
Sources
- TDG Gold: TDG Announces Preliminary Economic Assessment for the Shasta Au-Ag Project
- TDG Gold (release via BNN Bloomberg): TDG Announces Preliminary Economic Assessment for the Shasta Au-Ag Project
- TDG Gold: Agreement to sell 51% of the Aurora West Property to Freeport-McMoRan
- TDG Gold: Capital Structure
- Investing News Network: Top 5 Canadian Mining Stocks This Week: Star Diamond Gains 33 Percent